


AI agents and payments
Agentic commerce payments on rails that already authorize and settle
Agentic Commerce is for businesses in the USA. Developer evaluating agent-initiated purchases, permission boundaries and production readiness; separate released functionality from concepts. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- MCP server and REST payments API
- Authorization and settlement unchanged
- Same records as every other channel

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
Software teams adding an assistant
You are putting an agent in front of a checkout, a booking or a renewal, and it needs to take the payment without a second system holding the card.
Merchants asked about AI checkout
Customers or partners are asking whether an agent can buy from you. This is the honest answer about what works today and what does not.
Platforms with their own agents
You already call the RapidCents API. The MCP server is the same surface, described so a model can use it without you writing an adapter per assistant.
Core capabilities
RapidCents MCP Server
An agent that speaks the Model Context Protocol reaches the same payment operations a developer would call directly, without a bespoke adapter per assistant.
The same payments API
Agents do not get a side door. They use the REST API that terminals, checkout and your own software use, so there is one set of behaviours to reason about and one place a payment can come from.
Signed webhooks
Outcomes arrive as signed events rather than something an agent has to poll for or assert. The signature is what lets your system trust that the result came from RapidCents and not from the agent.
Tokenized credentials
Card data is replaced by a token held in the RapidCents vault. A token is the control surface: it can be constrained, and it can be revoked without touching the underlying card.
Idempotent requests
An agent that retries — because a model timed out, or a step ran twice — must not create a second charge. Idempotency keys make a repeated request return the original result instead of a duplicate payment.
A sandbox with documented test cards
Agent behaviour is worth rehearsing before it touches real money, including the declines and timeouts, because those are the paths an autonomous caller reaches most often.
One settlement trail
An agent-initiated payment appears in the merchant dashboard beside terminal and online sales, refunds the same way, and reconciles into the same deposit.
How it works
Decide which operations an agent is allowed to reach, and which stay with a person.
Connect the agent through the RapidCents MCP Server, or call the payments API directly if you are building the agent yourself.
Issue the agent a scoped, tokenized credential rather than a card number, so what it can do is bounded and revocable.
Rehearse in sandbox with documented test cards, including declines, timeouts and a repeated request that must not double-charge.
Go live and watch the same dashboard: agent-initiated payments settle and reconcile alongside every other channel.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
A practical view covers narrow US scenario where an assistant prepares a purchase and a customer grants the required payment authority. Name the agent, application, RapidCents interface and trusted result. Label production features, pilots and conceptual demonstrations clearly; protocol support alone does not establish complete autonomous purchasing. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Agentic Commerce does not, by itself, prove delivery or win a dispute.
The problem and the limit
The workflow should require documented spending authority, scoped credentials, idempotency and independently verified outcomes wherever implemented. Show timeout, repeated-request and changed-amount tests, plus revocation and human escalation. In practice, that the agent does not approve its own charge and that the integrating application has control responsibilities. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Agentic Commerce does not, by itself, prove delivery or win a dispute.
What to confirm
Before you rely on this, confirm US production availability of the actual MCP/API surface, supported methods/currencies and account prerequisites. Name responsibilities for customer consent and payment actions. Avoid universal assistant compatibility, worldwide merchant eligibility or an implied bypass of underwriting and authentication requirements. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Agentic Commerce does not, by itself, prove delivery or win a dispute.
Questions about Agentic Commerce
What is agentic commerce?
Agentic commerce is a purchase an AI agent starts on a person's behalf: the agent finds the item, chooses it and initiates the transaction, while the payment system authenticates, authorizes and settles it. The division is the important part. The agent forms intent; it does not approve the charge.
Can an AI agent authorize its own payment on RapidCents?
No. An agent presents a credential a person granted it, and RapidCents performs authentication, authorization and settlement exactly as it does for a terminal or a checkout. There is no path where an agent approves its own charge, and any vendor claiming otherwise is describing their own terms rather than an industry rule.
What can an AI agent do in a RapidCents payment workflow for USA merchants?
For a business in the USA, list released operations and permission limits; distinguish preparing a request from authentication, issuer authorization and settlement. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How is a duplicate or unauthorized agent payment prevented?
For a business in the USA, the practical view covers implemented approval, amount, credential and idempotency controls with test evidence; identify application-owned safeguards. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Is this integration ready for production on my US account?
For a business in the USA, state actual availability, prerequisites, supported interfaces and sandbox-to-production review. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
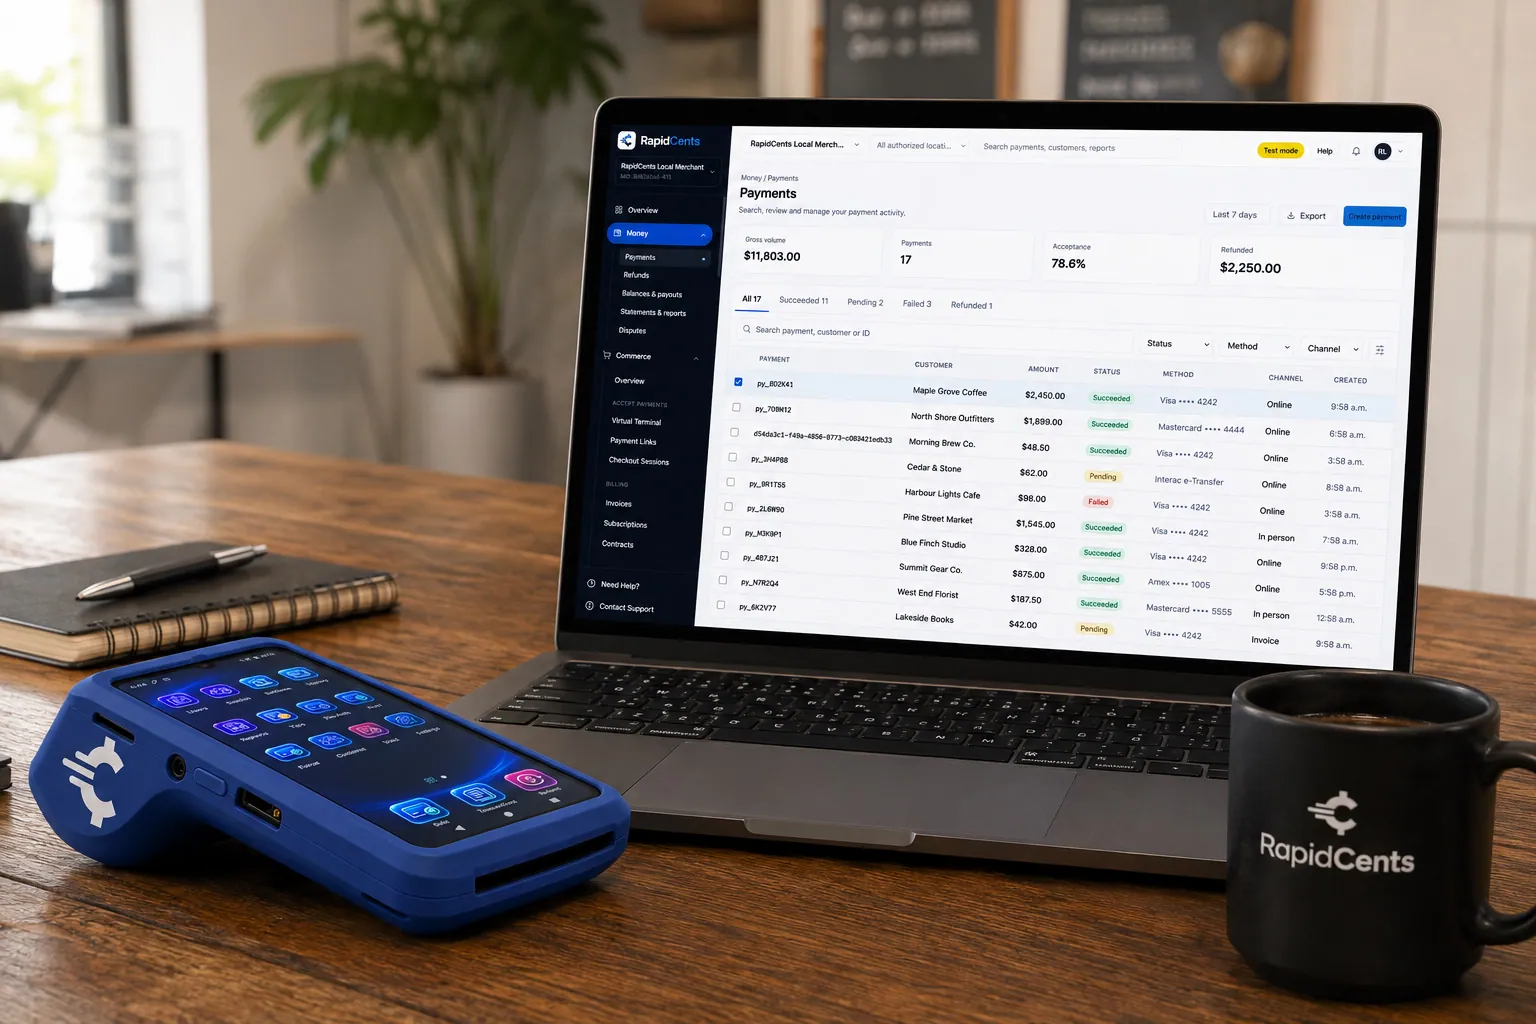
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and…
Explore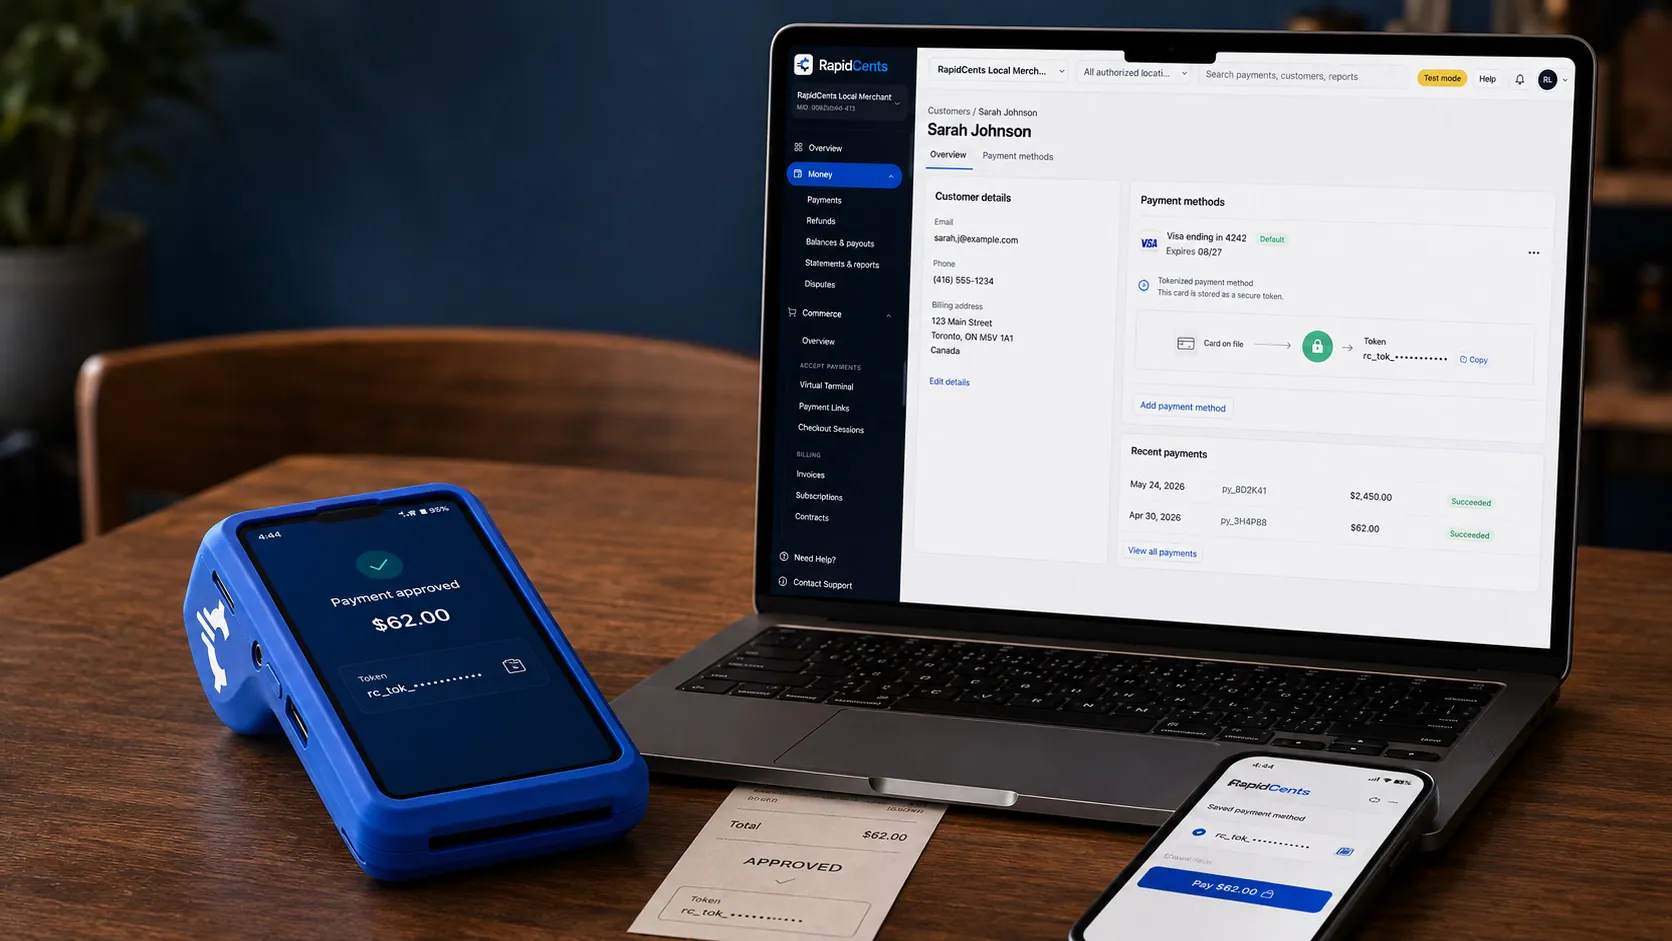
A stored RapidCents token stands in for the card number, with the terminal that captured the original credential beside it. Payment Tokenization
Tokenization exchanges a card number for a reference your software can store and reuse. Repeat…
Explore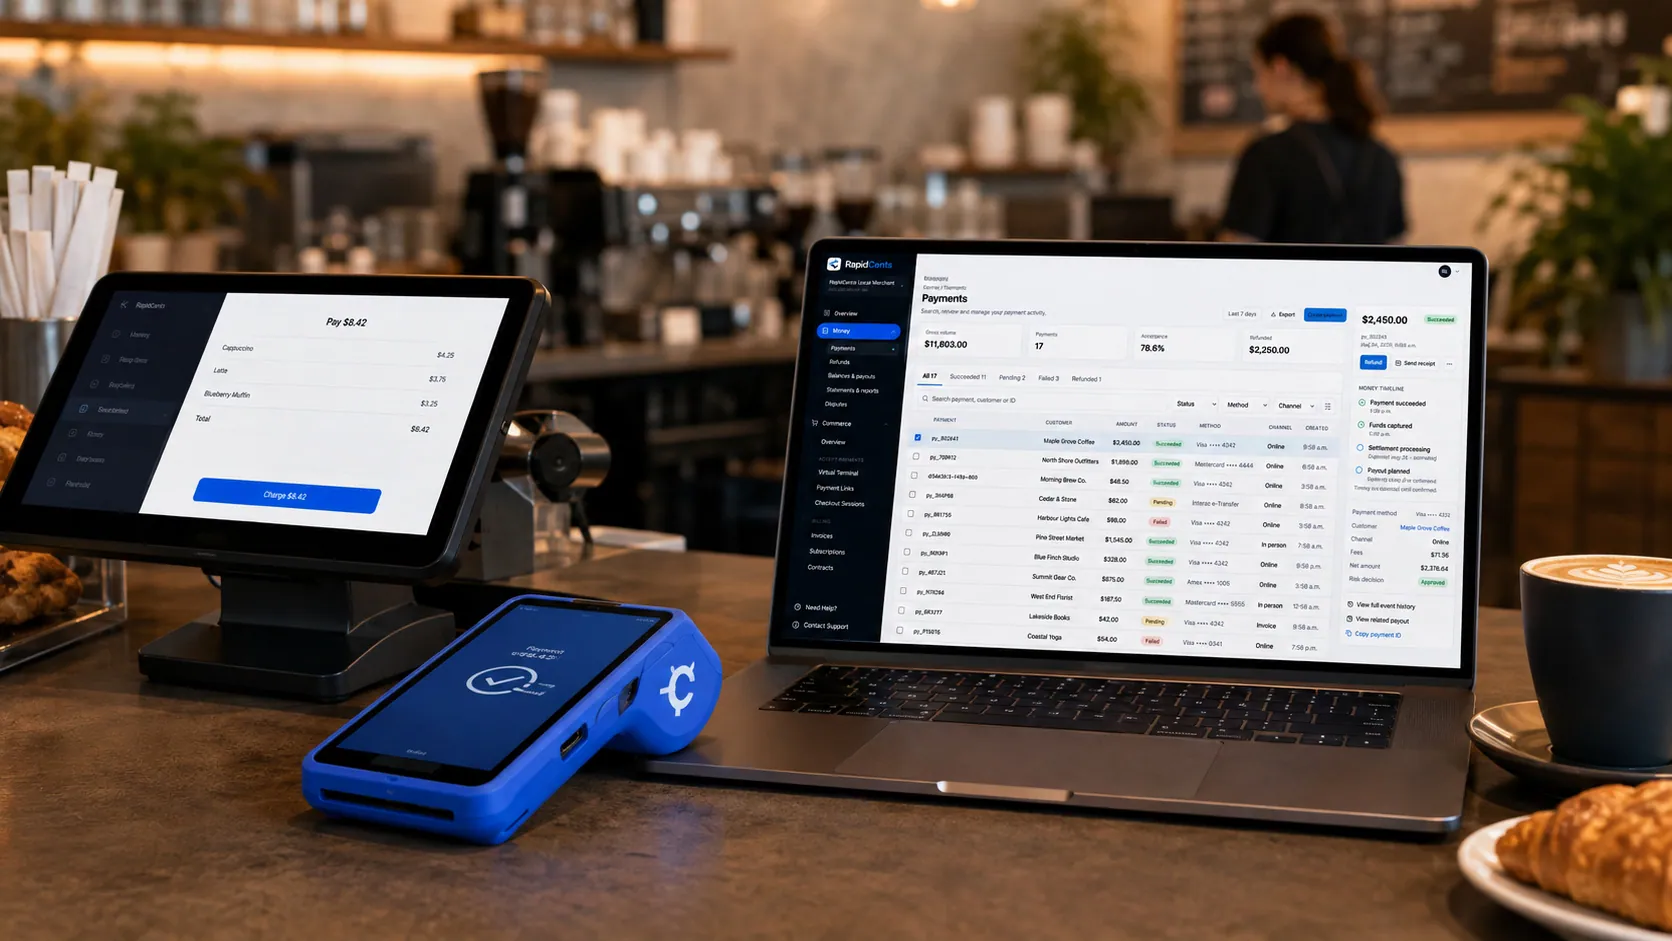
Payments taken inside existing business software through RapidCents, with the terminal and dashboard in the same workspace. Integrated Payments
RapidCents integrated payments connect certified POS and ERP systems so sale amounts, tips, refunds…
Explore


Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



