


Authentication where it earns its place
Add cardholder authentication without adding friction to every sale
3-D Secure is for businesses in the USA. US ecommerce operator evaluating cardholder authentication and checkout friction; distinguish authentication from broader fraud screening. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Issuer-verified cardholders
- Liability shift where it applies
- Rules, not blanket friction

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
Online merchants
Card-not-present sales carry the fraud liability.
International sellers
Some regions expect authentication by default.
High-ticket sellers
Larger orders justify the extra step.
Core capabilities
Risk-based rules
Trigger authentication by amount, geography or risk signal instead of every transaction.
Frictionless flow
Most authentications complete without a challenge screen.
Liability shift
Where authentication succeeds and the rules apply, fraud liability moves to the issuer.
Checkout integration
Works with hosted checkout and gateway integrations.
Outcome reporting
See authentication rates and their effect on approvals.
How it works
Set the rules that decide when authentication runs.
At checkout, the issuer evaluates the transaction.
Most authentications complete without a challenge.
A challenge appears only where the issuer requires it.
Reporting shows authentication and approval outcomes.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with 3D Secure
Capabilities on the same account, so the parts below connect without a second integration or a second contract.
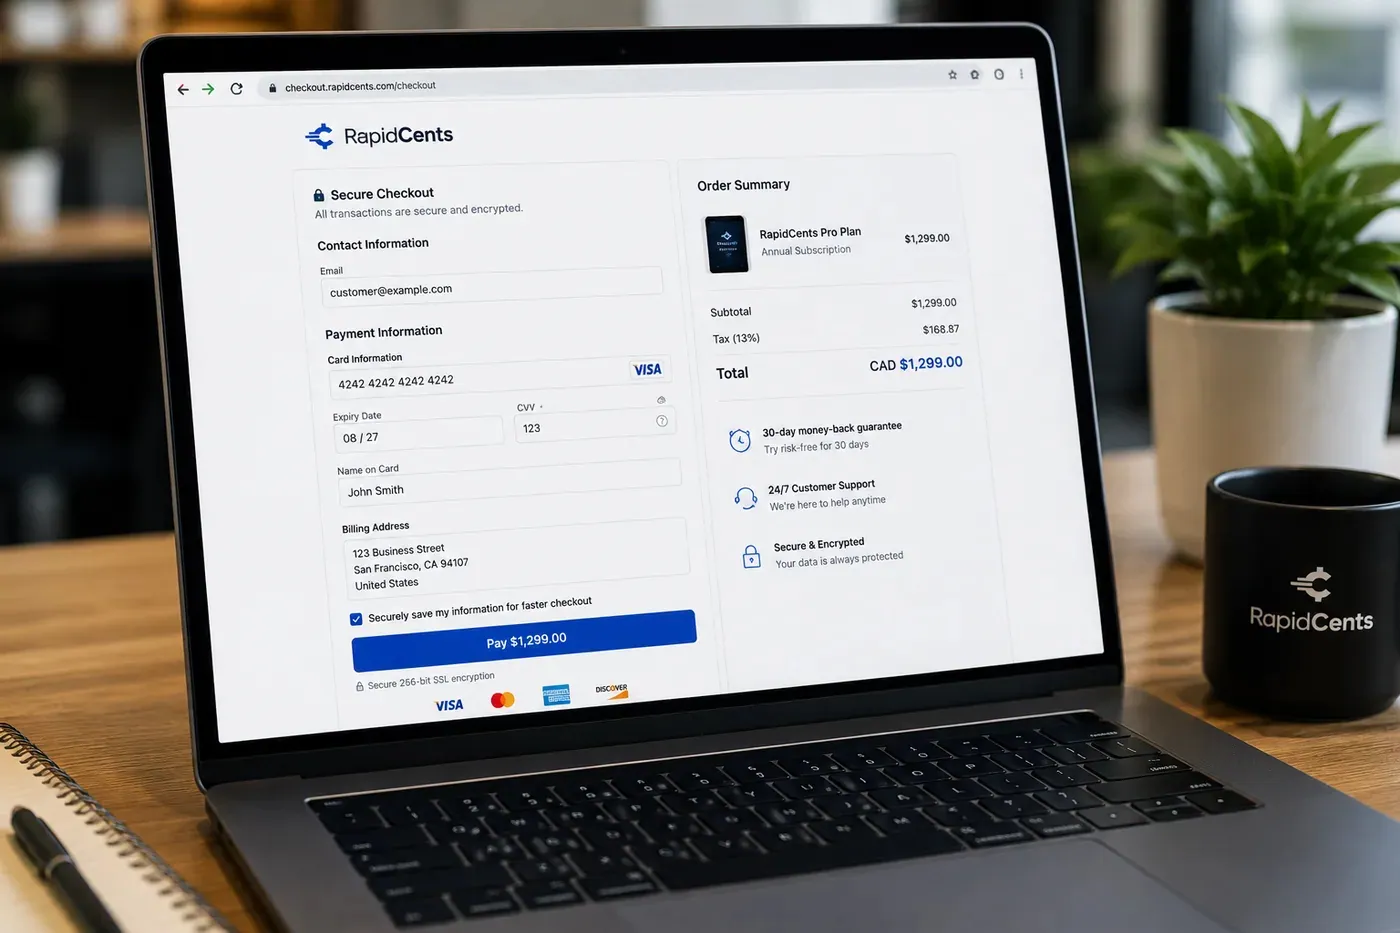
A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted checkout
A branded payment page RapidCents hosts, which keeps card data off your servers.
Explore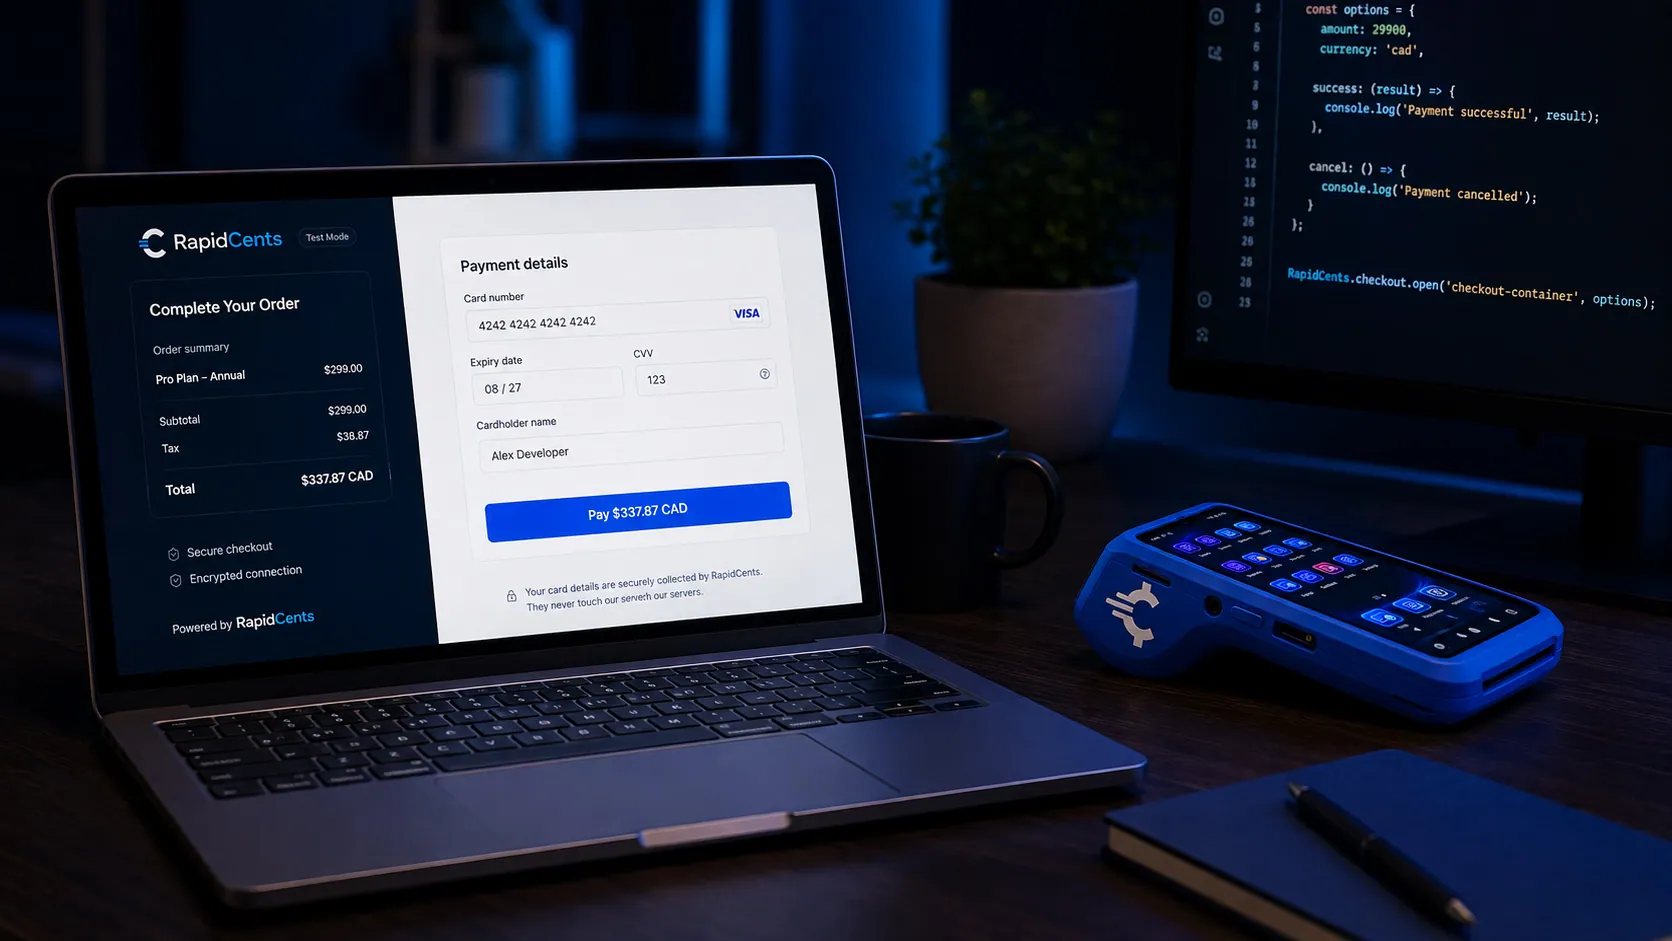
Rapid.js hosted card fields on a developer workstation, keeping card entry out of the merchant's PCI scope. Rapid.js
Embedded card fields that keep your checkout in your own design and out of PCI scope.
Explore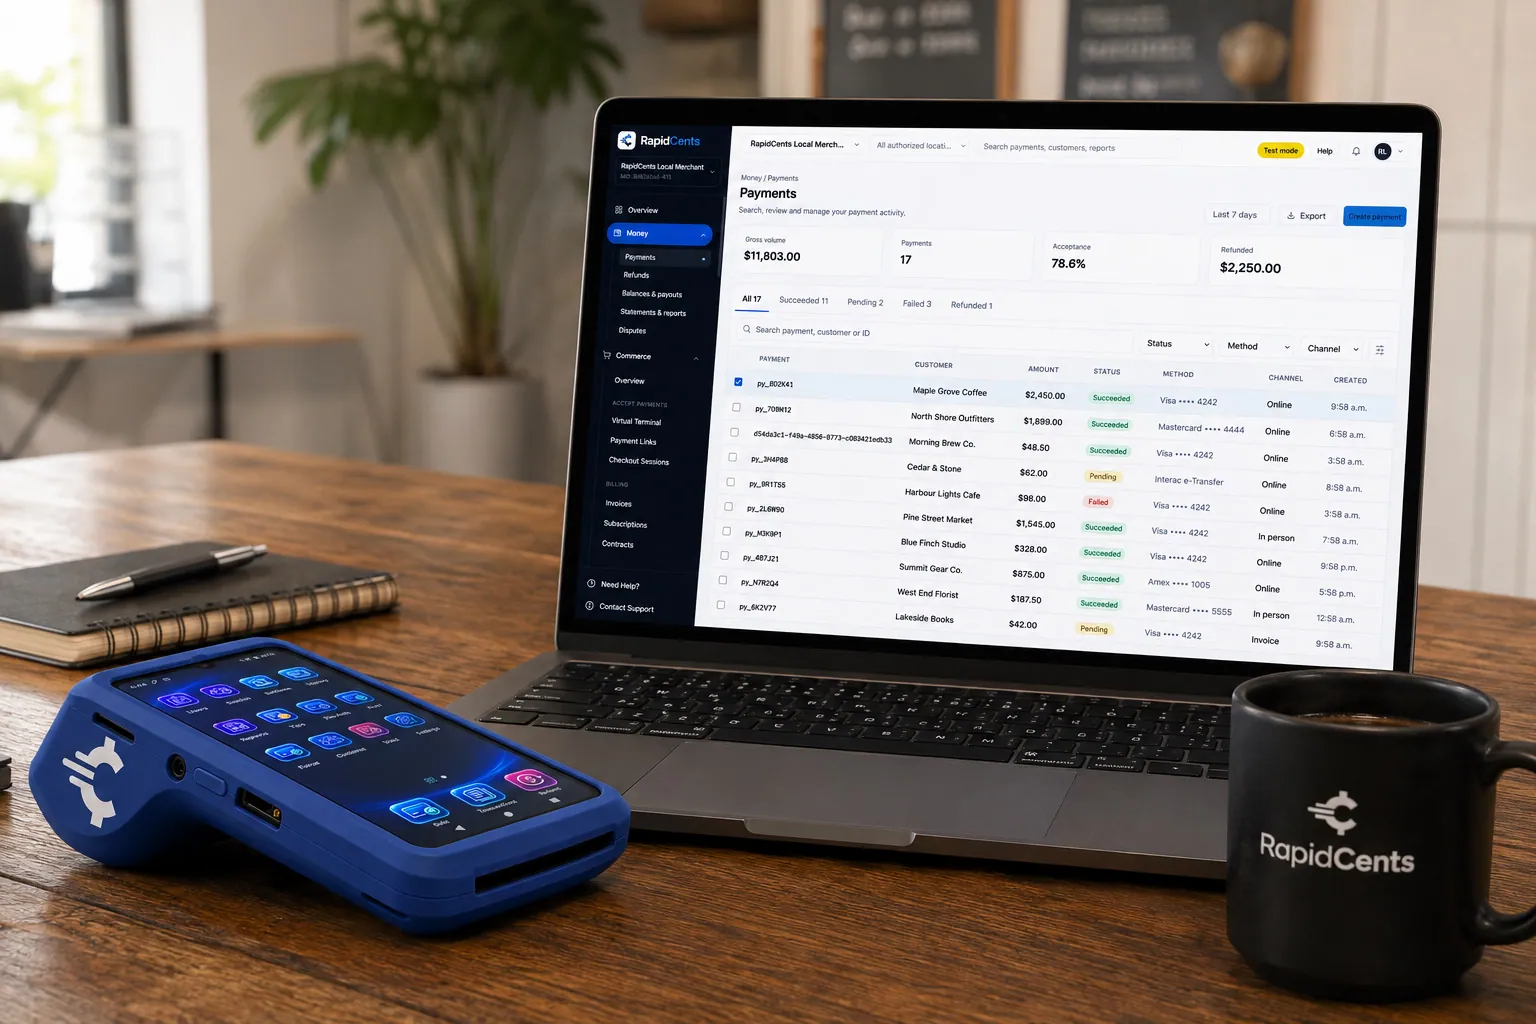
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment gateway
The authorization layer every online RapidCents payment runs through.
Explore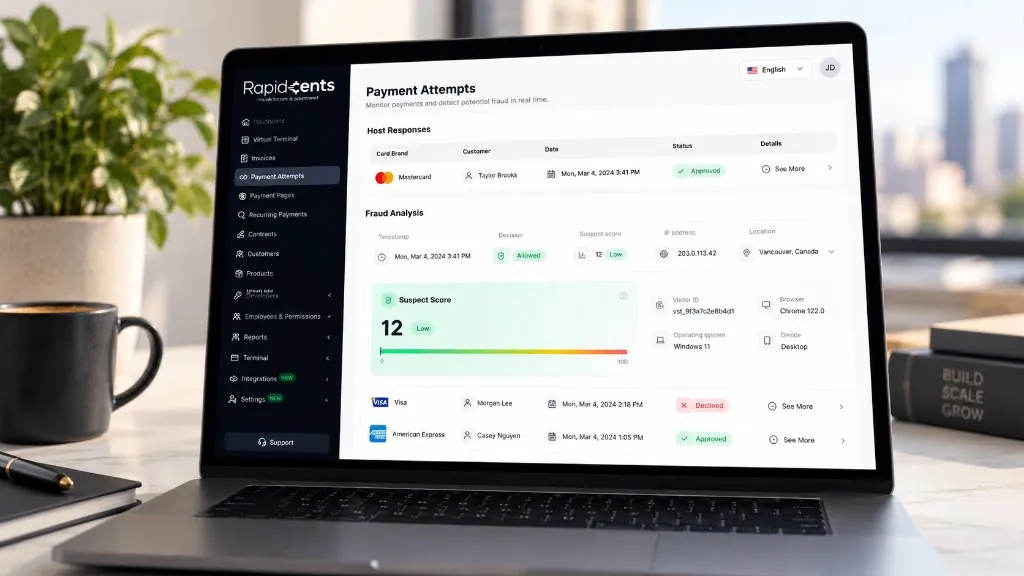
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud prevention
More than 180 signals checked on every payment attempt in under a second, and a fraud score you decide on.
Explore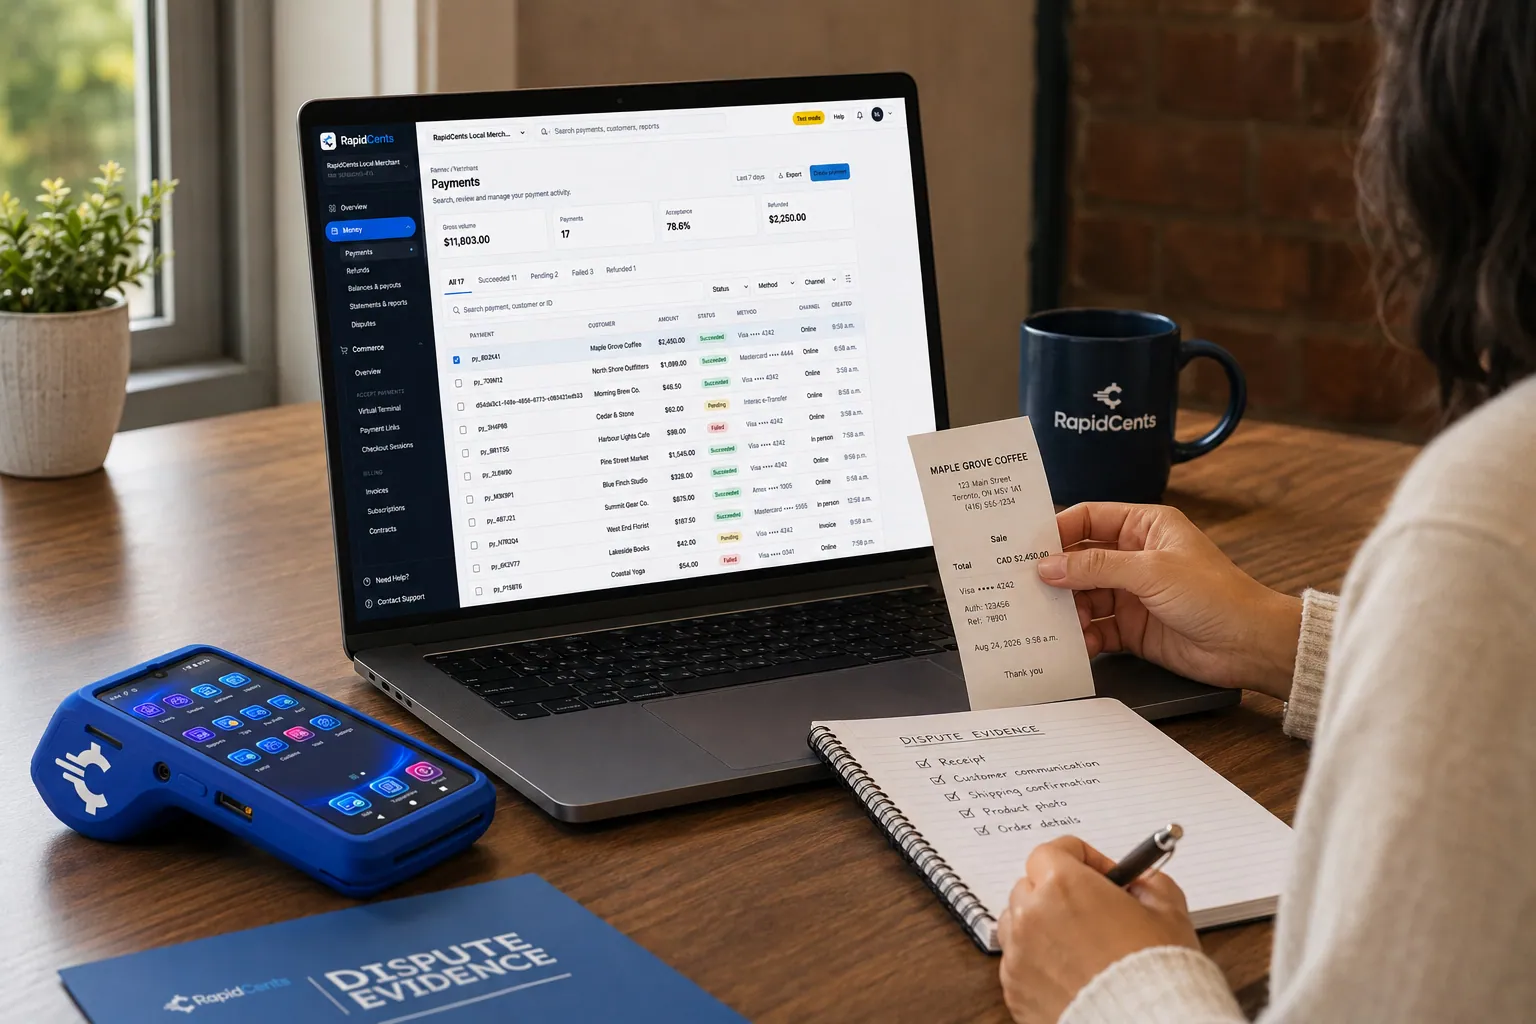
RapidCents assembles chargeback evidence from the original sale, with the terminal and receipts still at hand. Chargeback Protection
Dispute alerts and evidence assembly, so representment does not eat your week.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
A US web purchase moves from checkout submission through issuer authentication and the payment result. Cover when a customer may see a challenge, how the merchant receives the outcome and which verified checkout paths support it. Use an approved screen sequence instead of implying every payment is challenged. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. 3-D Secure does not, by itself, prove delivery or win a dispute.
The problem and the limit
Keep separate cardholder authentication from payment authorization. Record supported versions, failed or abandoned challenges and fallback behavior. Have risk approve any liability-shift conditions and evidence requirements; neither authentication nor a technical integration guarantees an approved payment or a successful dispute response. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. 3-D Secure does not, by itself, prove delivery or win a dispute.
What to confirm
Before you rely on this, confirm US account availability, supported brands, international-cardholder handling and checkout integrations. In practice, enrollment and rule configuration, including presentment and settlement currency implications. Do not import Canadian payment-method labels or a blanket authentication mandate into the US page. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. 3-D Secure does not, by itself, prove delivery or win a dispute.
Questions about 3D Secure
Does 3-D Secure hurt conversion?
Applied to every transaction it can. Rule-based triggering limits it to the transactions where the protection is worth the step.
What is liability shift?
Where authentication succeeds and network rules apply, liability for a fraudulent chargeback moves to the issuer.
Will customers always see a challenge?
No. Most authentications complete in the background without a challenge screen.
Does it work with hosted checkout?
Yes, and with gateway API integrations.
Does 3-D Secure apply to in-person payments?
No. It authenticates the cardholder in a card-not-present checkout, which is where the merchant carries the fraud liability. In-person sales are protected by the chip and the terminal's own encryption instead.
Which transactions should trigger authentication?
The ones where the protection is worth the extra step: larger orders, regions whose issuers expect authentication by default, and transactions your risk signals flag. Authentication and approval reporting is what tells you whether a rule is set too wide.
When would a customer see a 3-D Secure challenge on a USA checkout?
For a business in the USA, in practice, the supported flow, merchant-configurable rules and issuer decisions; distinguish frictionless results from interactive challenges. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Does 3-D Secure remove my responsibility for chargebacks?
For a business in the USA, state approved conditions, exclusions and evidence duties for any liability treatment. Keep authentication separate from dispute outcomes. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Which RapidCents checkout options support 3-D Secure for US accounts?
For a business in the USA, list validated hosted, embedded and API paths, versions and activation steps; identify unsupported paths. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud Prevention
RapidCents checks more than 180 signals on every payment attempt in under a second — the device, IP…
ExploreA RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via…
ExploreA payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and…
Explore
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



