


Accept payments in store, online, on the road and over the phone
Accept payments anywhere is for businesses in the USA. Evaluate accept payments anywhere for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Businesses selling in two or more places
A counter and a website, or a van and an invoice, where the second channel was added later and never joined the first.
Field and mobile operators
Trades, deliveries and market stalls taking payment away from a fixed counter.
Teams taking payment over the phone
Where an order is agreed on a call and the card is read out rather than presented.
Common challenges
A provider per channel
Each one bills differently, settles on its own schedule and reports in its own format. The differences land on whoever closes the month.
Channel pricing nobody compares
A rate agreed for the counter and a separate rate agreed online are rarely reviewed together, and the card mix differs between them anyway.
Customers who move between channels
Someone who buys online and returns in store is one customer and two systems, and the refund is where that becomes obvious.
The RapidCents approach
List where money actually arrives today, including the channels that only run occasionally.
Match each one to an acceptance method rather than to a product: counter, mobile, page, link or keyed.
Consolidate onto one merchant account so the deposit report covers the business rather than a channel.
Set roles and permissions once, so a refund limit means the same thing everywhere.
Reconcile the first cross-channel period before any of the old routes are retired.
Recommended capabilities
Terminals and Tap to Pay
Countertop, mobile and smart terminals for fixed lanes, and contactless acceptance on a compatible phone where carrying a device is not practical.
Hosted checkout and payment links
A hosted page for a site with a catalogue, and a pay-by-link URL sent by email or SMS for everything else.
Virtual Terminal
A card keyed into a browser for phone and back-office orders, with address verification and the approval or decline reason on screen.
One dashboard across channels
Every channel searchable in one place by last four digits, amount or reference, with deposits and disputes alongside.
Channel breakdown in reporting
In-person, online and keyed totals separated in the same export, which is what makes per-channel cost visible at all.
Related products
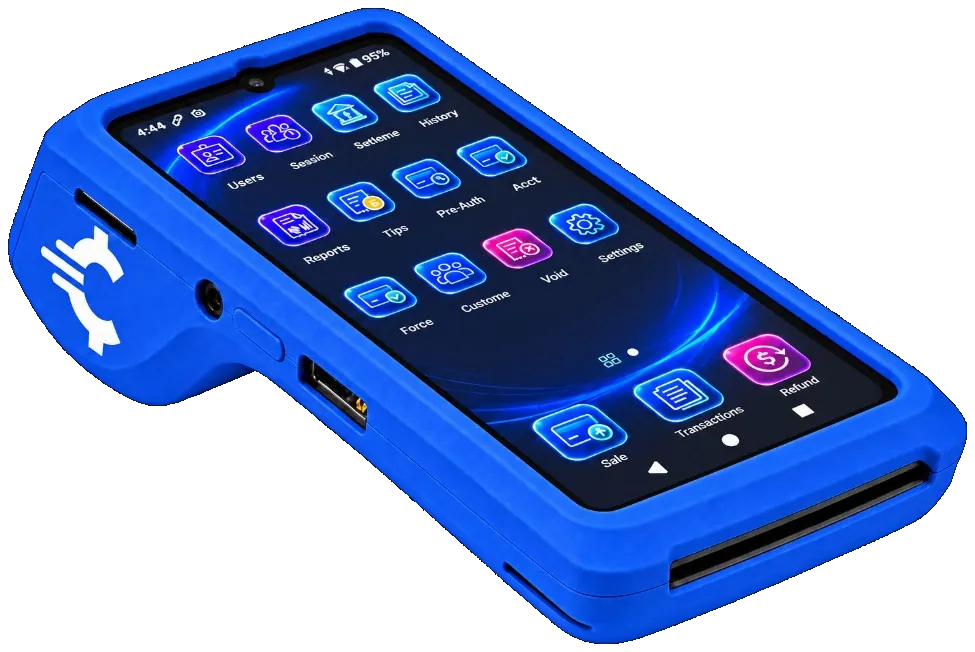
The RapidCents Rivo Go on a counter, the flagship of the Rivo line of countertop, mobile and compact card terminals. Payment Terminals
RapidCents payment terminals cover countertop, mobile and smart form factors so you can accept chip…
Explore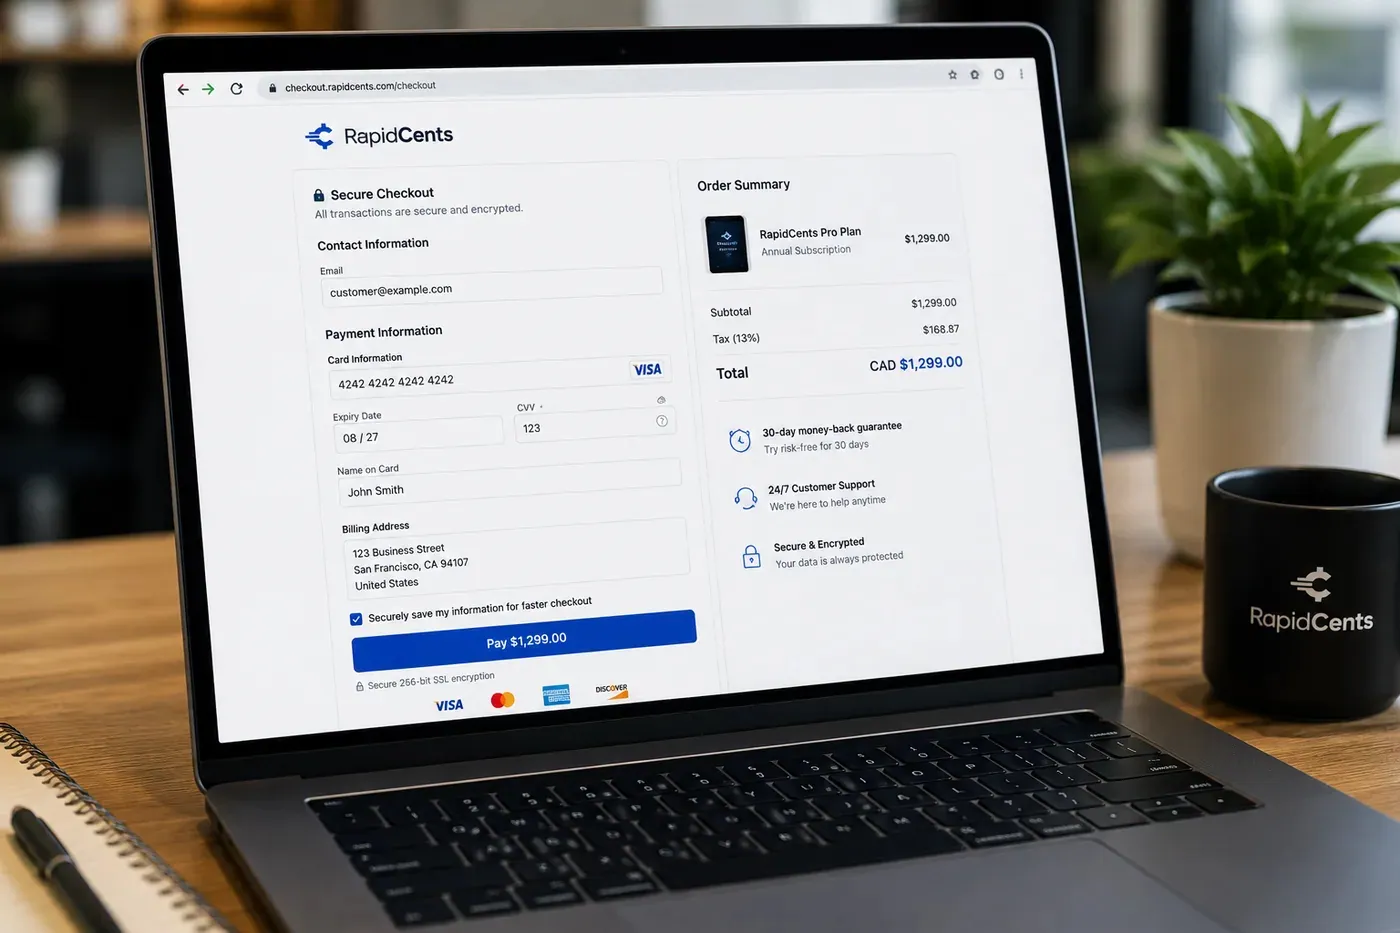
A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via iframe…
Explore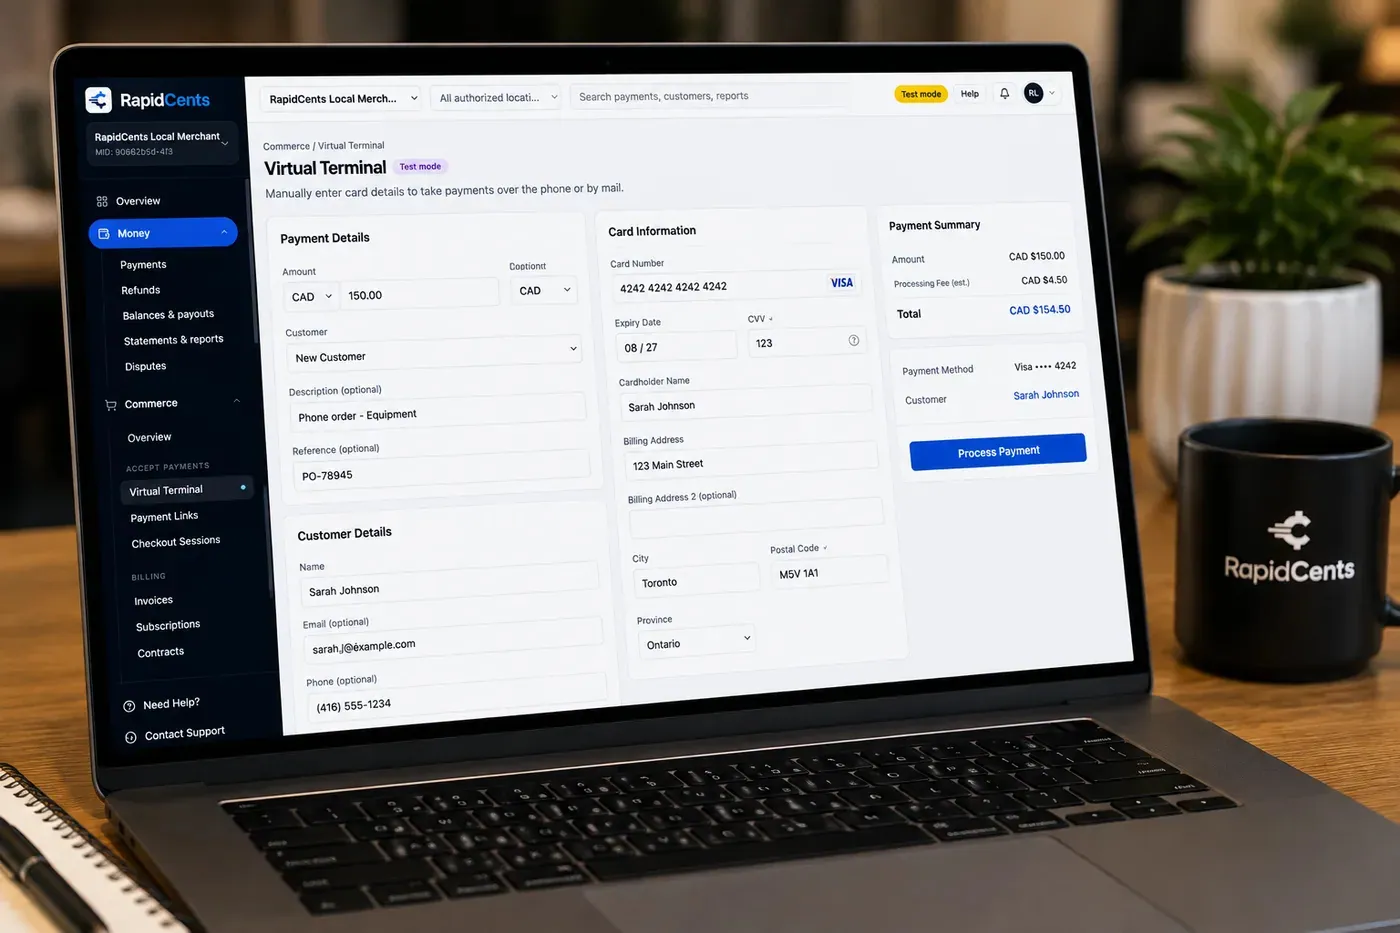
The RapidCents virtual terminal: payment details, card number, expiry and CVV keyed by hand on the left, with a payment summary on the right showing the amount, the estimated processing fee and a Process Payment button. Virtual Terminal
The RapidCents virtual terminal lets authorized staff enter mail-order and telephone-order payments through…
Explore


Implementation approach
Discovery
Map every route money currently takes, including the seasonal or occasional ones people forget to mention.
Configuration
Devices, checkout, links and keyed access set up under one account, with staff roles applied consistently.
Parallel testing
Each channel tested end to end — sale, refund, settlement — while existing routes still run.
Phased go-live
Channels moved one at a time, each confirmed against a deposit before the next begins.
What does not change
How your customers pay
Tap, chip, wallet, link or over the phone: the methods stay. What changes is where they report.
Your seasonal channels
A channel used twice a year does not need its own provider. It can sit dormant on the same account and be used when the season arrives.
Your existing devices, where they fit
Consolidating does not automatically mean replacing every terminal. Compatibility is checked before anything is ordered.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Map a U.S. Merchant's counter sale, field visit and remote invoice to the actual supported channel. In practice, who enters the payment details in each case. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments anywhere does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers shared customer or order references needed to reconcile channels. Do not imply every card, device or merchant account supports every method. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments anywhere does not, by itself, prove delivery or win a dispute.
What to confirm
In practice, the account configuration, equipment and staff training required before adding a channel. State confirmed U.S. Settlement arrangements separately from the channel choice. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments anywhere does not, by itself, prove delivery or win a dispute.
Frequently asked questions
Does one account mean one rate for everything?
No. Interchange differs by how the card is presented, so a tapped card and a keyed card cost differently under any provider. One account means one statement and one deposit report; it does not flatten the underlying cost difference.
Which method should a mobile business use?
Tap to Pay on a compatible phone if the payment is contactless and the volume is occasional. A mobile terminal with LTE if you need PIN debit, printed receipts or all-day reliability.
How do refunds work across channels?
A refund is processed against the original transaction, so an online sale is refunded against the online authorization even if the customer is standing at the counter. The dashboard finds the original by last four digits, amount or reference.
Can two staff take payments at the same time in different places?
Yes. Devices, checkout and keyed access run in parallel under the same account, with permissions set per user rather than per device.
What about a customer who wants to pay by bank transfer?
Bank payments are available for larger or repeating amounts, which suits B2B balances better than card does. It settles on a different rhythm, so it belongs in the reconciliation plan rather than being switched on quietly.
Do all channels settle into the same deposit?
They settle into the same account under one deposit report. Batches close per channel and device, which is exactly why the deposit detail linking each settlement to its batch is the report to work from.
Can my U.S. business use the same payment account in-store and online?
For a business in the USA, in practice, the approved account structure, reporting relationship and any separate agreements or enablement; avoid universal eligibility. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Which equipment do mobile staff need to collect a payment?
For a business in the USA, name supported device models, operating systems, connectivity and receipt options. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How do I match payments from different channels to the same customer?
For a business in the USA, in practice, verified references, customer records and reports, including when manual matching remains necessary. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



