


Cards without card data
Replace stored card numbers with tokens your systems can safely hold
Payment Tokenization is for businesses in the USA. Developer or security buyer understanding how card credentials become references and can be reused; distinguish the mechanism from vault management. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Raw card data never stored
- Reusable for repeat billing
- Reduces PCI scope

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
Subscription businesses
Charge the same customer repeatedly without storing cards.
Software platforms
Keep customer payment methods without holding card data.
Multi-channel merchants
Reuse a saved method online and in person.
Core capabilities
Token creation
Exchange a card entered at checkout, terminal or virtual terminal for a token.
Reuse across channels
Charge the same token online, in person or through the API.
Scope reduction
Your systems store the token, not the card number.
Lifecycle management
Update, replace or delete tokens as customer records change.
Works with recurring billing
Subscriptions and installments charge against the stored token.
How it works
The customer enters a card on a RapidCents-hosted surface.
RapidCents returns a token that maps to that credential.
Your system stores the token against the customer record.
Future charges reference the token instead of the card.
Tokens are updated or removed as the record changes.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with Payment Tokenization
Capabilities on the same account, so the parts below connect without a second integration or a second contract.
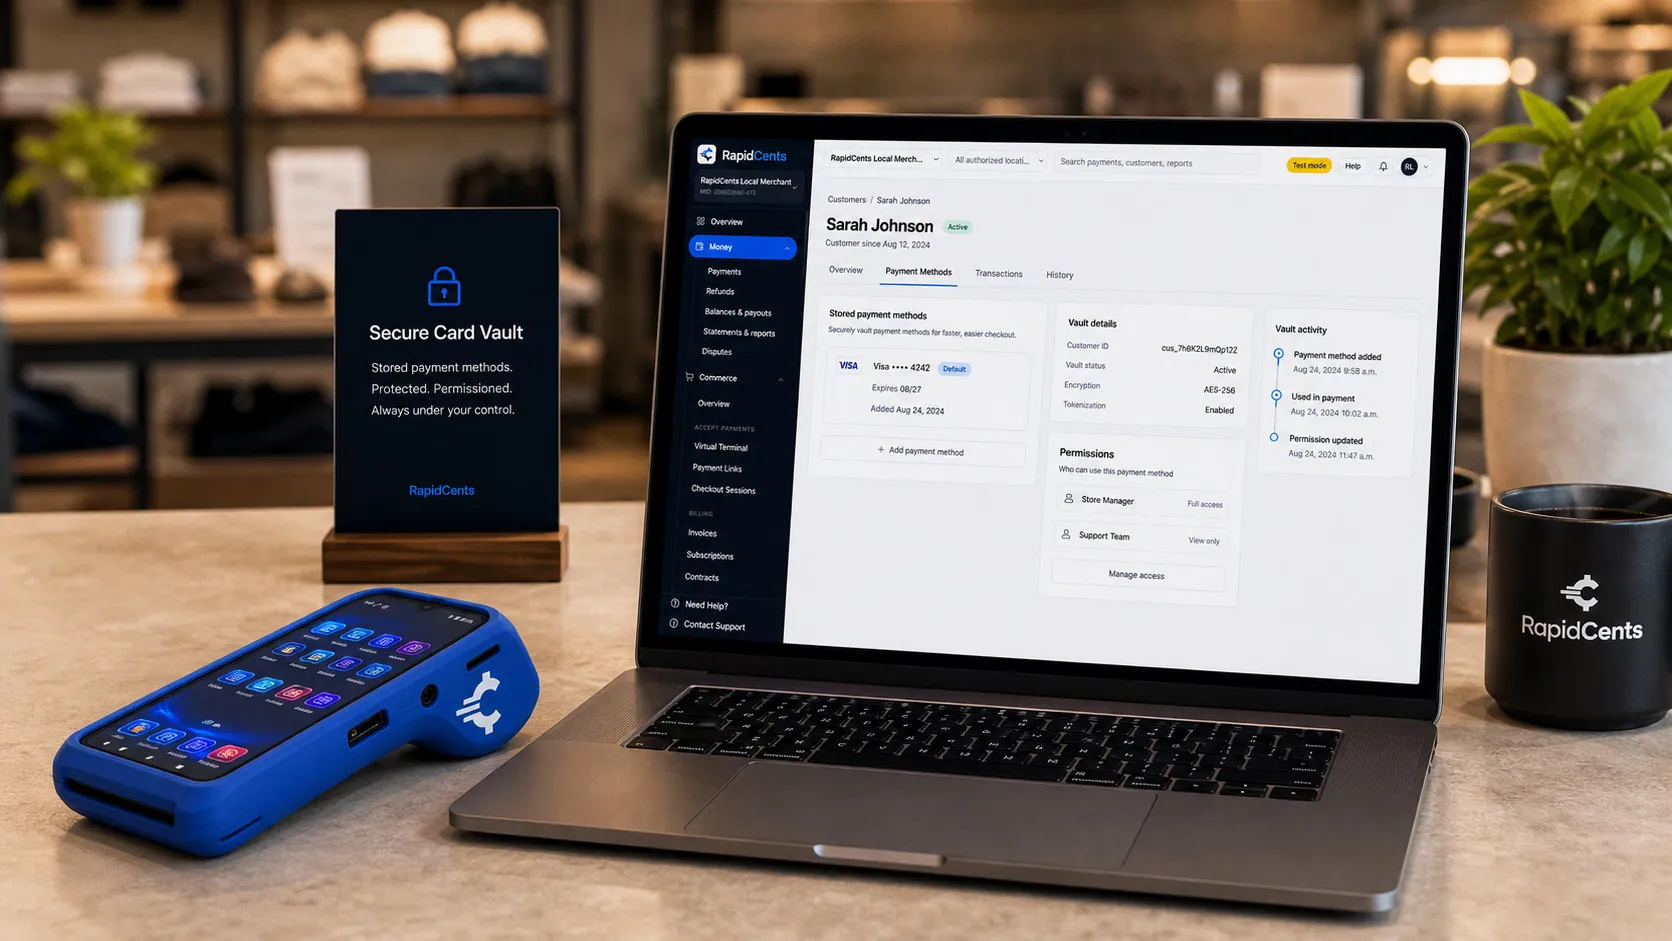
Card credentials sit in the RapidCents vault rather than in merchant software, with a terminal on the desk for new captures. Secure card vault
The PCI-scoped store the tokens point at, so card-on-file stays out of your scope.
Explore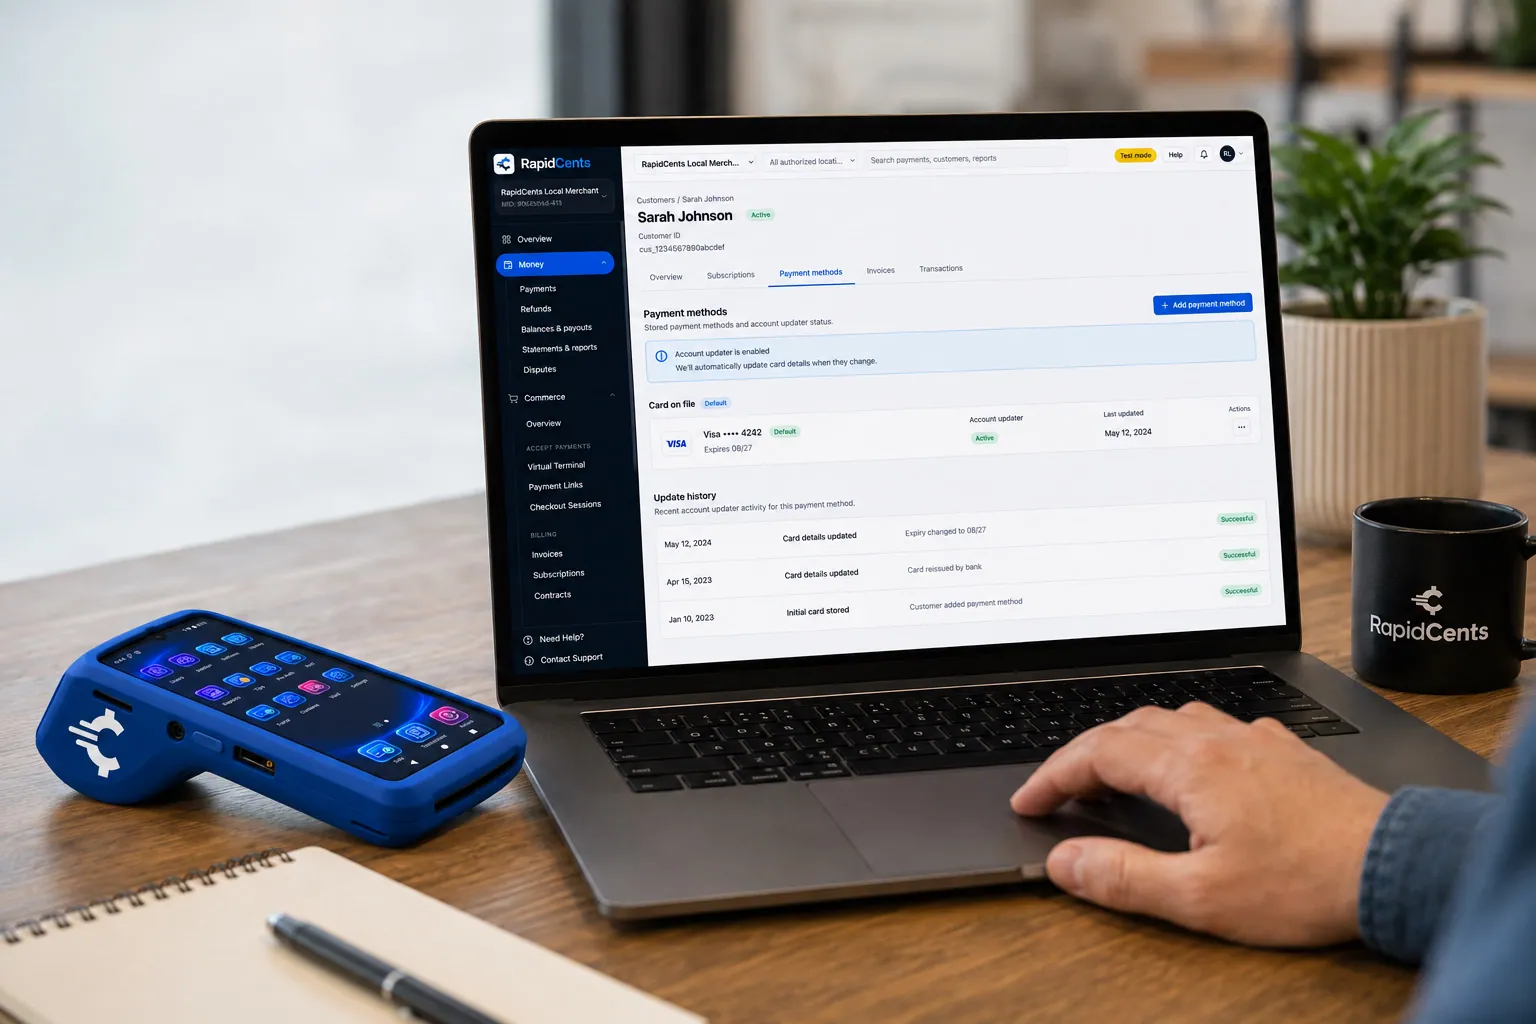
RapidCents refreshes a stored card after a reissue, so the vaulted credential keeps working without asking the customer again. Account Updater
Refreshes stored cards when they expire or get reissued, so repeat billing keeps working.
Explore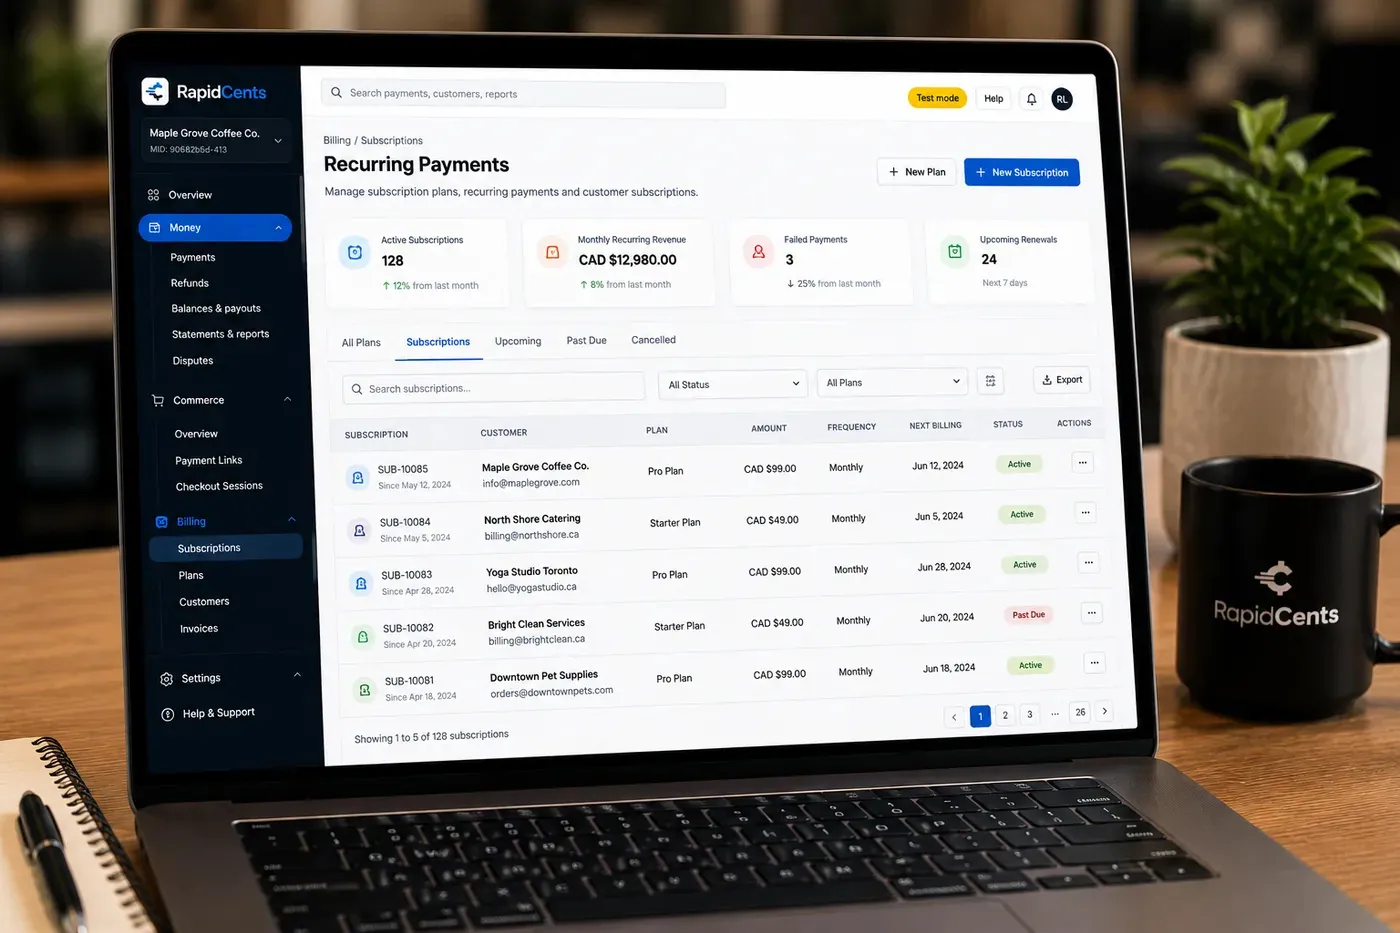
The RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring payments
Schedules, subscriptions and instalments billed from a stored credential.
Explore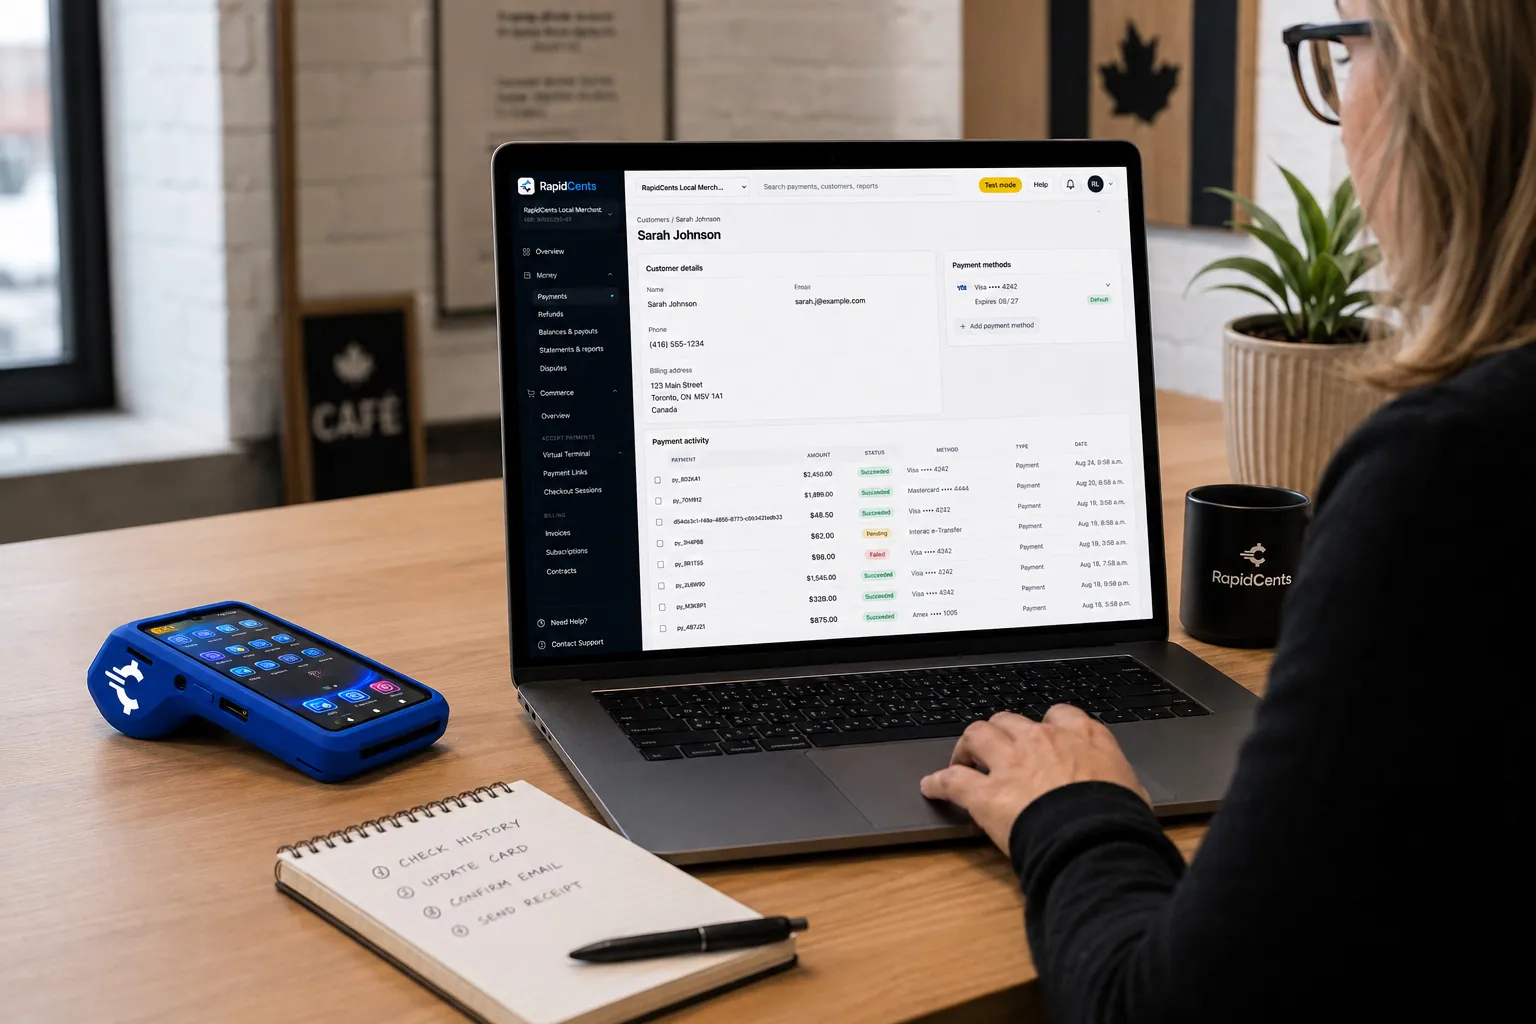
A RapidCents customer profile holds saved cards and invoices, so a return visit can be charged without re-keying the card. Customer profiles
One customer record holding contact details, stored credentials and payment history.
Explore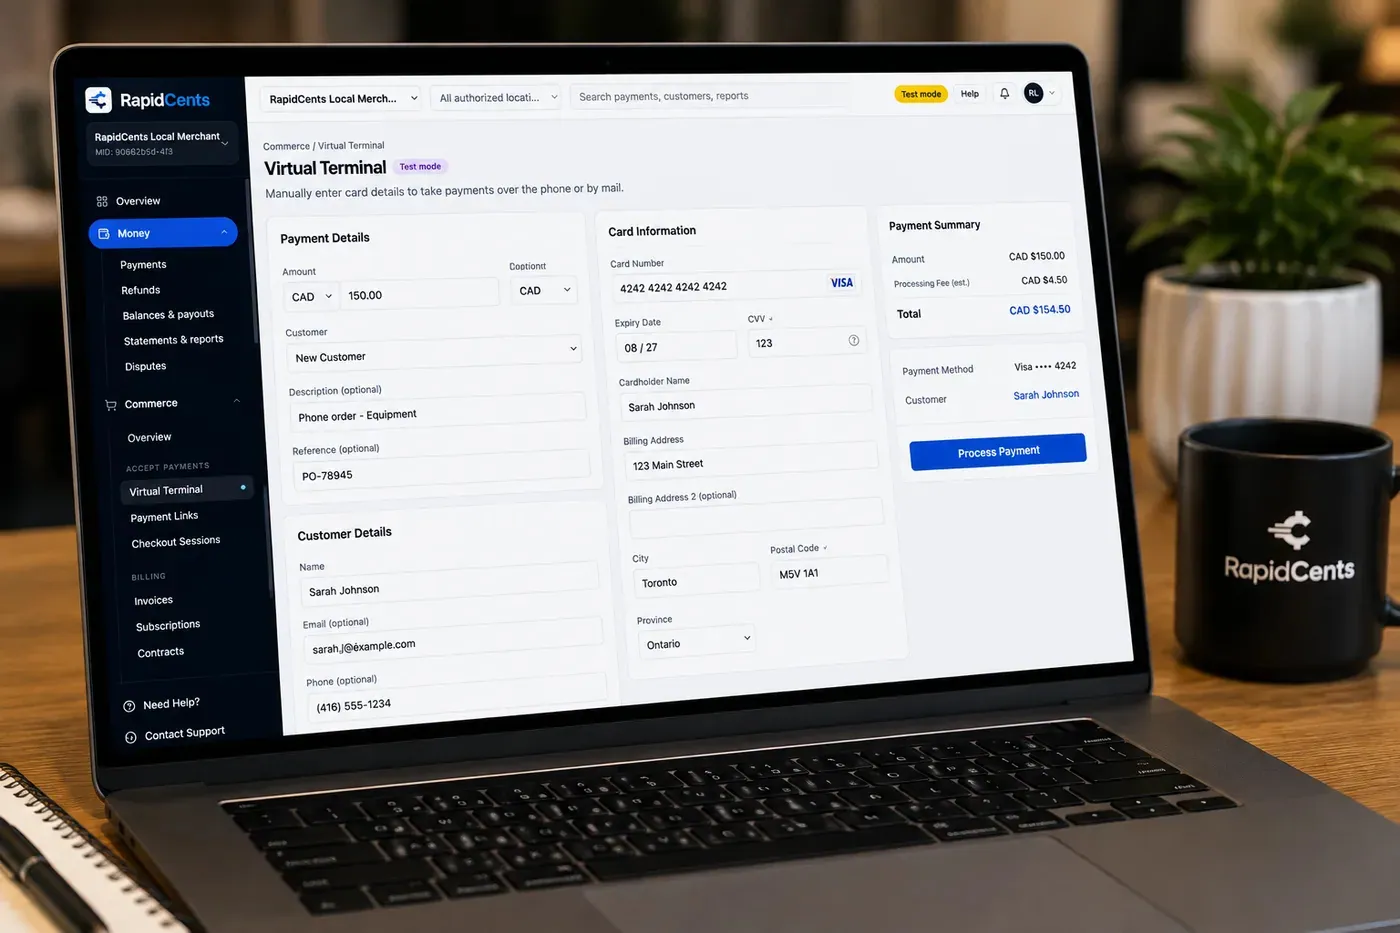
The RapidCents virtual terminal: payment details, card number, expiry and CVV keyed by hand on the left, with a payment summary on the right showing the amount, the estimated processing fee and a Process Payment button. Virtual Terminal
Key a card into a browser for phone, mail and back-office orders.
Explore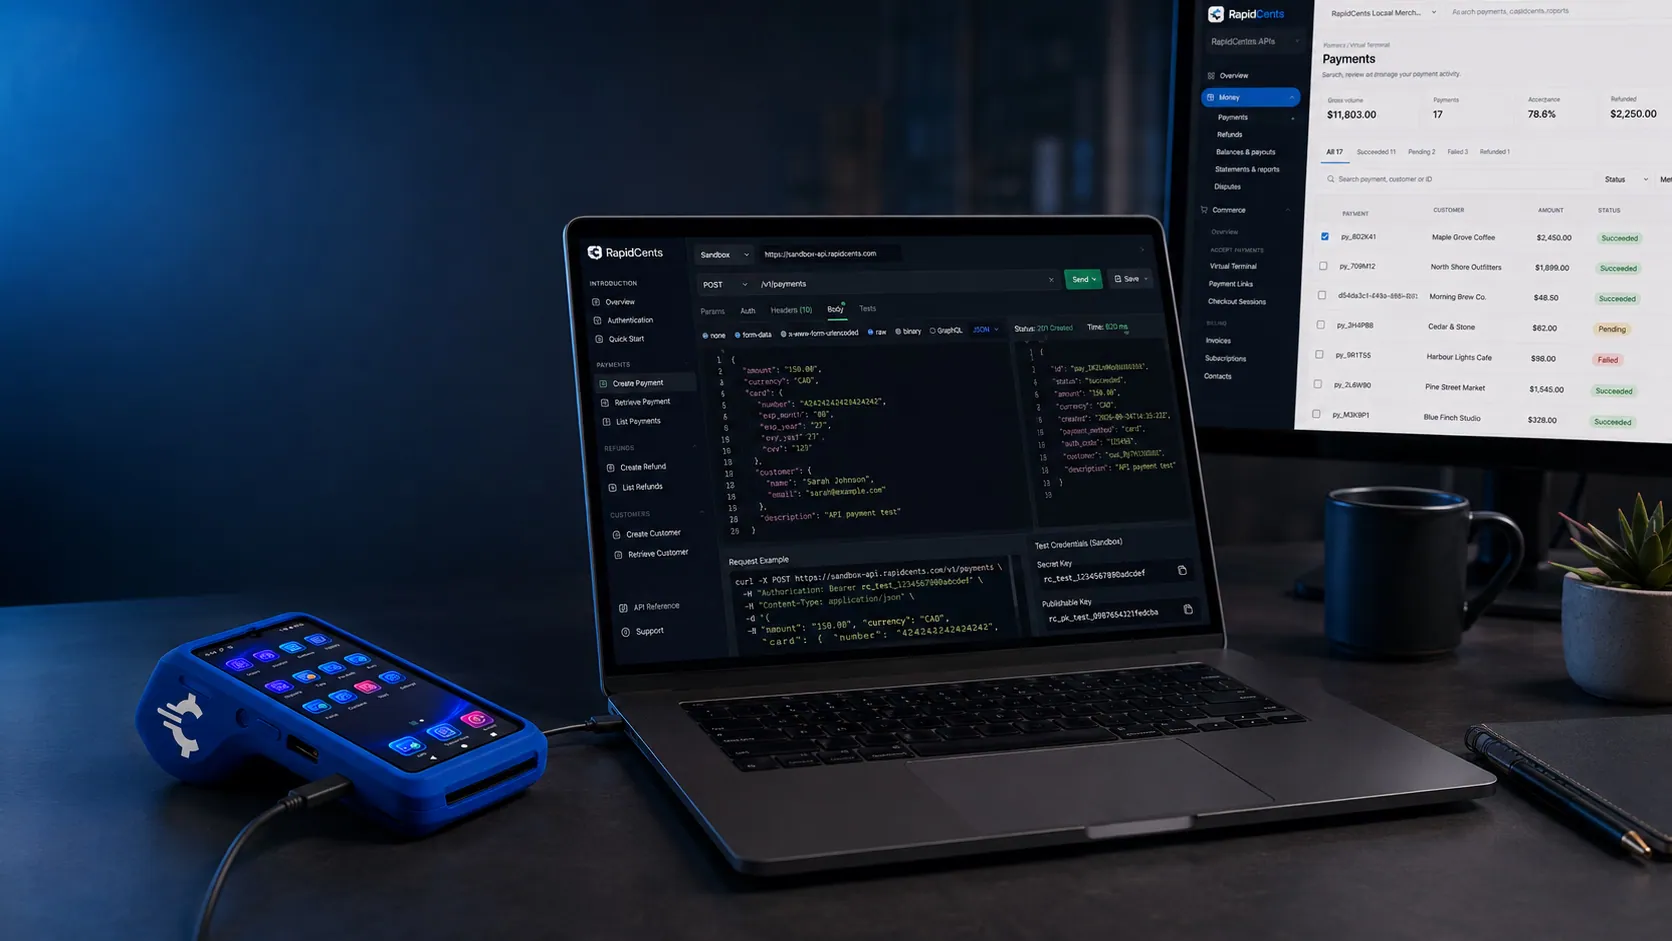
A RapidCents API request and its response on a developer workstation, with the merchant dashboard and a test terminal. RapidCents APIs
REST endpoints for payments, customers, refunds and reporting.
Explore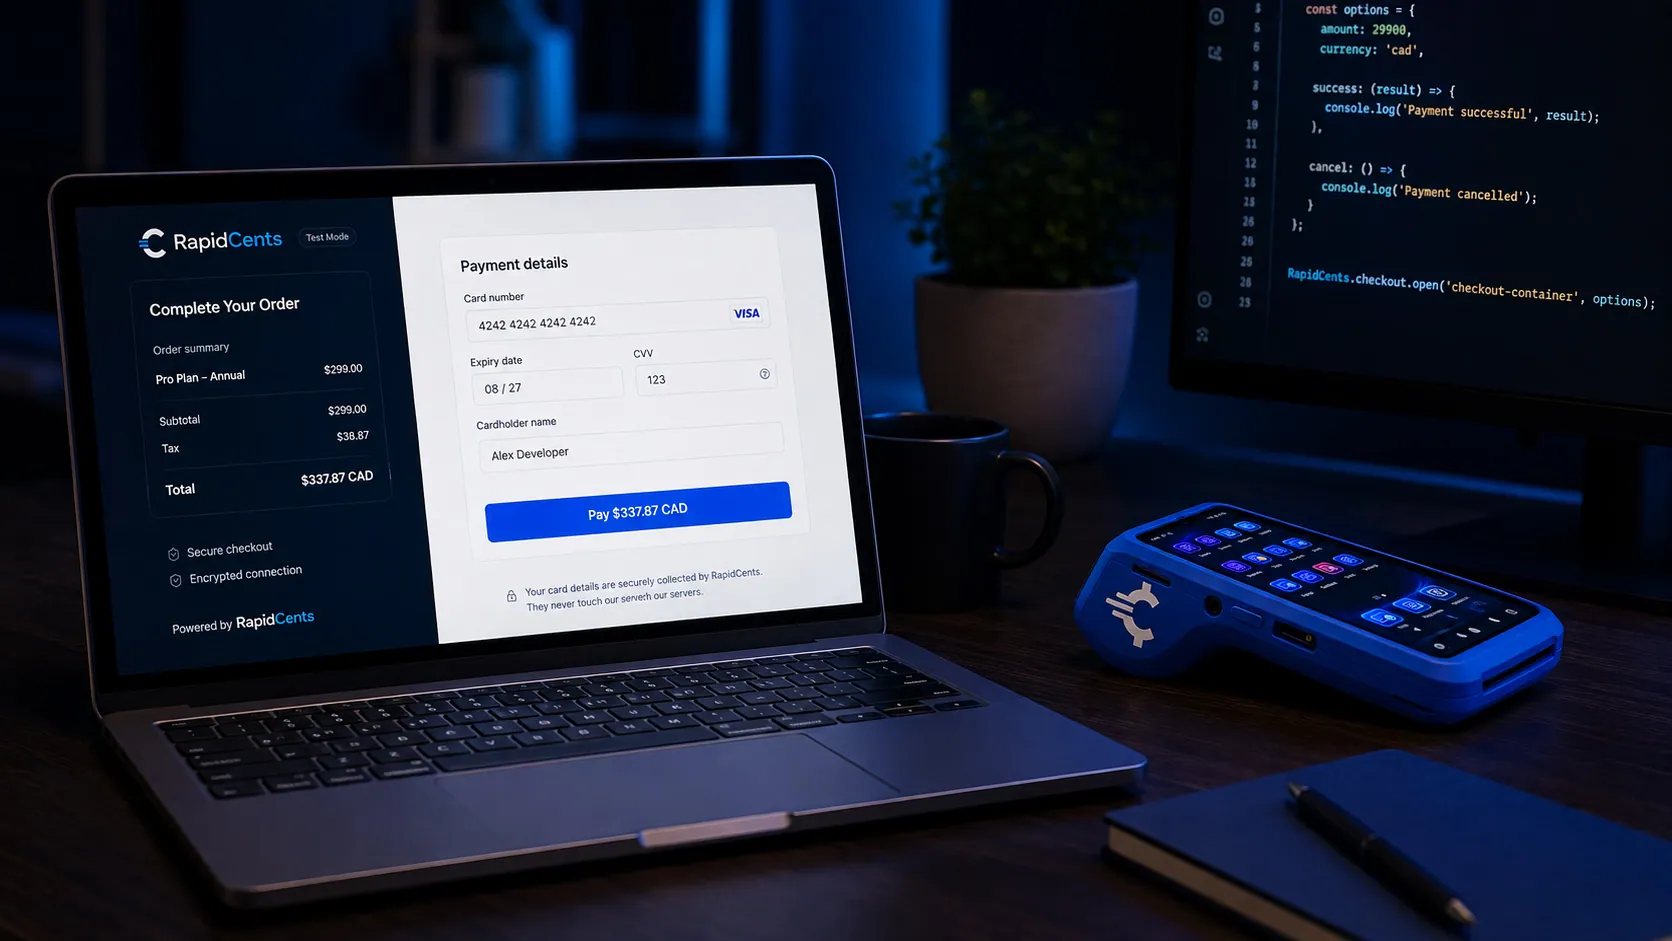
Rapid.js hosted card fields on a developer workstation, keeping card entry out of the merchant's PCI scope. Rapid.js
Embedded card fields that keep your checkout in your own design and out of PCI scope.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Follow a US checkout capturing a credential through an approved flow, receiving a token and associating it with a customer for an authorized later use. In practice, the actual token lifecycle and supported channels. Keep token creation/use distinct from the Secure Card Vault page’s operational storage and access controls. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Payment Tokenization does not, by itself, prove delivery or win a dispute.
The problem and the limit
Diagram where raw credentials and token references reside and which systems can access each. Clarify scope, revocation and migration limitations. The workflow should require security approval for claims that tokens are unusable elsewhere, work across every channel or eliminate PCI obligations; those statements depend on the implementation. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Payment Tokenization does not, by itself, prove delivery or win a dispute.
What to confirm
Before you rely on this, confirm tokenization availability for US accounts, supported entry paths and types of subsequent transactions. In practice, merchant-account boundaries, portability, currency/channel restrictions and fees. Obtain a validated cross-channel example before claiming a terminal-created token can be charged online or through any API. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Payment Tokenization does not, by itself, prove delivery or win a dispute.
Questions about Payment Tokenization
How is a token different from a card number?
A token is a reference that only RapidCents can map back to the credential. On its own it cannot be used elsewhere.
Does tokenization reduce PCI scope?
Yes. Storing tokens instead of card numbers keeps raw credentials out of your systems and narrows what has to be assessed.
What happens when a card expires?
Account Updater can refresh the underlying credential so the token keeps working.
Can I use a token in person and online?
Yes, a stored token can be charged across channels on the same account.
How is tokenization different from the Secure Card Vault?
Tokenization is the mechanism that produces the token. The vault is where tokenized methods are held against a customer record, with the consent that allowed it and the permissions that govern who may charge it.
Can my own software create and charge tokens?
The card has to be entered on a RapidCents-hosted surface, which is what keeps the credential out of your systems. Your software receives the token back and charges it through the API, online or in person, as often as the customer has authorized.
How does tokenization work for a USA merchant?
For a business in the USA, the practical view covers approved capture-to-token sequence and what merchant systems receive and retain. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can one token be used across online, terminal and recurring payments?
For a business in the USA, state confirmed account/channel boundaries and consent requirements; do not infer universal token portability. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What happens to tokens if I migrate providers or remove a saved method?
For a business in the USA, in practice, documented deletion, revocation and approved migration procedures, distinguishing customer records from transferable credentials. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
Card credentials sit in the RapidCents vault rather than in merchant software, with a terminal on the desk for new captures. Secure Card Vault
The vault stores tokenized payment methods against a customer record so staff can charge a…
ExploreRapidCents refreshes a stored card after a reissue, so the vaulted credential keeps working without asking the customer again. Account Updater
Cards expire, get reissued and get replaced after fraud. Account Updater refreshes stored…
ExploreThe RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring Payments
RapidCents recurring payments manage subscription plans, membership renewals and installment…
Explore
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



