


Respond with evidence, on time
Answer disputes with the evidence already in your account
Chargeback Protection is for businesses in the USA. Merchant evaluating evidence preparation and deadline assistance; distinguish the service proposition from the Disputes case-management interface. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Deadline alerts
- Evidence assembled for you
- Win-rate reporting

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
Online sellers
Card-not-present disputes are the most common.
Subscription businesses
Recurring billing attracts recognition disputes.
High-volume merchants
Disputes need a process, not ad-hoc responses.
Core capabilities
Dispute alerts
Know a dispute exists while there is still time to respond.
Evidence packs
Transaction, authorization and delivery detail assembled into a response.
Deadline tracking
See what is due and when across open disputes.
Reason-code guidance
Understand what the issuer is actually asking for.
Outcome reporting
Track win rate by reason code to decide what to contest.
How it works
A dispute is raised and an alert is sent.
RapidCents assembles the transaction evidence.
You review, add context and submit before the deadline.
The outcome is recorded against the dispute.
Win-rate reporting shows which reason codes are worth contesting.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with Chargeback Protection
Capabilities on the same account, so the parts below connect without a second integration or a second contract.
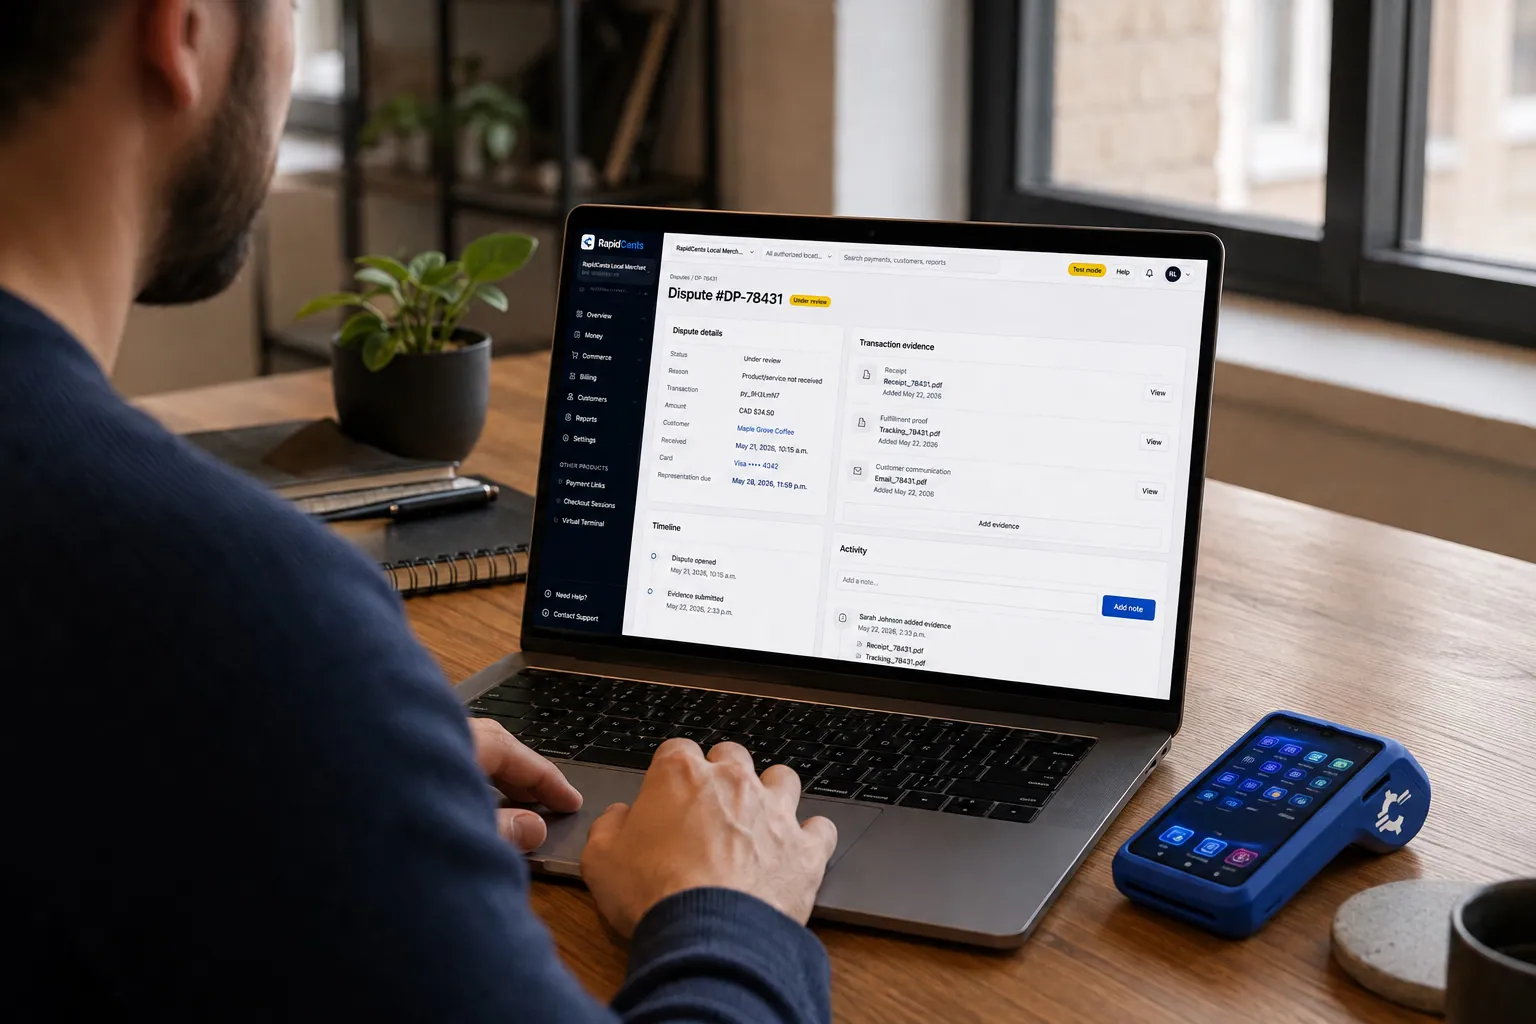
A merchant works a RapidCents dispute case on the dashboard, with the original terminal sale still on the desk. Dispute management
Every chargeback, its deadline and its evidence pack in one queue.
Explore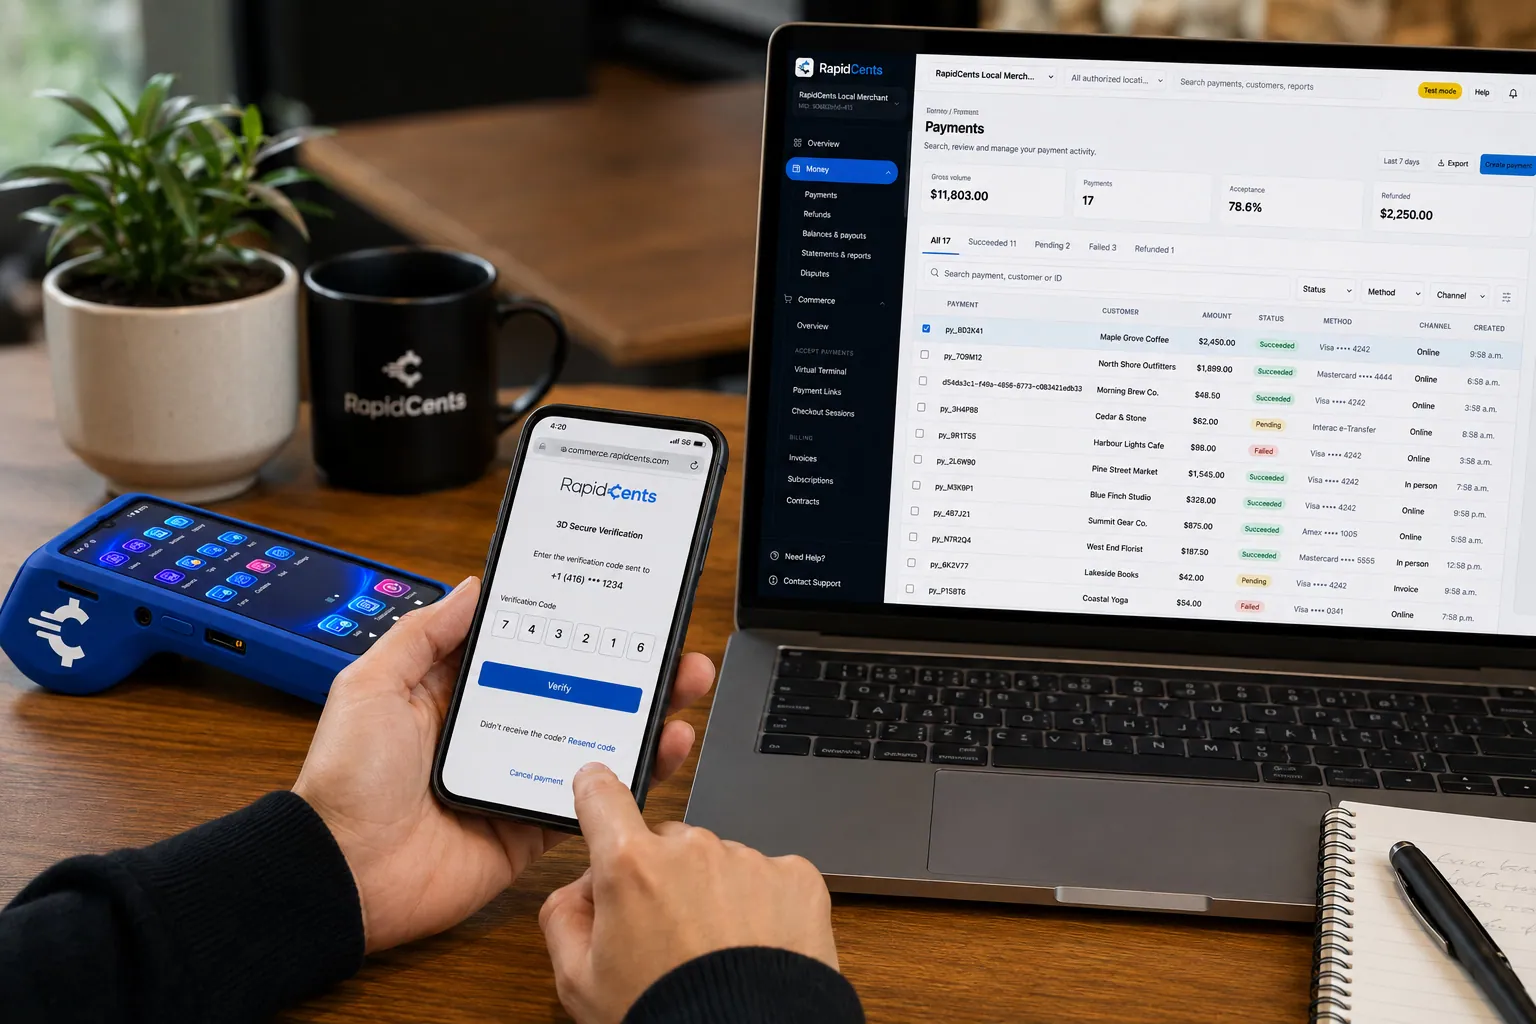
A cardholder completes 3-D Secure on RapidCents checkout, so the issuer can authenticate the online payment. 3-D Secure
Issuer authentication on online payments, which shifts fraud chargeback liability.
Explore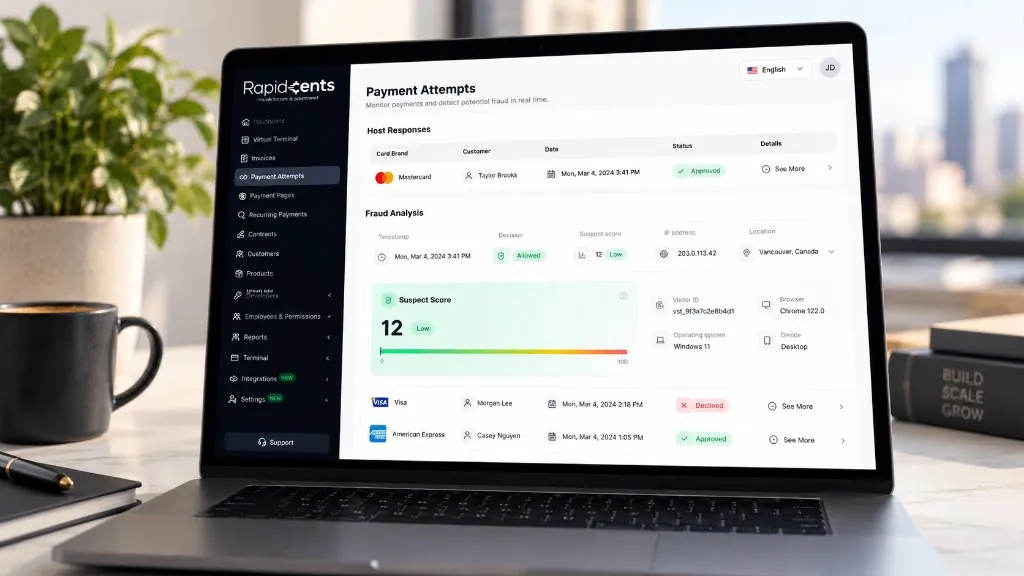
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud prevention
More than 180 signals checked on every payment attempt in under a second, and a fraud score you decide on.
Explore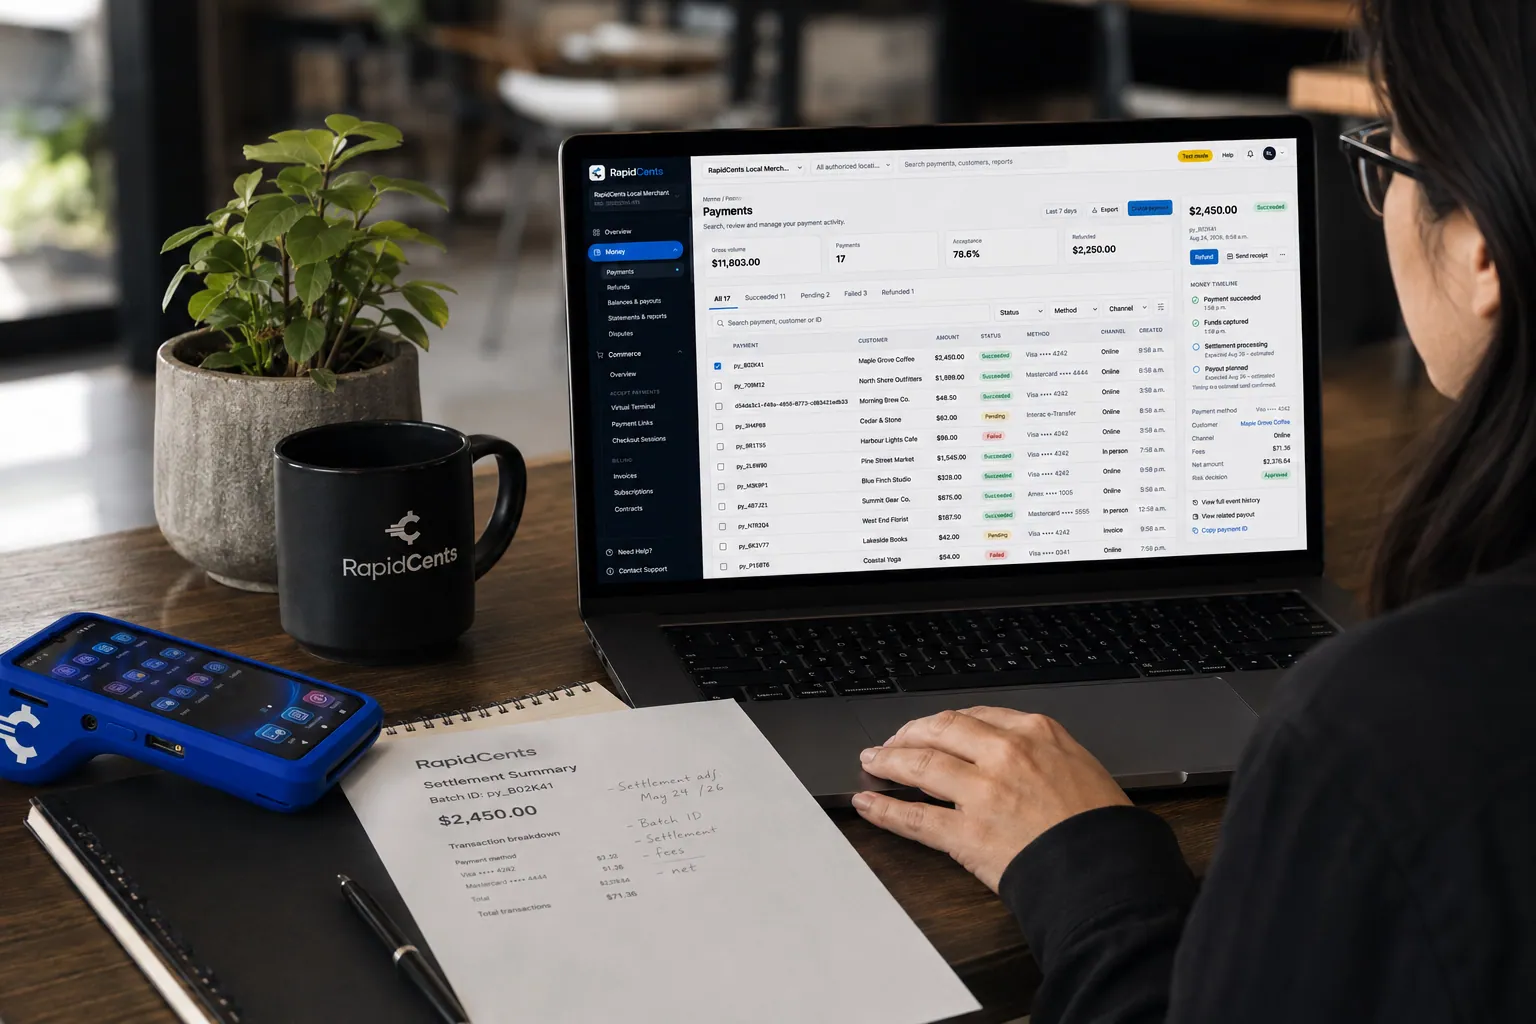
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting and reconciliation
Deposit-level detail that ties settlements back to the transactions behind them.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Show a US merchant receiving a dispute alert and assembling transaction, authorization and available fulfillment records into an evidence package. In practice, the actual assistance provided and who submits the response. Keep this page focused on the evidence-support proposition while linking case status and inbox operations to Disputes. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Chargeback Protection does not, by itself, prove delivery or win a dispute.
The problem and the limit
Define protection precisely: alerts, evidence assembly, managed response or an expressly contracted financial benefit. The workflow should require current documentation for deadlines and exclusions. Do not invent pre-dispute network alerts or imply insurance, reimbursement, guaranteed wins or coverage of every fraud loss merely from the product name. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Chargeback Protection does not, by itself, prove delivery or win a dispute.
What to confirm
Before you rely on this, confirm US processor/network support, eligible channels, enrollment, fees and merchant responsibilities. In practice, approval of refunds or case actions and their USD-reporting effect. Any reimbursement, coverage limit or financial guarantee needs explicit US agreement evidence and legal approval. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Chargeback Protection does not, by itself, prove delivery or win a dispute.
Questions about Chargeback Protection
Can every dispute be won?
No. Some reason codes are rarely winnable, which is why outcome reporting matters: it shows where a response is worth the effort.
How much time do I have?
Deadlines are set by the card networks. Alerts and deadline tracking exist so a response is not missed.
What evidence is included?
Transaction, authorization and available delivery or service detail, plus anything you add.
Does prevention help?
Yes. Fraud Prevention and 3-D Secure reduce how many disputes reach this stage.
How is this different from Fraud Prevention?
Fraud Prevention screens transactions before they settle and so reduces how many disputes ever arrive. Chargeback Protection handles the ones that arrive anyway: the alert, the evidence pack, the deadline and the outcome.
Can I add my own evidence to the pack?
Yes, and it is usually what decides the case. RapidCents assembles the transaction, authorization and available delivery or service detail; you review it, add the context only your business has, and submit before the deadline.
What does chargeback protection include for USA merchants?
For a business in the USA, enumerate contracted service components and exclusions; say explicitly whether any reimbursement exists. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Does RapidCents prepare and submit every dispute response automatically?
For a business in the USA, in practice, the verified evidence, approval and submission workflow; distinguish assembling records from filing a response. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Which transactions and card networks are covered by the service?
For a business in the USA, state validated US scope, activation and fees, and how merchants check an individual case’s eligibility. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud Prevention
RapidCents checks more than 180 signals on every payment attempt in under a second — the device, IP…
ExploreA merchant works a RapidCents dispute case on the dashboard, with the original terminal sale still on the desk. Disputes
RapidCents disputes centralizes chargeback notifications, response deadlines and evidence upload in…
Explore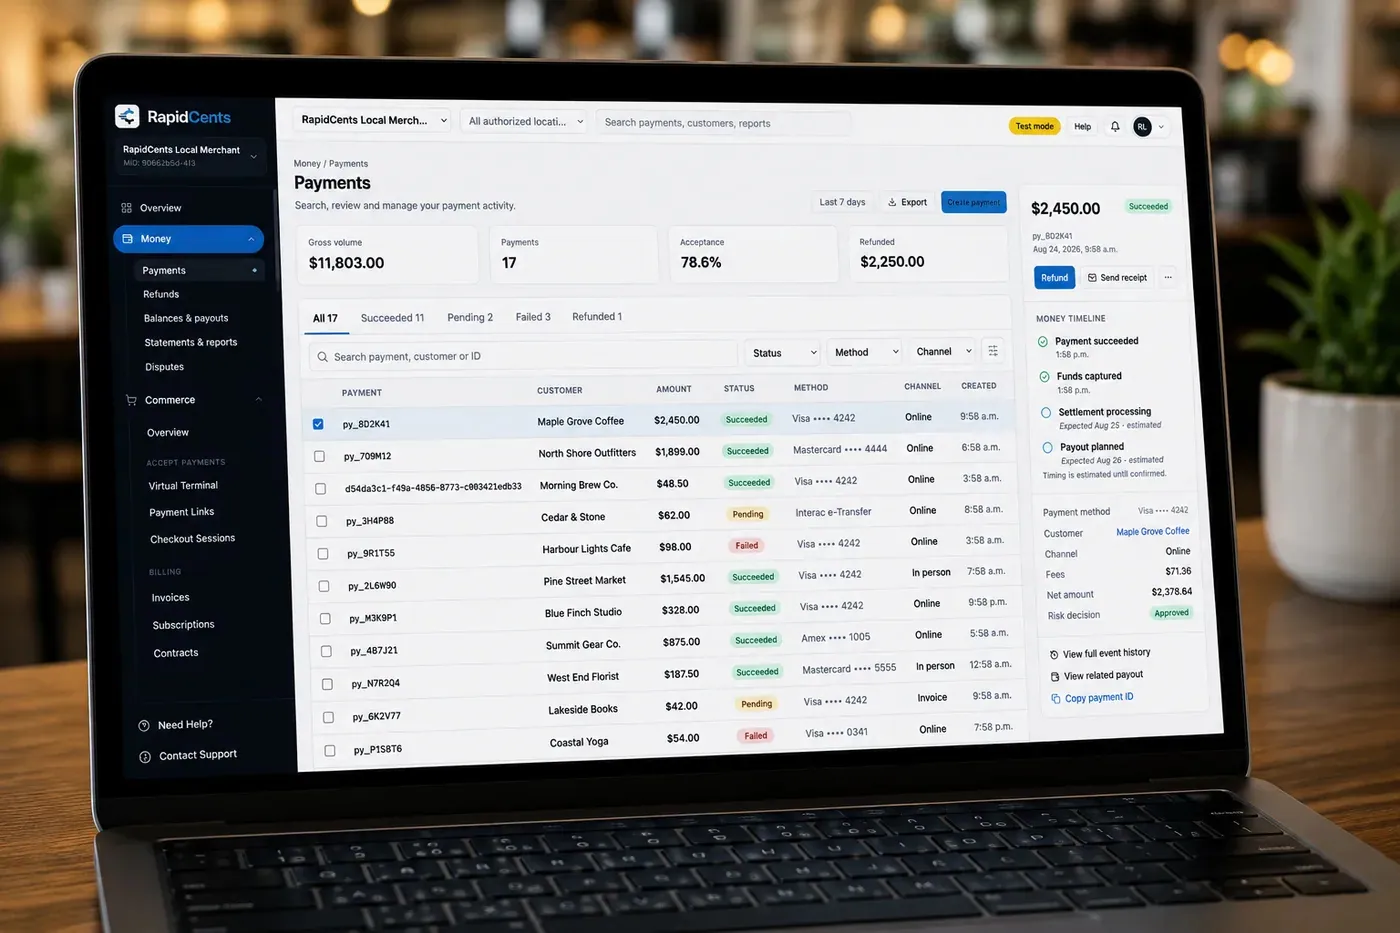
The RapidCents payments screen: gross volume, payment count, acceptance rate and refunds across the top, a filterable transaction list below, and a money timeline on the right tracing one payment from capture to planned payout. Merchant Dashboard
The RapidCents merchant dashboard gives owners, managers and finance staff a single signed-in view…
Explore

Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



