


Unified reporting across every location
Multi-location business is for businesses in the USA. Evaluate multi-location business for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Retail and restaurant chains
Sites that should run and report the same way, but were opened years apart on different equipment.
Franchisors
Head office needs visibility across franchisees without giving each one visibility into the others.
Regional managers
A manager responsible for a territory needs their locations and nothing else, without asking head office to pull a report.
Common challenges
Deposit timing that varies by site
Batches close at different times, so two stores with identical sales land money on different days and the month-end totals disagree.
Everyone sharing one login
Without scoped access, either managers see the whole chain or they see nothing and route every question to head office.
Disputes handled nowhere
A chargeback raised against one location is seen by whoever opens the mail. Deadlines pass at the sites least equipped to notice.
The RapidCents approach
Map the hierarchy you actually operate: head office, regions or brands, then locations.
Assign a MID and terminals to each site so its volume, deposits and disputes are attributable.
Set the batch policy, because a scheduled close at a consistent time removes most deposit-timing variance.
Invite managers with access scoped to their locations, and keep dispute handling where someone is accountable for it.
Review the roll-up on a fixed cadence and drill into a single store when a number looks wrong.
Recommended capabilities
Location hierarchy
Sites organized under regions, brands or franchise groups, with as many tiers as the operation actually has.
Roll-up reporting with drill-down
Consolidated totals for the chain that open down to one store, one terminal and one transaction.
Scoped permissions
A manager sees the locations assigned to them; transactions from other territories are not visible to them.
Centralized disputes
Head office can respond to a chargeback on behalf of a location, with transaction and authorization evidence already assembled.
Terminal inventory
Which device sits at which site, and when it last closed a batch — the fastest way to find the lane that stopped settling.
Related products
One RapidCents account comparing sales across locations, with a terminal representing the store-level capture. Multi-Location
RapidCents multi-location tools organize stores, franchises and regions in a hierarchy with location-level…
Explore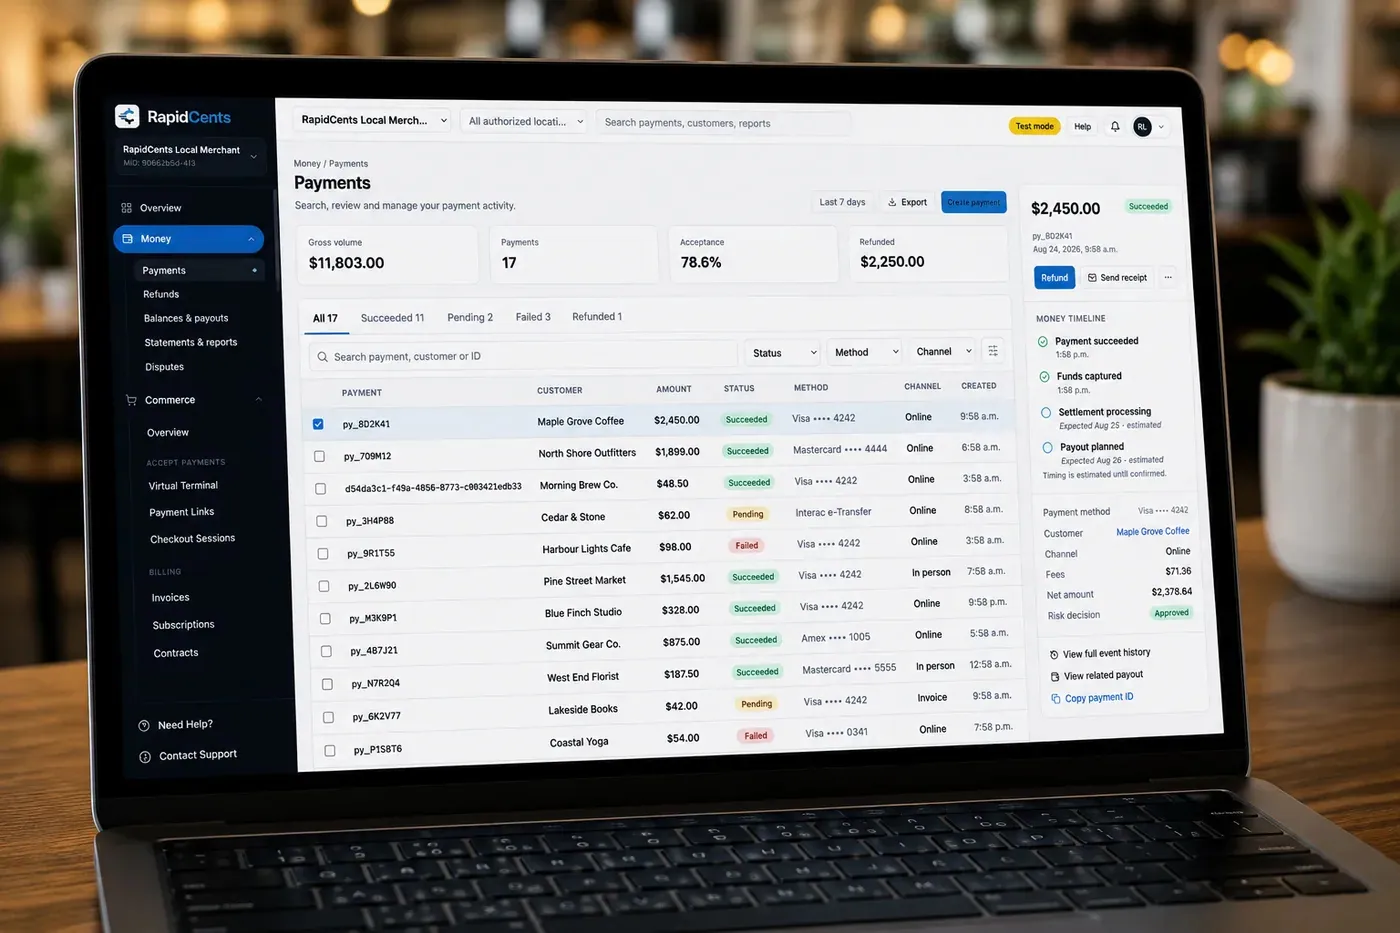
The RapidCents payments screen: gross volume, payment count, acceptance rate and refunds across the top, a filterable transaction list below, and a money timeline on the right tracing one payment from capture to planned payout. Merchant Dashboard
The RapidCents merchant dashboard gives owners, managers and finance staff a single signed-in view of live…
Explore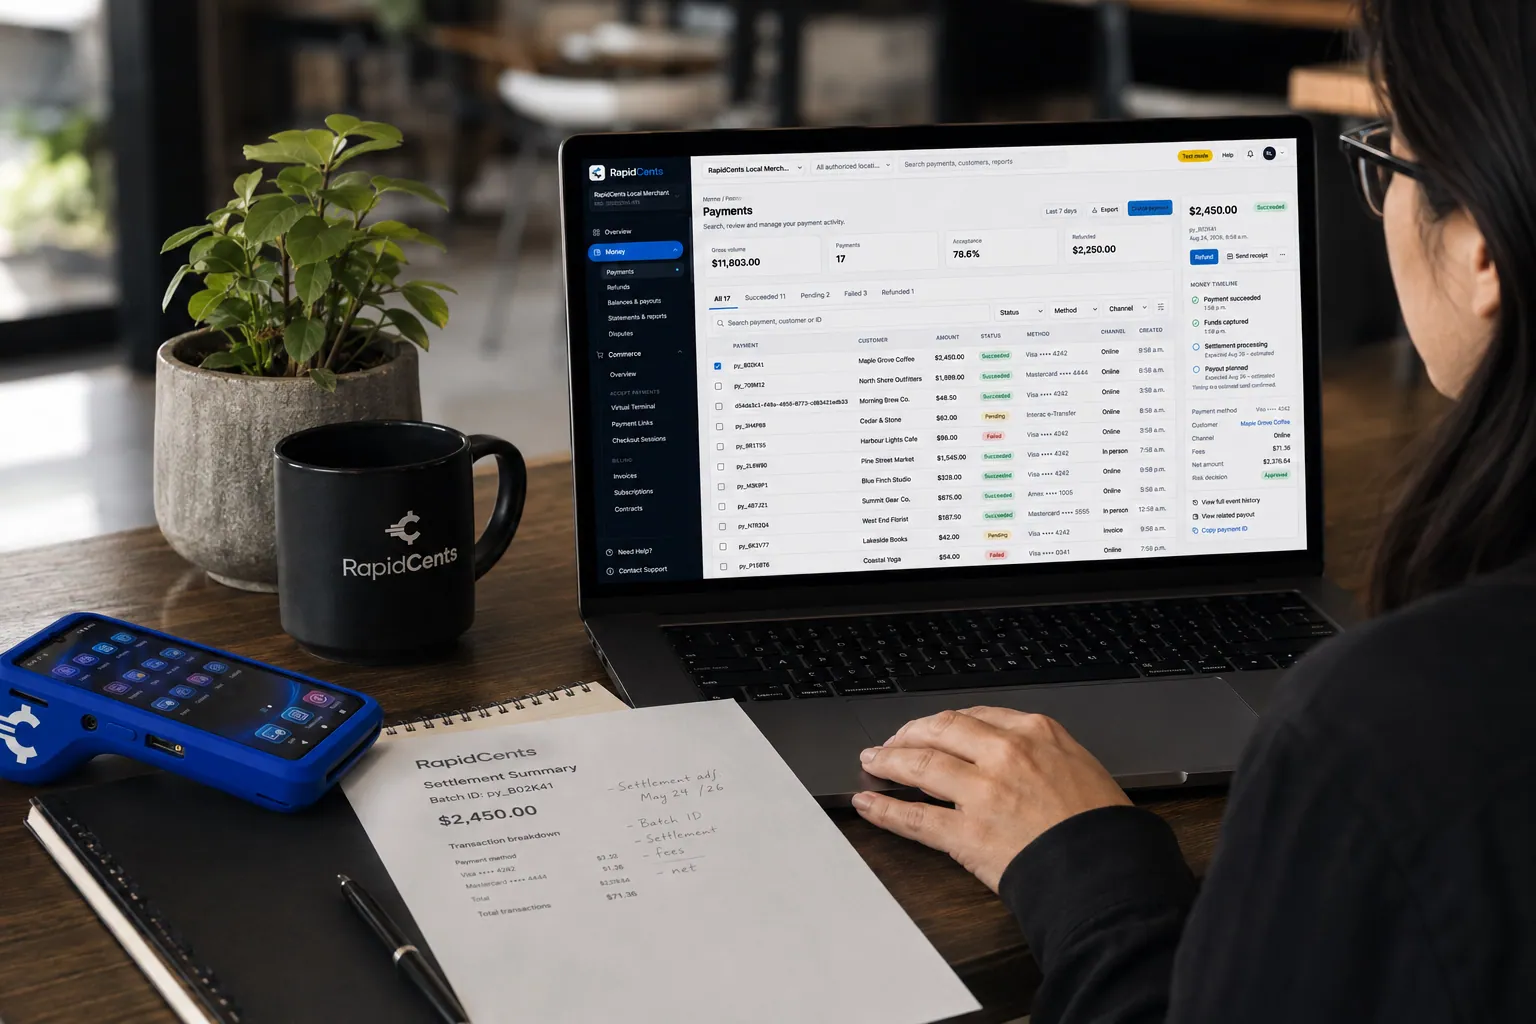
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF export…
Explore


Implementation approach
Hierarchy design
A working session to agree the tree and the permission model before anything is provisioned. Restructuring later is possible but tedious.
Bulk provisioning
Locations and MIDs set up in batch rather than one form at a time, with terminals shipped assigned to the site they belong to.
Manager training
Roll-up reports, scoped search and the dispute queue, taught to the people who will actually open them.
Go-live in waves
Regions phased rather than switched together, so support load stays manageable and each wave learns from the last.
What does not change
Your banking arrangements per site
Each location MID can deposit to its own designated account. Consolidating reporting does not force consolidating banking.
Local menus, catalogues and pricing
Structure standardizes reporting and permissions, not what each site sells or charges.
Franchisee independence
A franchisee can hold a scoped login to their own units. Head office visibility does not require removing theirs.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
A practical view covers U.S. Operator reviewing sales across stores while local staff handle checkout and approved refunds. Distinguish location, merchant ID and legal entity. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Multi-location business does not, by itself, prove delivery or win a dispute.
The problem and the limit
Cover which reports can combine or separate locations and how permissions restrict access. Before you rely on this, confirm time-zone and business-day reporting behavior. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Multi-location business does not, by itself, prove delivery or win a dispute.
What to confirm
Lay out a pilot location, acceptance checks and staged expansion. Clarify that centralized reporting does not automatically mean combined deposits or one contract. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Multi-location business does not, by itself, prove delivery or win a dispute.
Frequently asked questions
How many locations before this is worth doing?
Hierarchy features typically activate at three or more sites. Two locations can usually be run as two accounts; at three, the reconciliation and permission problems start costing more than the setup does.
Can regions carry different pricing?
Pricing attaches to the merchant account, so location MIDs can carry different rates where card mix or volume genuinely differs. It is worth asking why they differ before accepting that they should.
What if one location runs a different POS?
Mixed estates are common after an acquisition. Certified connectors and RapidBridge cover most of it, and the practical question is which POS versions are certified — confirmed per site by an integration specialist.
Who should respond to a chargeback, the store or head office?
Either, and the choice matters more than the tooling. Head office responds faster and more consistently; the store holds the delivery and service detail. Centralized handling with a way to request evidence from the site is the usual compromise.
Can we open a new store without redoing the setup?
A new site is provisioned from an existing configuration, with terminals shipped assigned to it. The configuration work is the hierarchy and the permission model, done once.
What does head office see that a store manager does not?
Cross-location comparison, deposit timing variance between sites, and the whole dispute queue. A store manager sees their own location in the same detail, which is usually more useful to them than the chain view.
Can head office see every location while limiting local staff access?
For a business in the USA, the practical view covers actual role and location controls with a demonstration. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Do all locations receive one bank deposit?
For a business in the USA, in practice, the agreed settlement and merchant-account structure; avoid assuming consolidation. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should we compare daily totals across U.S. time zones?
For a business in the USA, state the configured report date, cutoff and time-zone behavior and how finance should reconcile it. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



