


Sell online with checkout that fits how you actually sell
Selling online starts with the surface, not the technology. RapidCents offers hosted checkout for a catalogue, a payment page for a few products, a link for a one-off quote or booking deposit, and invoices that carry their own payment page. Settlement is in USD, and online orders report beside counter sales on the same account.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Businesses with a small product range
A few items, sold repeatedly. A page or a link does the job a full storefront would do badly.
Businesses with a catalogue
Where stock, variants and returns matter, and the online store has to agree with the shop floor.
Quote-and-invoice businesses
Where each sale is negotiated and the payment attaches to a document rather than to a cart.
Common challenges
Building more than the sale needs
A storefront for four products costs more to maintain than it earns, and every extra surface is another thing that can break.
Handling card data you did not need to touch
A checkout built directly against card fields widens the compliance assessment. Hosted pages and embedded fields avoid that without giving up the design.
Online and in-store treated as separate businesses
Separate stock counts and separate reporting produce two versions of the truth, and the return of an online order at the counter is where they collide.
The RapidCents approach
Decide what you are actually selling online: a catalogue, a few products, a service, or a deposit against work.
Pick the surface to match — hosted checkout, a payment page, a link, or an invoice carrying its own payment page.
Decide where the card is entered, because that sets both the build effort and the compliance scope.
Connect it to reporting so online sits beside in-store rather than in a separate system.
Test the whole loop — sale, receipt, refund, deposit — before it is public.
Recommended capabilities
Hosted checkout
A RapidCents-hosted page with your logo and accent colour, wallet buttons on supported browsers, and session expiry on abandoned carts.
Payment pages and links
A page or a URL for a small range or a single sale, with partial amounts, custom references and deactivation once paid.
Gateway API
For teams building their own checkout: authorize and capture separately, customer tokens, idempotency keys and signed webhooks.
3-D Secure by rule
Authentication triggered by amount, geography or risk signal rather than applied to every sale, so the friction is spent where the liability shift is worth it.
Reporting beside in-store
Online orders report alongside counter sales in the same dashboard, so the two are one business in the numbers.
Related products

A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via iframe…
Explore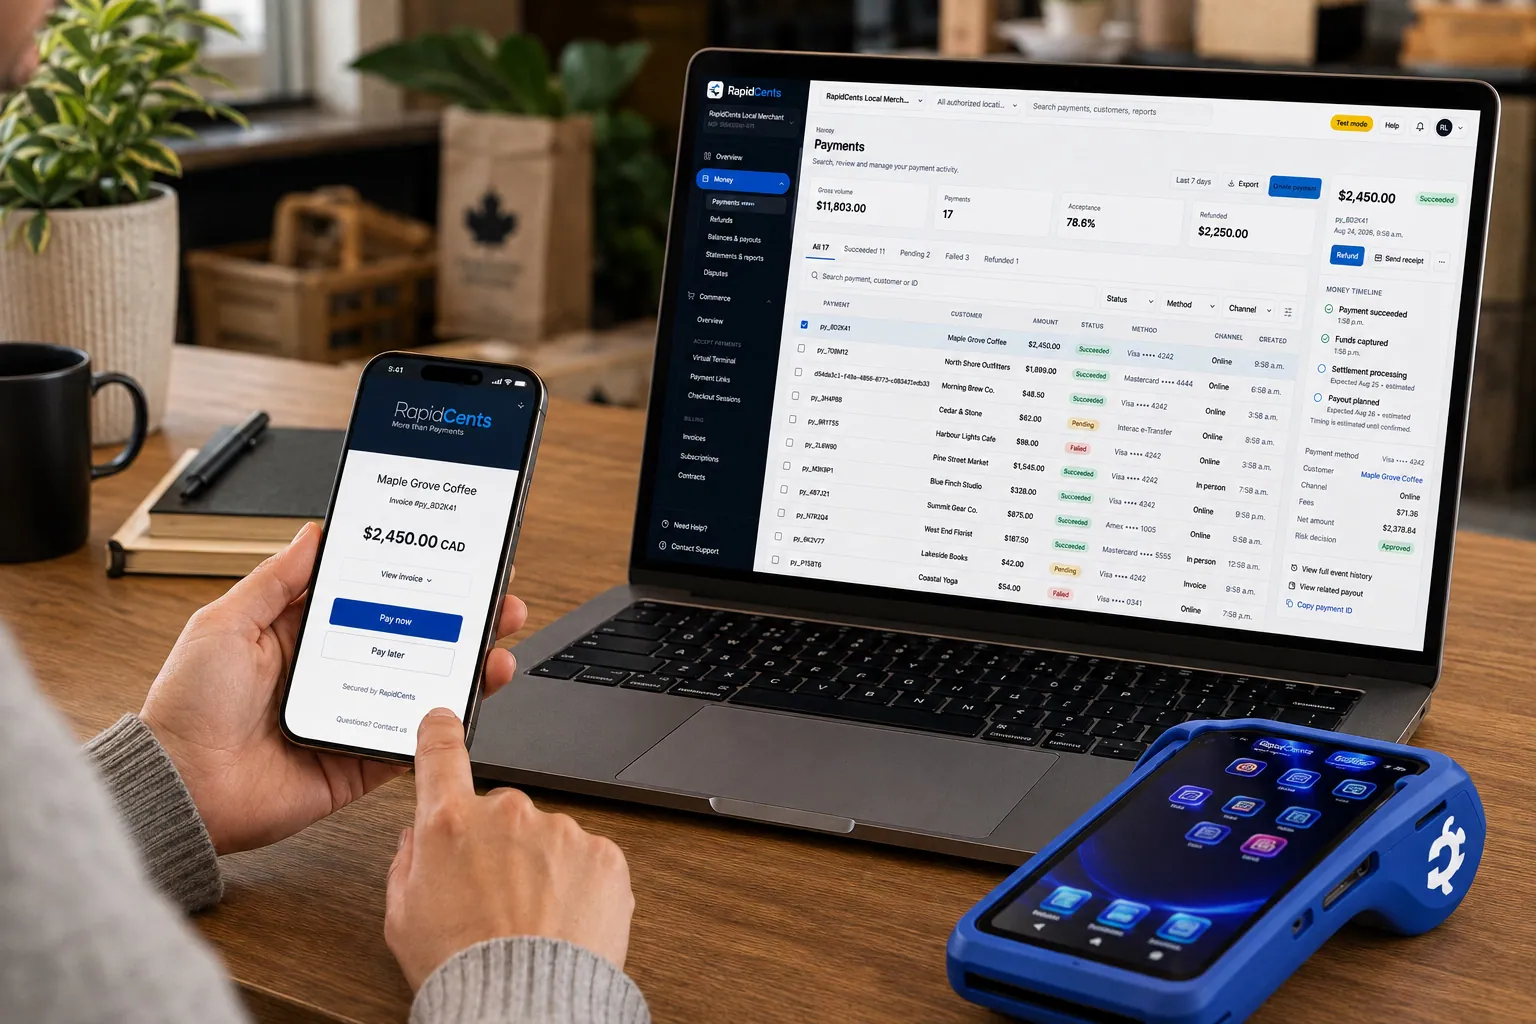
A branded RapidCents payment page open on laptop and phone, ready to collect a card or wallet payment. Payment Pages
Publish a secure, branded page that collects a payment for a product, service, deposit or event.
Explore
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and tokenize…
Explore


Implementation approach
Choose the surface
Match the sale to the smallest thing that handles it properly. This is the decision that saves the most work later.
Configure and brand
Logo, accent colour, receipt content and return URLs set before anything is public.
Test the loop
A sale, a refund and a settlement checked end to end, including what the customer receives by email.
Launch and watch
Live for a period with monitoring on declines and settlement, before any previous route is retired.
What does not change
Your website
A hosted checkout is a step in the flow, not a replacement for your site. Customers return to your pages after paying.
Your in-store operation
Selling online does not change the counter. The same account and the same reporting cover both.
What you sell and how you price it
The surface is a way to collect payment. It does not impose a catalogue structure, a subscription model or a pricing scheme.
Cards, currencies and settlement in the United States
What a RapidCents account in the United States accepts, the currency it settles in, and when the money arrives.
Cards and methods accepted
Visa, Mastercard, American Express, Discover, UnionPay and Diners Club cards from any country, plus PIN debit, Apple Pay, Google Pay and ACH bank payments, on one merchant account.
137+ currencies, settled in USD
Accept 137+ currencies from customers worldwide and receive every payout in USD, deposited directly into your US bank account.
Next-business-day funding and reconciliation
Batches close nightly and deposits arrive the next business day, based on cut-off times and eligibility, with deposit-level reporting in one RapidCents dashboard.
Frequently asked questions
Do I need a storefront to sell online?
No. A payment page or a link handles a small range or a one-off sale, and an invoice can carry its own payment page. A storefront earns its cost once you have a catalogue, stock and repeat browsing.
What is the difference between a payment page and a payment link?
A page is a durable surface a customer can return to. A link is generated for a specific amount and customer, often expires, and deactivates after payment. Pages suit repeat products; links suit one-off amounts.
How do returns work when the sale was online?
The refund is processed against the original authorization, so the money returns to the card that paid. If the customer brings the item to a store, the refund still references the online transaction, which is why one account across channels matters more than it sounds.
Will wallet buttons work for every customer?
Apple Pay and Google Pay appear on supported browsers and devices. Card entry stays available for everyone else, so wallet support is an addition rather than a requirement.
How do I stop abandoned carts sitting open?
Hosted checkout sessions and payment links expire. That limits how long an open payment surface exists, which is a security position as much as a housekeeping one.
Can I sell in more than one currency?
Accept 137+ currencies across Visa, Mastercard, Amex, Discover, UnionPay, Diners Club, and Interac. Canadian merchants can process both CAD and USD and deposit payouts directly into either their CAD bank account or their USD bank account; US merchants can accept 137+ currencies with direct USD bank settlement.
Can an invoice collect the payment itself?
Yes. An invoice can carry its own payment page, so the customer pays from the document instead of being sent somewhere else. That removes the second step where delay usually sits, and the payment reconciles against the invoice rather than being matched to it later.
Can I take a deposit online and collect the balance later?
Yes. A payment link can be issued for a partial amount, such as a booking deposit or a stage payment against work, with a custom reference for reconciliation; it deactivates once paid. The balance is collected the same way when it falls due.
What should be tested before an online channel goes public?
The whole loop: a sale, the receipt email the customer receives, a refund and the bank deposit it settles into. After launch, the channel runs for a period with declines and settlement monitored, and any earlier route is retired only once that period checks out.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



