


Understand your payment costs before making a change
Lower payment costs is for businesses in the USA. Evaluate lower payment costs for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Operators renewing or renegotiating
A contract approaching renewal is the one moment the markup is genuinely open.
Finance teams asked to cut cost
Processing appears as one line in the ledger and several dozen on the statement. The work is turning the second into the first.
Businesses on a blended rate
A single rate covering every card type conceals which transactions actually cost what.
Common challenges
Effective rate is the only comparable number
Total monthly cost divided by total volume. Two providers quoting different structures cannot be compared any other way, and neither can this month against last.
Card mix moves the number on its own
Premium consumer and commercial cards carry higher interchange. As the customer base shifts, the effective rate rises without a contract term changing.
The cost that is not the rate
Monthly minimums, statement fees, terminal rental, non-compliance charges and batch fees are not part of the rate and are part of the bill.
The RapidCents approach
Upload a recent statement to Fee Check so interchange, markup and effective rate are separated line by line.
Identify which costs are pass-through — interchange and network assessments — and which belong to the provider.
Read the non-rate lines: monthly minimums, statement fees, equipment rental and any compliance charges.
Look at how transactions are presented, because card-present, keyed and e-commerce interchange differ for the same card.
Compare any proposal on effective rate over the same statement period rather than on a headline number.
Recommended capabilities
Fee Check statement breakdown
Upload a processing statement and interchange, markup and effective rate are separated automatically, with no obligation attached to the result.
Interchange-plus pricing where you qualify
Interchange and assessments pass through at cost, with the RapidCents markup stated separately. Amex operates on its own arrangement rather than under interchange-plus.
Fee detail in reporting
Interchange, assessment and processor fee as separate columns in the export, so a statement can be checked rather than trusted.
Channel breakdown
In-person, online and keyed totals separated, which is where a surprising share of the cost difference sits.
Deposit-level detail
Each settlement tied back to the transactions and the deductions behind it.
Related products
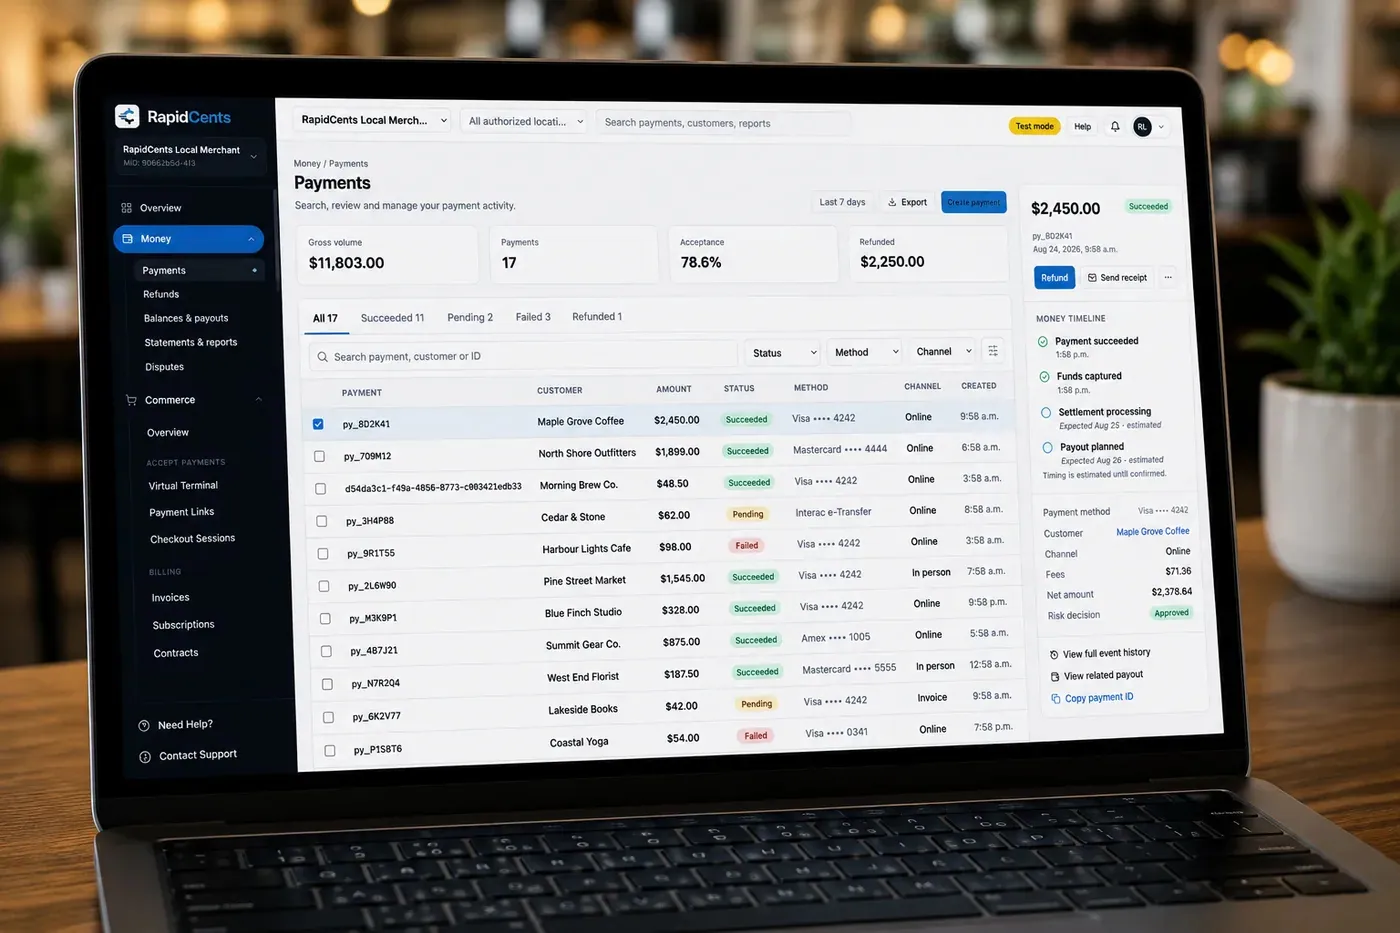
The RapidCents payments screen: gross volume, payment count, acceptance rate and refunds across the top, a filterable transaction list below, and a money timeline on the right tracing one payment from capture to planned payout. Merchant Dashboard
The RapidCents merchant dashboard gives owners, managers and finance staff a single signed-in view of live…
Explore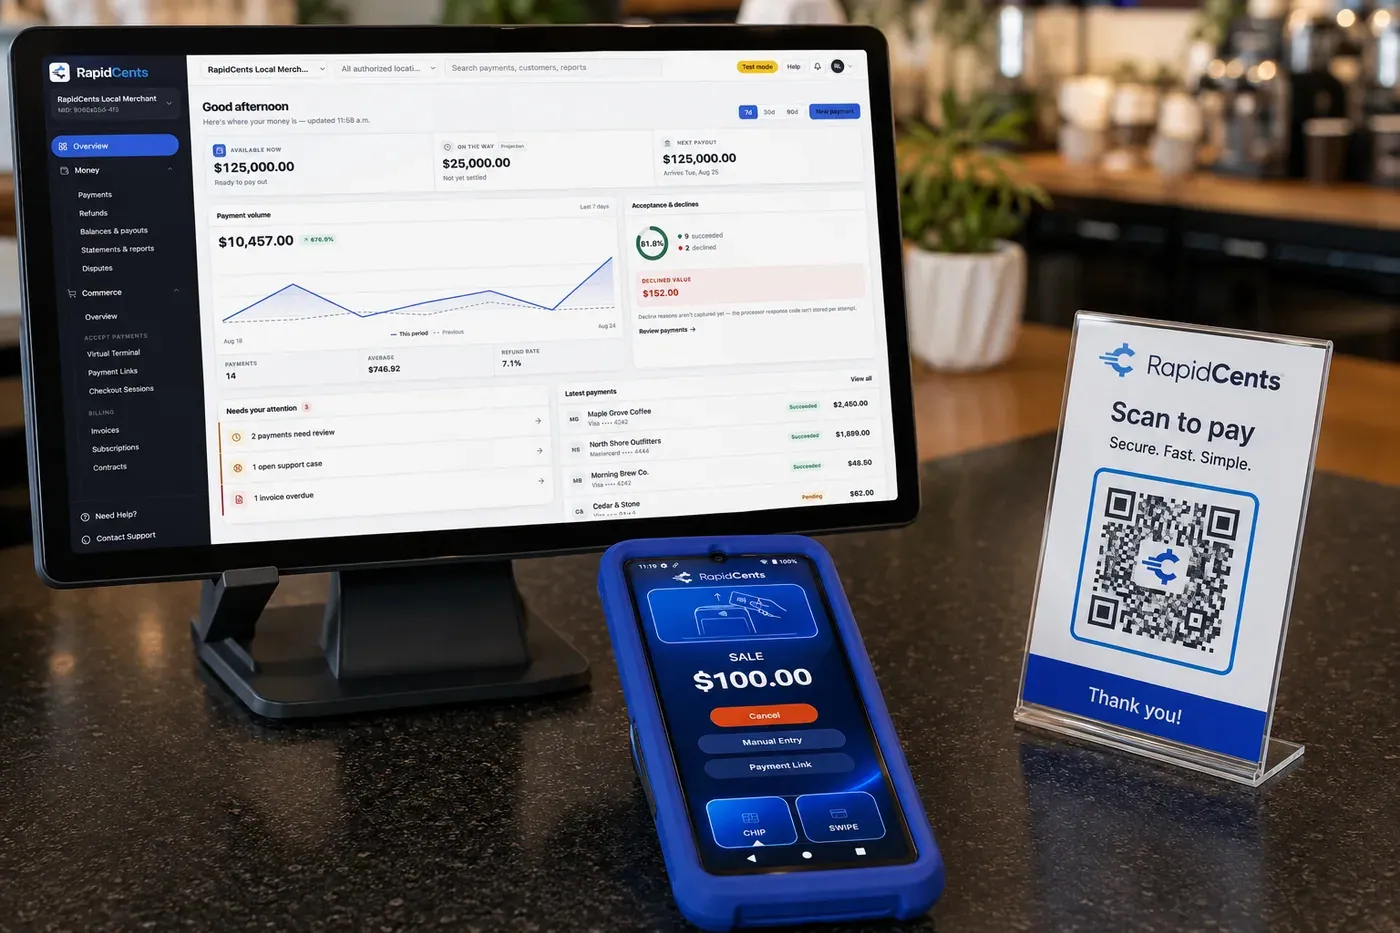
A RapidCents shop counter: the payments dashboard on a monitor showing available balance and the day's volume, a card terminal displaying a $100.00 sale, and a scan-to-pay QR card beside them. Payment Processing
RapidCents payment processing connects authorization, settlement and reporting across in-person, online and…
Explore


Implementation approach
Statement review
A current statement, read line by line. A quote produced without one is a guess.
Structure comparison
Your card mix priced under the current structure and under interchange-plus, on the same volume.
Configuration changes that cost nothing
Some cost is operational: keyed transactions that could have been card-present, batches closed late, address verification data not sent. These are worth fixing regardless of provider.
Review after the change
Compare the first full statement under the new arrangement against the old one on effective rate, not on the rate you were quoted.
What does not change
Interchange
Interchange is set by Visa and Mastercard and is identical for every provider; PIN debit is priced differently again. No provider discounts interchange, and an offer that appears to is discounting something else.
The cards your customers carry
You cannot choose which cards customers present. You can see what each type costs you, and route and price accordingly.
Your acceptance itself
Changing pricing structure does not change which cards you accept or how the customer pays.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
In practice, a U.S. Statement review using card mix, transaction channel, average ticket and total billed fees. Keep separate controllable charges from costs determined by the transaction. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Lower payment costs does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers how a fair comparison holds assumptions consistent and includes monthly, hardware and other applicable charges. Label estimates clearly. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Lower payment costs does not, by itself, prove delivery or win a dispute.
What to confirm
In practice, what the merchant receives from a review and what still requires an approved quote. Use the Fed fee-challenge evidence only as context, never proof of savings. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Lower payment costs does not, by itself, prove delivery or win a dispute.
Frequently asked questions
Why did my effective rate rise when nothing changed?
Because card mix changes on its own. A shift toward premium consumer or commercial cards raises the interchange you pay without a single contract term moving, which is why the effective rate is worth recalculating each quarter rather than at renewal.
Is interchange-plus always cheaper than a flat rate?
No. Interchange-plus is more transparent, not automatically cheaper. For a business with a low average sale and mostly debit, a flat rate can be competitive. The comparison has to be run against your own statement.
What is the fastest cost to remove?
Usually the non-rate lines, because they are fixed regardless of volume. A monthly minimum, a statement fee or rental on equipment you already own costs the same whether you process well or badly.
Does surcharging or a cash discount lower my cost?
Those shift cost to the customer rather than removing it, and both carry network and state rules about disclosure. Treat them as a pricing decision to take advice on, not as a processing setting to switch on.
Why does the same card cost different amounts?
Because interchange depends on how the card was presented as well as what it is. The same card tapped at a terminal, keyed by hand and used online can fall into three different interchange categories.
What should I have ready for a statement review?
One full monthly statement, including the fee summary pages most people discard. Total volume, transaction count and every fee line are what the effective rate is calculated from.
What information is needed to compare U.S. processing costs?
For a business in the USA, list the approved statement and business inputs, explaining why transaction mix matters. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Does a lower advertised rate guarantee a lower total bill?
For a business in the USA, in practice, the need to compare all relevant charges and the same volume assumptions. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should an estimated saving be verified after switching?
For a business in the USA, a practical view covers like-for-like statement comparison and explain changes in volume or card mix. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



