


Scale payment operations as volume increases
Growing business is for businesses in the USA. Evaluate growing business for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Businesses adding a channel
A counter business opening an online store, or an online business opening a counter. The second channel is where the reporting usually splits.
Owners hiring their first finance person
Once someone other than the owner closes the month, the reporting has to be legible to a person who was not there when it was set up.
Operators approaching a volume tier
Rising volume changes which pricing model is cheaper. A blended rate that suited a small book often stops suiting a larger one.
Common challenges
A provider per channel
Terminal from one company, gateway from another, invoicing from a third. Three settlement timetables and three fee structures to reconcile every month.
Reporting that will not add up
Two systems that both call something a sale, but count refunds, tips or day boundaries differently, produce totals that never agree.
Pricing set for a smaller business
Rates agreed at launch rarely get revisited. Card mix shifts toward premium and commercial cards as the customer base grows, and the effective rate drifts up without a contract term changing.
The RapidCents approach
Inventory what you run today: every device, gateway, login and the fee each one carries.
Decide which channels consolidate now and which wait, because a working integration is rarely worth breaking on schedule.
Compare pricing models against your actual card mix rather than against a headline rate.
Move channels one at a time, with the previous route still live until the new one reconciles.
Hand finance a single deposit report and confirm it ties to the bank before old accounts are closed.
Recommended capabilities
One account across channels
Counter, online, keyed and invoice payments settle under the same merchant account, so one deposit report covers the business.
Interchange-plus pricing where you qualify
Interchange and assessments pass through at cost with the RapidCents markup stated separately, so a rate movement is attributable to one side or the other. Amex operates on its own arrangement.
Reporting with channel breakdown
In-person, online and keyed totals separated, with interchange, assessment and processor fee columns in the export.
Integration paths that scale
Certified POS and ERP connectors, RapidBridge for software already in place, and REST APIs with signed webhooks when you need to build.
Role-based access
Cashier, manager and admin roles with audit trails, so a growing team stops sharing one login.
Related products
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and tokenize…
Explore
Payments taken inside existing business software through RapidCents, with the terminal and dashboard in the same workspace. Integrated Payments
RapidCents integrated payments connect certified POS and ERP systems so sale amounts, tips, refunds and…
Explore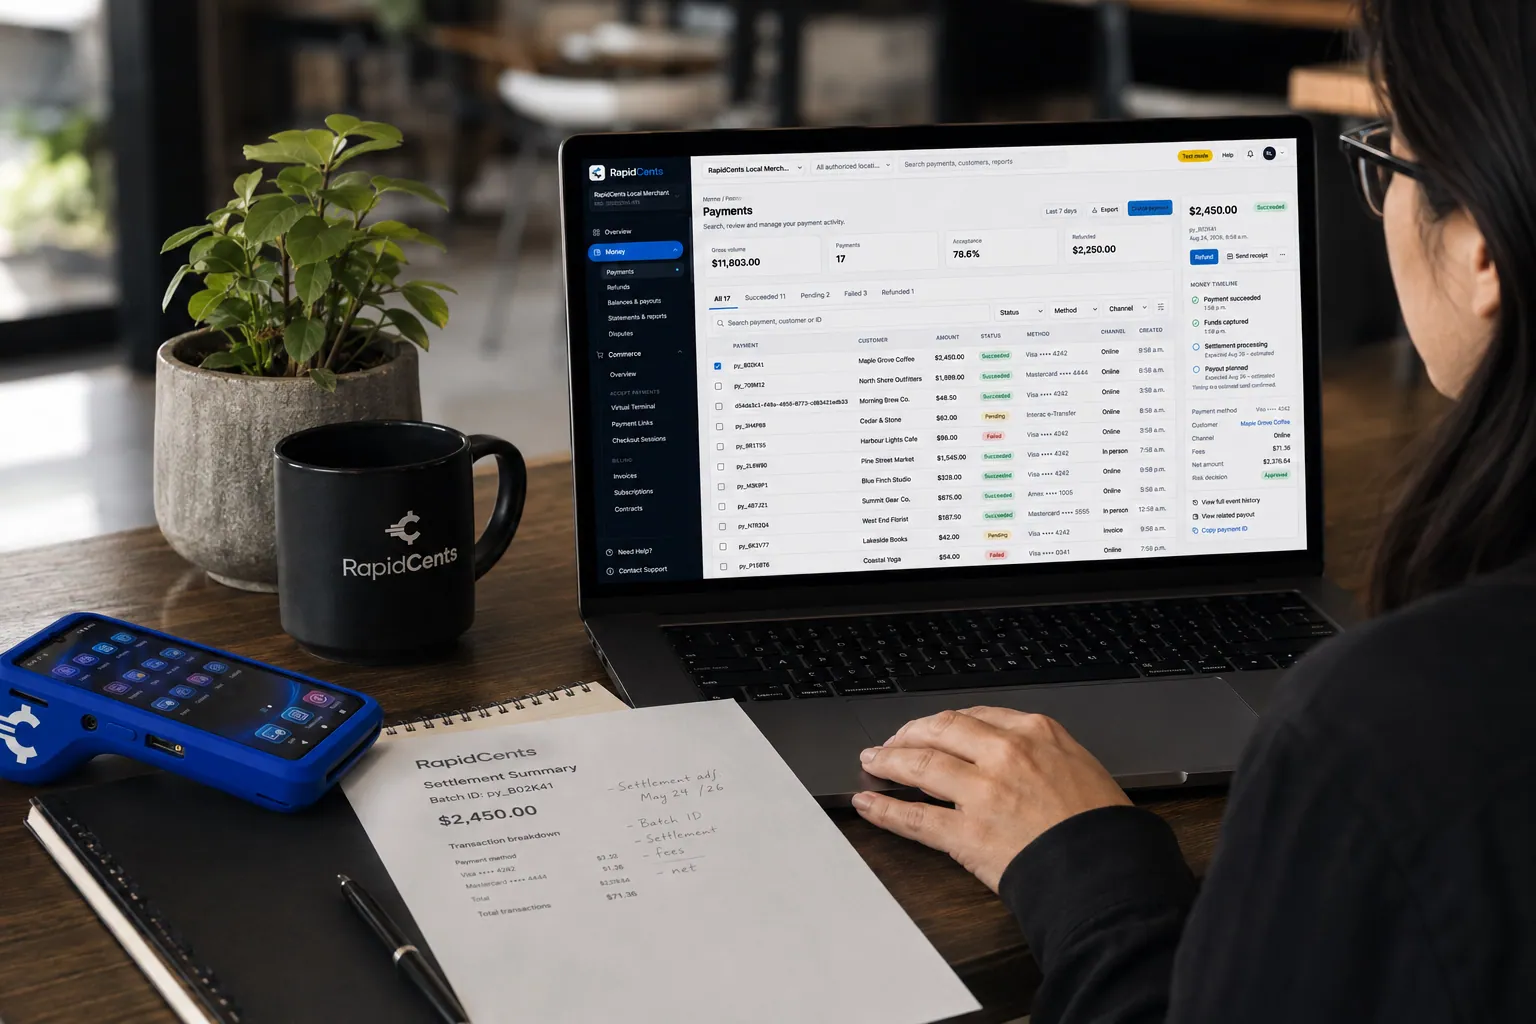
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF export…
Explore


Implementation approach
Discovery
Map current providers, contract end dates and any equipment still under lease. Exit terms decide sequencing more often than technical fit does.
Configuration
Channels, users and the reporting exports finance needs are set up before any live volume moves.
Parallel testing
Test transactions run on the new channel while the existing one still handles real customers.
Phased go-live
One channel at a time, with the first deposit on each checked before the next begins.
What does not change
Your existing software
A POS or ERP that works today usually stays. Integration connects payments to it rather than replacing it.
Customer-facing prices and receipts
Consolidating processing changes what you pay, not what the customer pays or sees at checkout.
Interchange itself
Interchange is set by Visa and Mastercard and is the same for every provider; PIN debit is priced differently again. What differs between providers is the markup on top and how clearly it is shown.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
A practical view covers U.S. Merchant moving from one checkout process to additional staff, channels or locations. Name the operational trigger for each change. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Growing business does not, by itself, prove delivery or win a dispute.
The problem and the limit
In practice, permission changes, daily reconciliation and handling of refunds as more employees participate. Avoid equating higher volume with automatic lower pricing. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Growing business does not, by itself, prove delivery or win a dispute.
What to confirm
Provide a phased adoption plan and a checklist of facts to bring to a review: volume mix, current tools, desired channels and staffing. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Growing business does not, by itself, prove delivery or win a dispute.
Frequently asked questions
Does higher volume automatically mean a lower rate?
Volume affects the markup a provider can offer. It does not affect interchange, which the networks set by card type and by how the card was presented. A large business taking mostly premium credit can carry a higher effective rate than a smaller one taking mostly debit.
Can I keep one provider for a channel that already works?
Yes. Consolidation has real value, but a working integration on a live channel is an asset. Move the channels where cost or reconciliation actually hurts, and leave the rest until there is a reason.
What breaks when we add a second location?
Usually reporting and permissions. Two sites under one flat account produce one undifferentiated total. Location-level MIDs and scoped user access keep the two sets of numbers separate while still rolling up.
How do we compare two offers honestly?
Compare effective rate — total monthly cost divided by total volume — over the same statement period, then read what sits below the rate: monthly minimums, statement fees, equipment rental and any non-compliance charges.
Who owns the integration work?
For certified POS and ERP connectors, RapidCents and the partner guide the sandbox test cases together. For custom software, your developers build against the REST API and a sandbox, with an integration specialist on the RapidCents side.
What does finance get that they did not have before?
Deposit-level detail tying each settlement back to the transactions inside it, channel breakdown in the same export, and scheduled CSV delivery so the file arrives without anyone logging in to produce it.
When should a growing U.S. business review its payment setup?
For a business in the USA, name operational changes that justify a review, without claiming a mandatory transaction threshold. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can we add a new payment channel before replacing our existing software?
For a business in the USA, in practice, supported configurations and compatibility assessment. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Will higher processing volume change our pricing?
For a business in the USA, in practice, that a review may consider volume and transaction mix; terms depend on the actual proposal and agreement. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



