


Bank-to-bank collection
Collect larger invoices directly from a bank account
ACH Bank Payments is for businesses in the USA. US merchant comparing bank-account collection with cards, including authorization, verification, returns and eligibility. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Suited to high-value invoices
- Mandates on file
- Reported beside card volume

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
B2B invoicing
Collect large invoices without card interchange.
Memberships and dues
Predictable recurring debits from a bank account.
Property and services
Rent, retainers and scheduled service billing.
Core capabilities
Mandate capture
Collect and store authorization before the first debit.
Scheduled debits
Run one-off or recurring debits on the dates you agree with the customer.
Retry handling
Failed debits follow a retry schedule with clear status reporting.
Reconciliation
Bank payments settle into the same deposit reporting as card volume.
Customer notifications
Customers receive notice before a debit is taken.
How it works
Collect the customer's authorization and bank details securely.
Schedule a one-off debit or a recurring series.
RapidCents submits the debit on the agreed date.
Failed debits follow the retry schedule you configure.
Settlement and status appear in the merchant dashboard.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with ACH / Bank Payments
Capabilities on the same account, so the parts below connect without a second integration or a second contract.
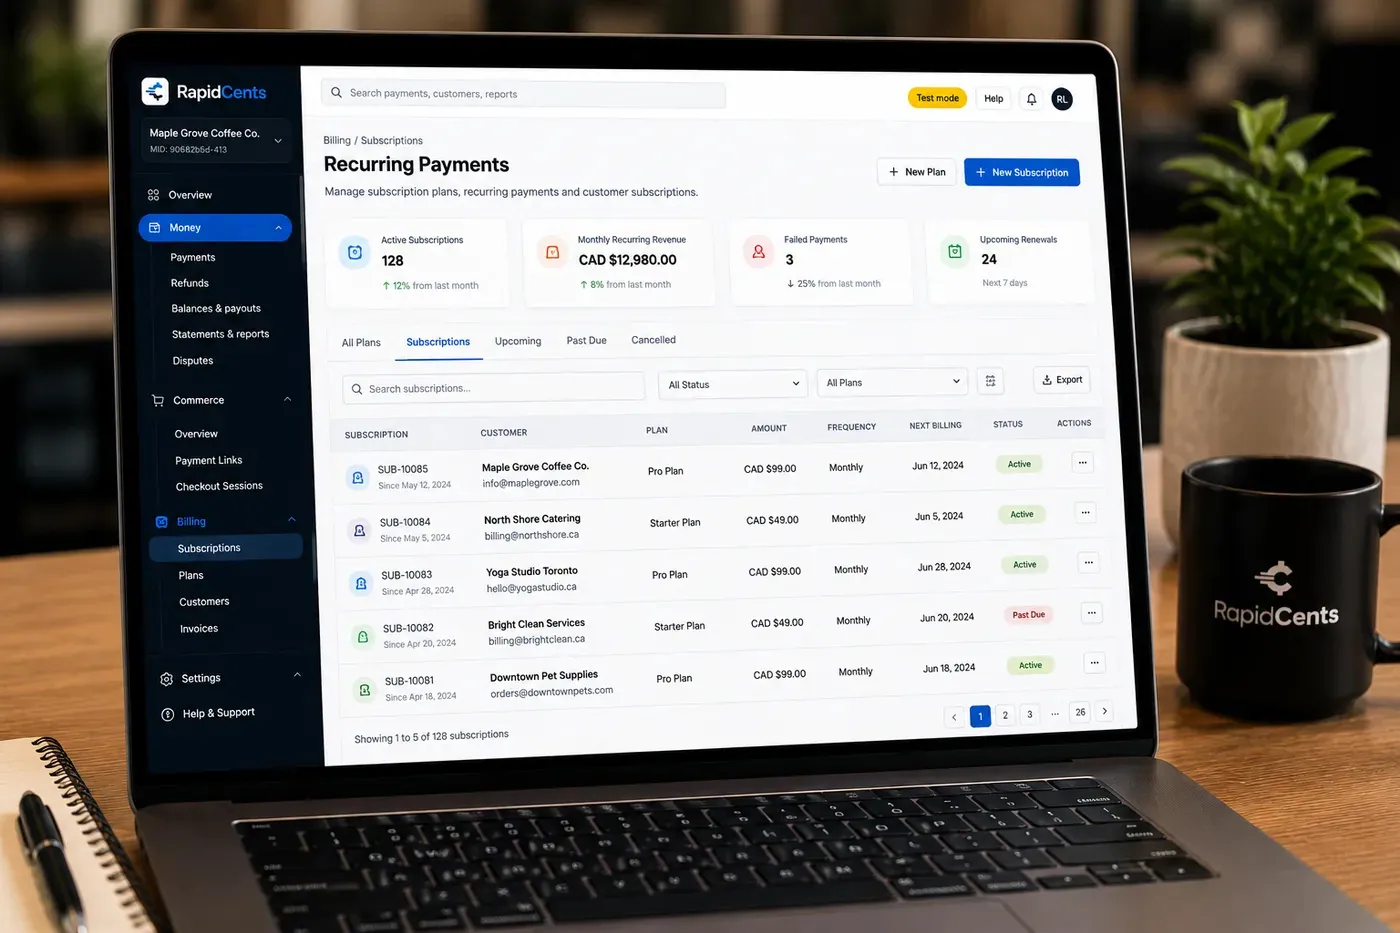
The RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring payments
Schedules, subscriptions and instalments billed from a stored credential.
Explore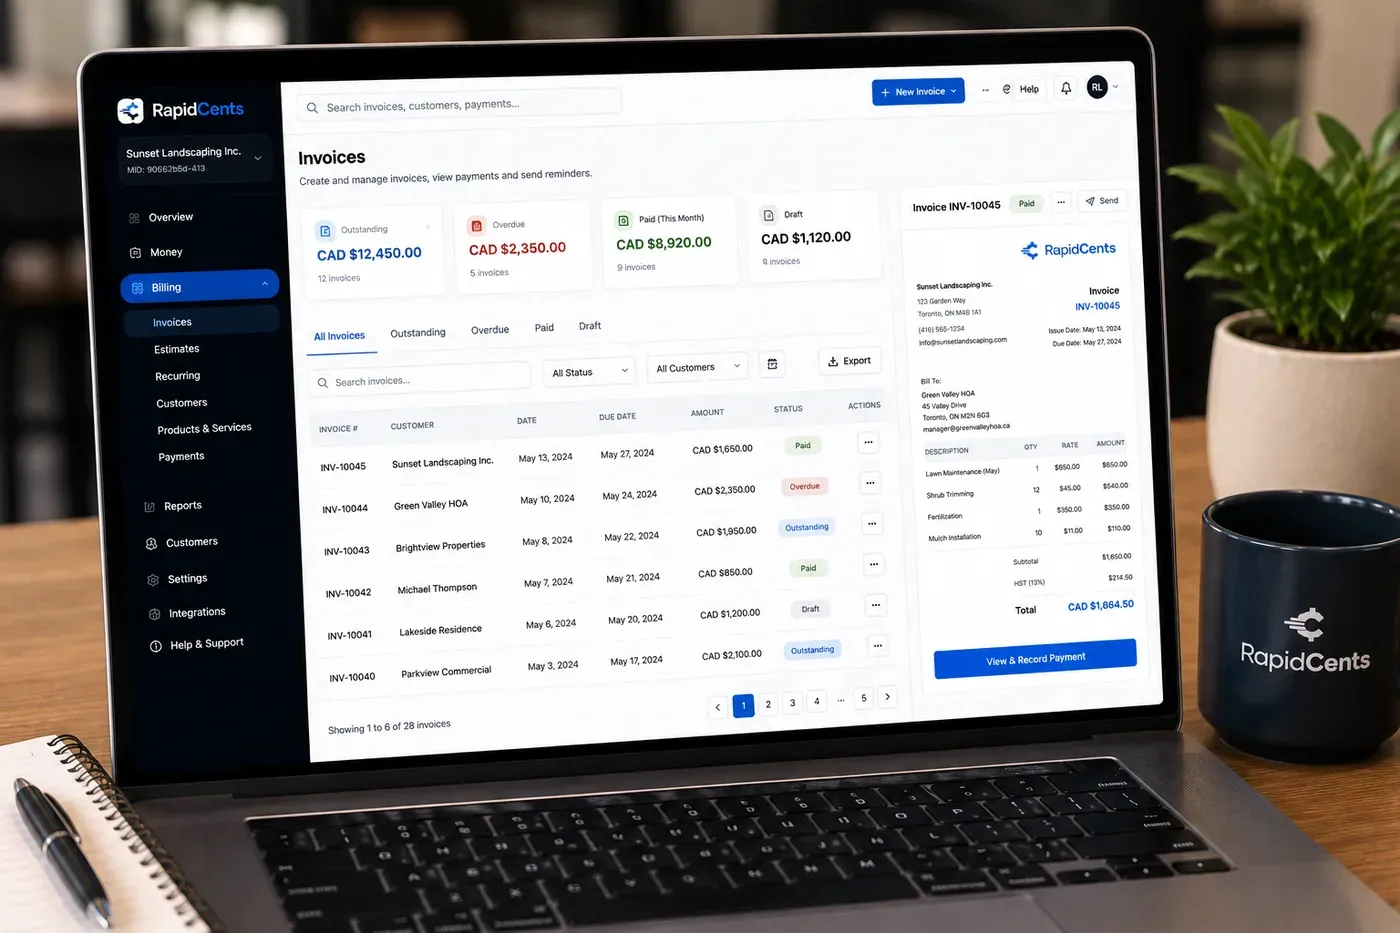
The RapidCents invoices screen: outstanding, overdue, paid and draft totals across the top, the invoice list below them, and a preview of one invoice on the right with its line items and a View & Record Payment button. Invoicing
Send an invoice that carries its own payment page and reconciles itself.
Explore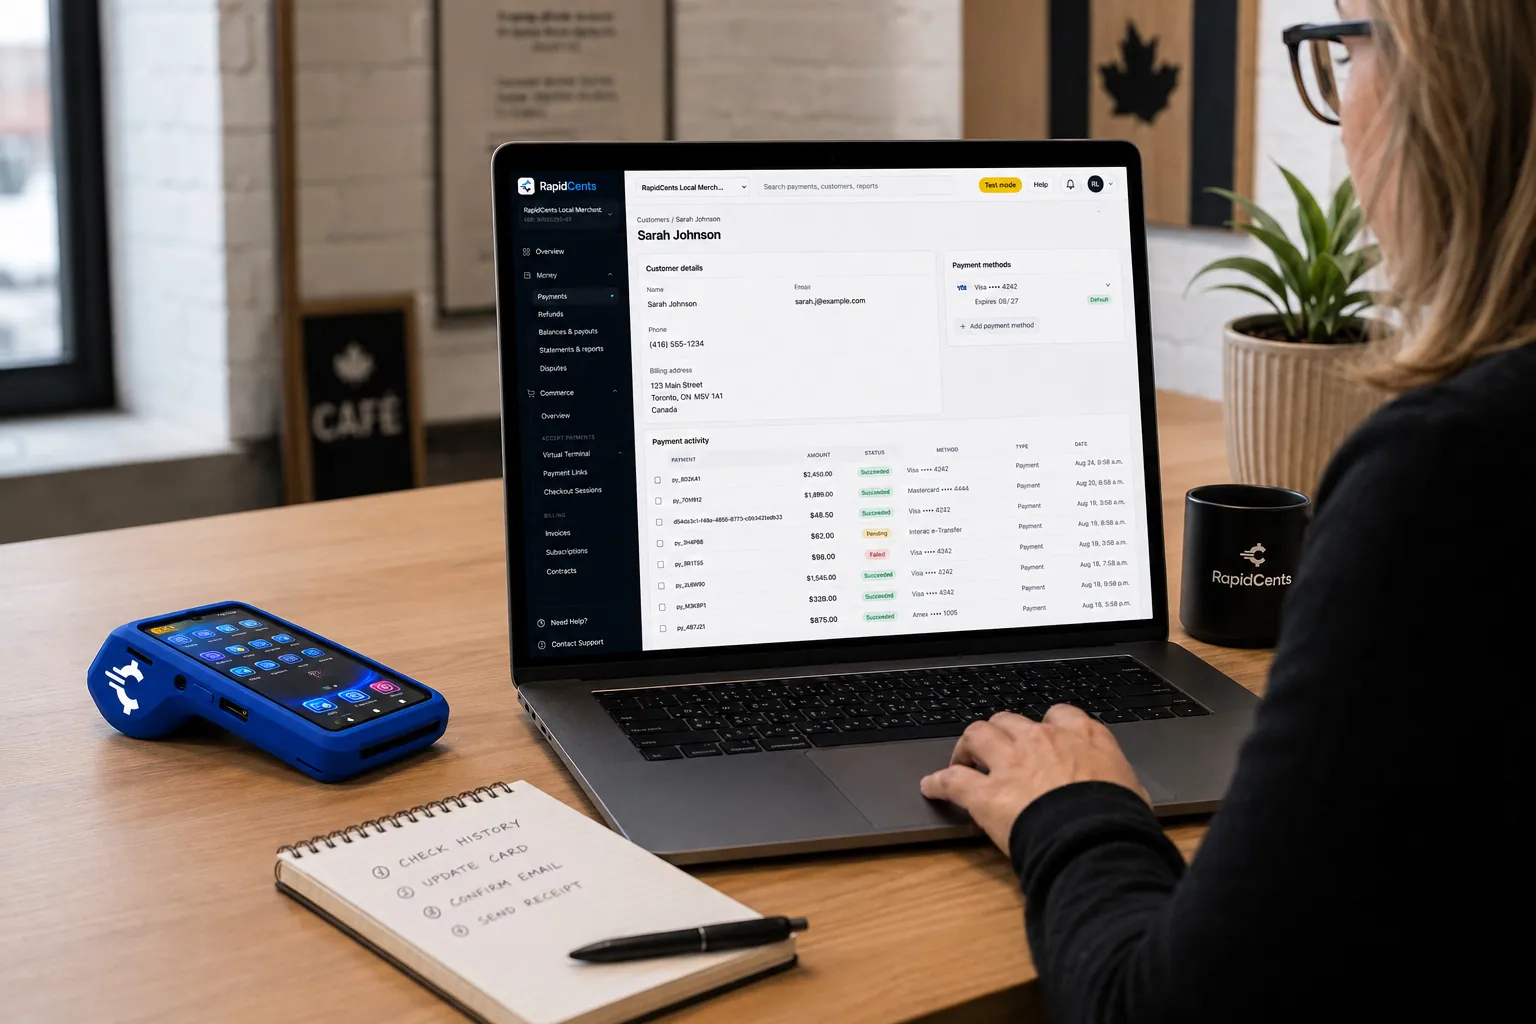
A RapidCents customer profile holds saved cards and invoices, so a return visit can be charged without re-keying the card. Customer profiles
One customer record holding contact details, stored credentials and payment history.
Explore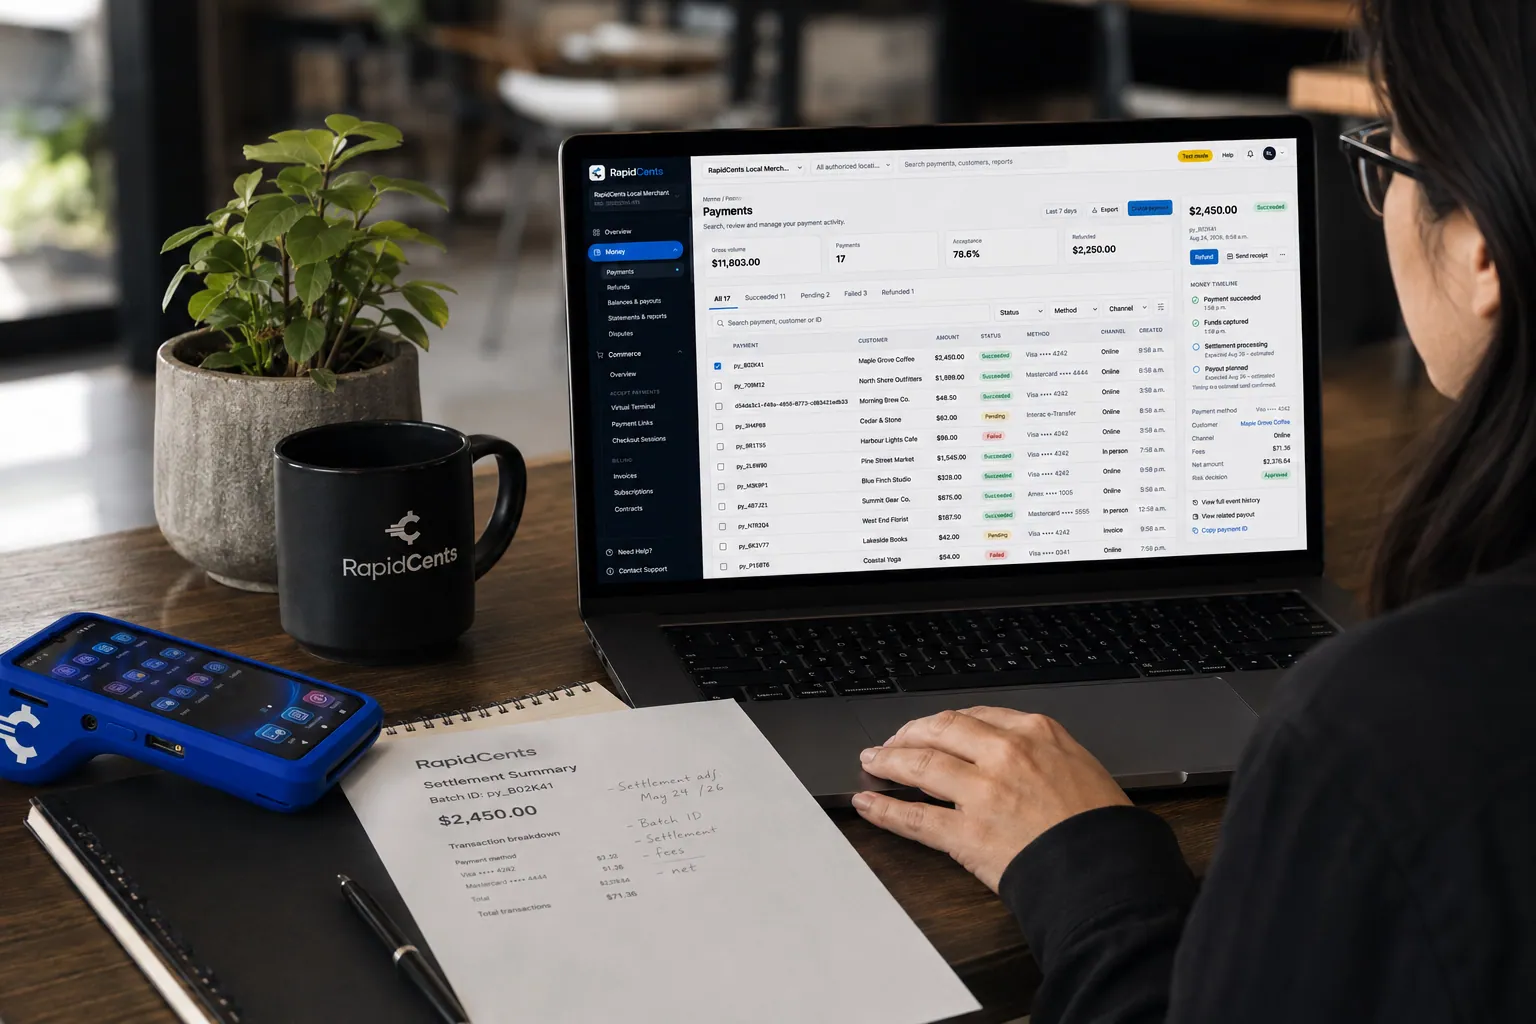
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting and reconciliation
Deposit-level detail that ties settlements back to the transactions behind them.
Explore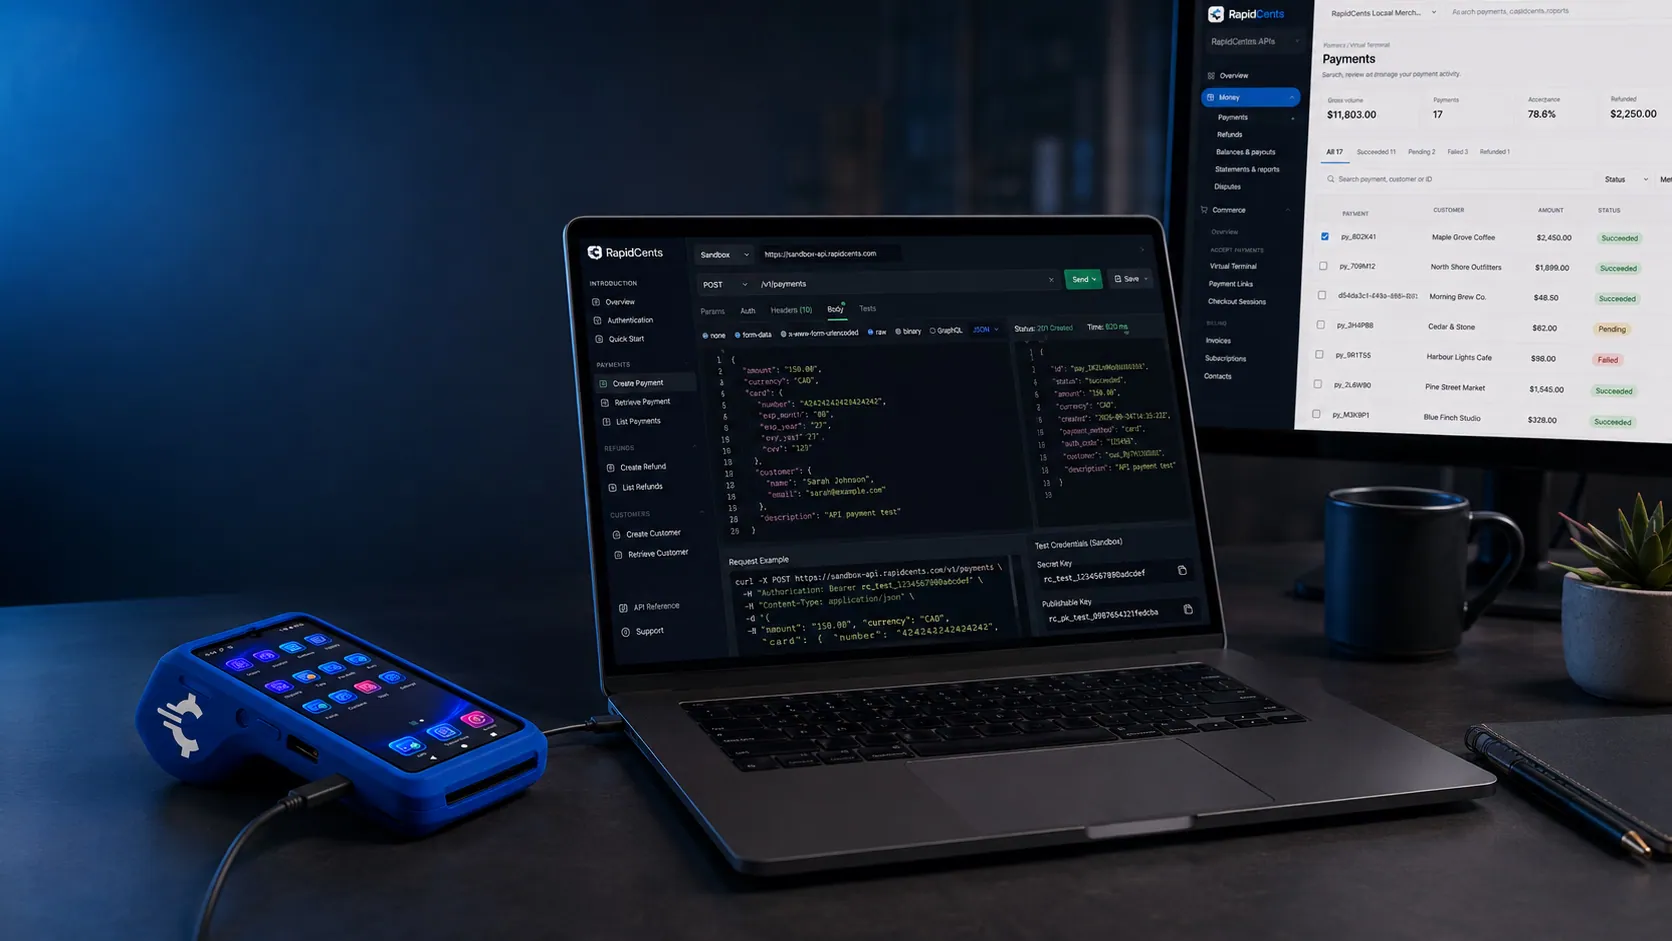
A RapidCents API request and its response on a developer workstation, with the merchant dashboard and a test terminal. RapidCents APIs
REST endpoints for payments, customers, refunds and reporting.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Build a US invoice-payment example with the verified collection channel, customer authorization, bank-account verification and reconciliation status. Clearly separate sending a debit request from funds becoming available. Show how staff handle a pending payment without treating it as a completed card sale. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. ACH Bank Payments does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers returns, unauthorized-payment reports, duplicate submissions and supported retry controls. Ask operations to supply the actual notices and authorization records. Review flat-cost or lower-cost claims against full pricing and transaction assumptions; do not describe ACH as risk-free, irrevocable or universally cheaper. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. ACH Bank Payments does not, by itself, prove delivery or win a dispute.
What to confirm
US availability is a publication gate. Before you rely on this, confirm processor/banking arrangements, business eligibility, supported accounts, USD handling, entry types, limits, fees and cutoffs. For Canadian variants, name the approved domestic bank-payment service separately; mention U.S. ACH or cross-border access only if confirmed. State timing only from approved terms. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. ACH Bank Payments does not, by itself, prove delivery or win a dispute.
Questions about ACH / Bank Payments
When are bank payments better than cards?
On large or recurring invoices, where a percentage card fee costs materially more than a bank debit.
Do I need the customer's permission?
Yes. A mandate is captured and stored before any debit is submitted.
What happens when a debit fails?
It follows the retry schedule you configure, and the status is visible in the dashboard.
Can I run cards and bank payments together?
Yes. Both settle into the same reporting so finance reconciles once.
What exactly is a mandate, and how is it collected?
A mandate is the customer's authorization to debit their account. It is collected with the bank details on a secure surface, stored before the first debit is submitted, and kept on file for the life of the arrangement.
How is this different from recurring card billing?
Recurring card billing charges a stored card token, so it depends on the card staying valid and carries a percentage fee. A bank debit pulls from the account under a mandate. Both can run on the same account and land in the same deposit reporting.
Can my USA business accept ACH payments through RapidCents?
For a business in the USA, state approved US merchant/bank-account eligibility, enrollment and supported use cases. If unapproved, use an eligibility inquiry rather than a sales claim. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
When should I consider an ACH invoice paid?
For a business in the USA, in practice, confirmed statuses, funds availability and return handling; distinguish request acceptance from settlement. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What authorization and account verification are required?
For a business in the USA, the practical view covers actual offered entry types, authorization records, notices and verification options after compliance review. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
The RapidCents invoices screen: outstanding, overdue, paid and draft totals across the top, the invoice list below them, and a preview of one invoice on the right with its line items and a View & Record Payment button. Invoicing
RapidCents invoicing helps professional services, contractors and B2B suppliers create branded…
ExploreThe RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring Payments
RapidCents recurring payments manage subscription plans, membership renewals and installment…
ExploreA merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF…
Explore
Industries that run on ACH / Bank Payments
Labour Unions
Unions collect dues by payroll deduction or card, plus initiation fees, benefit…
Condo Corporations & HOAs
Condo corporations and property boards collect monthly common-element fees, special…
Alarm & Monitoring
Alarm and monitoring companies bill a small monthly fee across a very large base…
Home Healthcare
Home care agencies invoice families on a recurring schedule for booked visit hours, with…
Retirement Residences
Retirement and assisted-living residences bill monthly rent plus care levels and optional…
Solar Installers
Solar installers handle high-value contracts staged across deposit, equipment…
Auto Parts Retailers
Parts counters serve retail walk-ins and trade accounts on terms, so the same store needs…
Print & Sign Shops
Print and sign shops quote per job, take a deposit before production and the balance at…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



