


Cross-border payment processing
Accept payments internationally from customers outside your own market
International Payments is for businesses in the USA. US merchant accepting foreign-issued cards; distinguish acceptance from overseas onboarding, multicurrency settlement and remittances. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Foreign-issued cards
- Issuer-reason diagnostics
- Reported in one dashboard

- PCI DSS Level 1
- SOC 2 Type II
- Specialist support
- Interchange-plus available
- All major card brands: Visa, Mastercard, Amex, Discover, PIN debit
Who it's for
Exporters
Businesses worldwide selling to customers abroad.
Online retailers
Stores with traffic from outside your own market.
Software platforms
Products billing international customers.
Core capabilities
International card acceptance
Accept Visa, Mastercard and Amex credentials issued outside your own market.
Issuer-reason diagnostics
See the issuing bank's response on a cross-border authorization instead of guessing.
Risk rules
Tune velocity and verification rules for foreign-issued cards.
3-D Secure
Apply strong customer authentication where the issuer expects it.
Unified reporting
Domestic and international volume settle into the same reports.
Cross-border payment processing on one account
International and domestic payment processing share one merchant account, one gateway integration and one deposit schedule.
Online and in person
Take foreign-issued cards through hosted checkout, payment links and invoices, and from visitors paying at the counter.
What is cross-border payment processing?
Cross-border payment processing lets a business accept payments internationally: a card issued in another country is authorized by its foreign issuer, and the funds settle to the merchant's own account. RapidCents runs it on the same account, gateway and reports as domestic payment processing.
Definition
Cross-border payment processing is the handling of a card payment when the card was issued in a different country from the one where the merchant's account is based. It is how a business accepts payments internationally without opening an account in every country its customers live in.
How it works
The authorization request travels from the merchant's payment processor through the card network to the bank that issued the card abroad. The network marks the transaction as cross-border, the issuer applies its own fraud and approval rules, and the approved funds settle to the merchant's account.
Example
A software company sells a subscription to a customer in London whose Visa card was issued by a UK bank. The sale runs through the company's usual checkout, the UK issuer approves it, and the payment lands in the same deposit report as the company's domestic sales, identified as a foreign-issued card.
Why it matters
Cross-border card payments are declined more often and cost more to accept than domestic ones, because issuers apply stricter rules and card networks add cross-border assessments. Seeing why a foreign card was declined, and what each cross-border sale actually cost, is what separates a working international channel from lost orders.
How RapidCents handles it
RapidCents processes Visa, Mastercard and American Express cards issued abroad on the same merchant account as domestic payment processing, shows the issuer's decline reason, lets risk and 3-D Secure rules be set for foreign-issued cards, and itemizes cross-border costs on an interchange-plus statement.
How to accept payments internationally
Confirm where your international customers pay: an online checkout, payment links and invoices, or at the counter when they visit.
Enable international card acceptance on your RapidCents account. No second gateway or separate integration is needed.
Set risk and verification rules for foreign-issued cards, and apply 3-D Secure where issuers in your customers' regions expect it.
Show prices clearly and describe the charge the way it will appear on the cardholder's statement, which reduces disputes from customers abroad.
Review approvals and decline reasons by issuing region, and adjust the rules where good customers are being declined.
Reconcile international and domestic volume in the same deposit reports, and read cross-border costs line by line on your interchange-plus statement.
What cross-border payment processing costs
A cross-border payment carries costs a domestic sale does not. Each is charged by a different party, which is why a blended rate hides them and an interchange-plus statement shows them.
Foreign-card interchange
Set by the card networks and paid to the issuing bank. Interchange on cards issued abroad is generally higher than on domestic cards.
Cross-border assessments
Network fees added when the card's issuing country differs from the merchant's. On an interchange-plus statement they appear as their own lines.
Currency conversion
When the cardholder's bank converts the charge into their own currency, any foreign transaction fee is billed to the cardholder by their bank, not to the merchant.
Fraud and disputes
Card-not-present sales to customers abroad carry more fraud risk and slower dispute resolution, so verification rules and chargeback protection belong in the cost.
Processor markup
On interchange-plus pricing the processor's margin is stated separately from everything above, so you can see exactly what the processor charges for cross-border volume.
Related ways to get paid across borders
- Payment processingThe merchant account, authorization and settlement that every international and domestic payment runs on.
- Hosted checkoutA secure checkout page customers abroad can pay on without your systems touching card data.
- Payment linksSend a link by email or text to a customer in another country and get paid by card.
- 3-D SecureStrong customer authentication for issuers that expect it on cross-border card-not-present sales.
- Fraud preventionDevice, IP, location and VPN signals on every attempt, which matter most on foreign-issued cards.
- Interchange-plus pricingSee interchange, cross-border assessments and the processor margin as separate lines.
How it works
Enable international acceptance on your account.
Set risk and verification rules for foreign-issued cards.
Apply 3-D Secure where the issuer requires it.
Monitor approval and decline reasons by region.
Reconcile international volume in the same reports as domestic.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with International Payments
Capabilities on the same account, so the parts below connect without a second integration or a second contract.
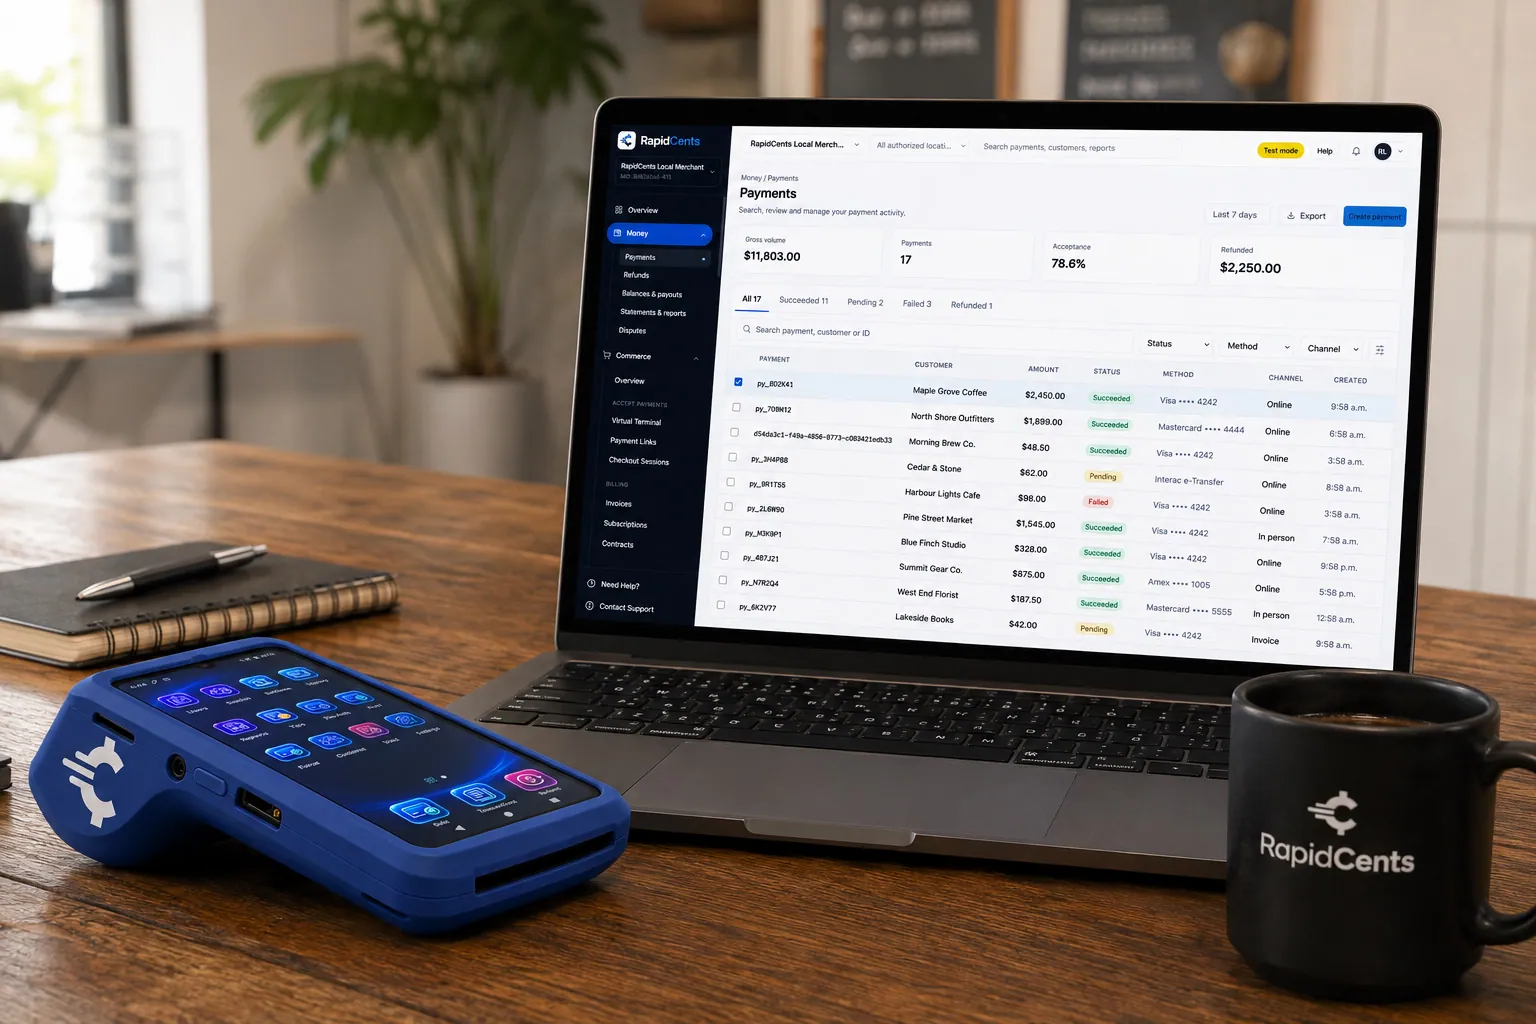
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment gateway
The authorization layer every online RapidCents payment runs through.
Explore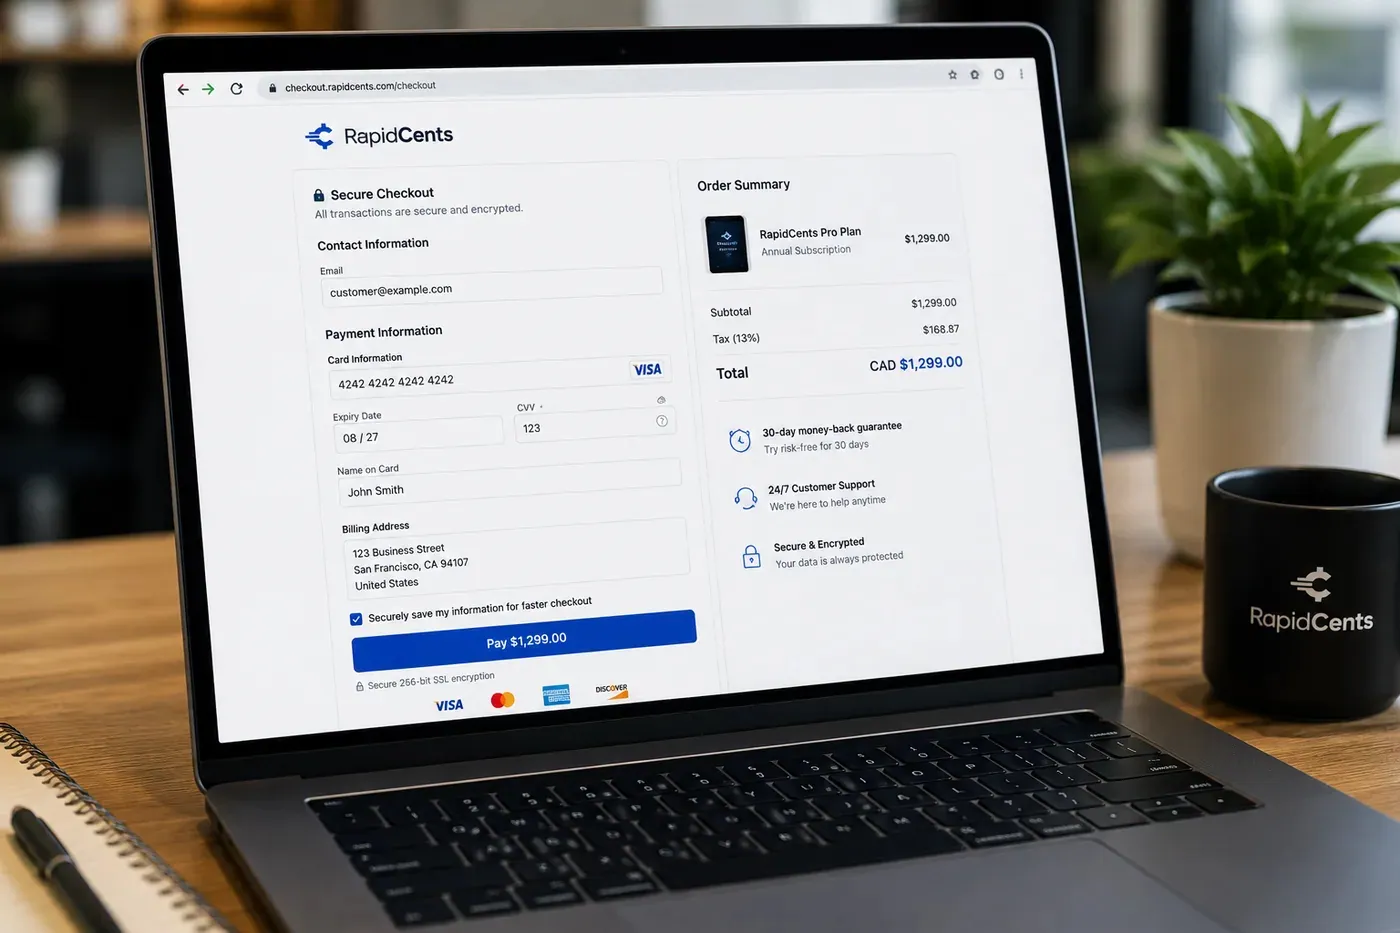
A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted checkout
A branded payment page RapidCents hosts, which keeps card data off your servers.
Explore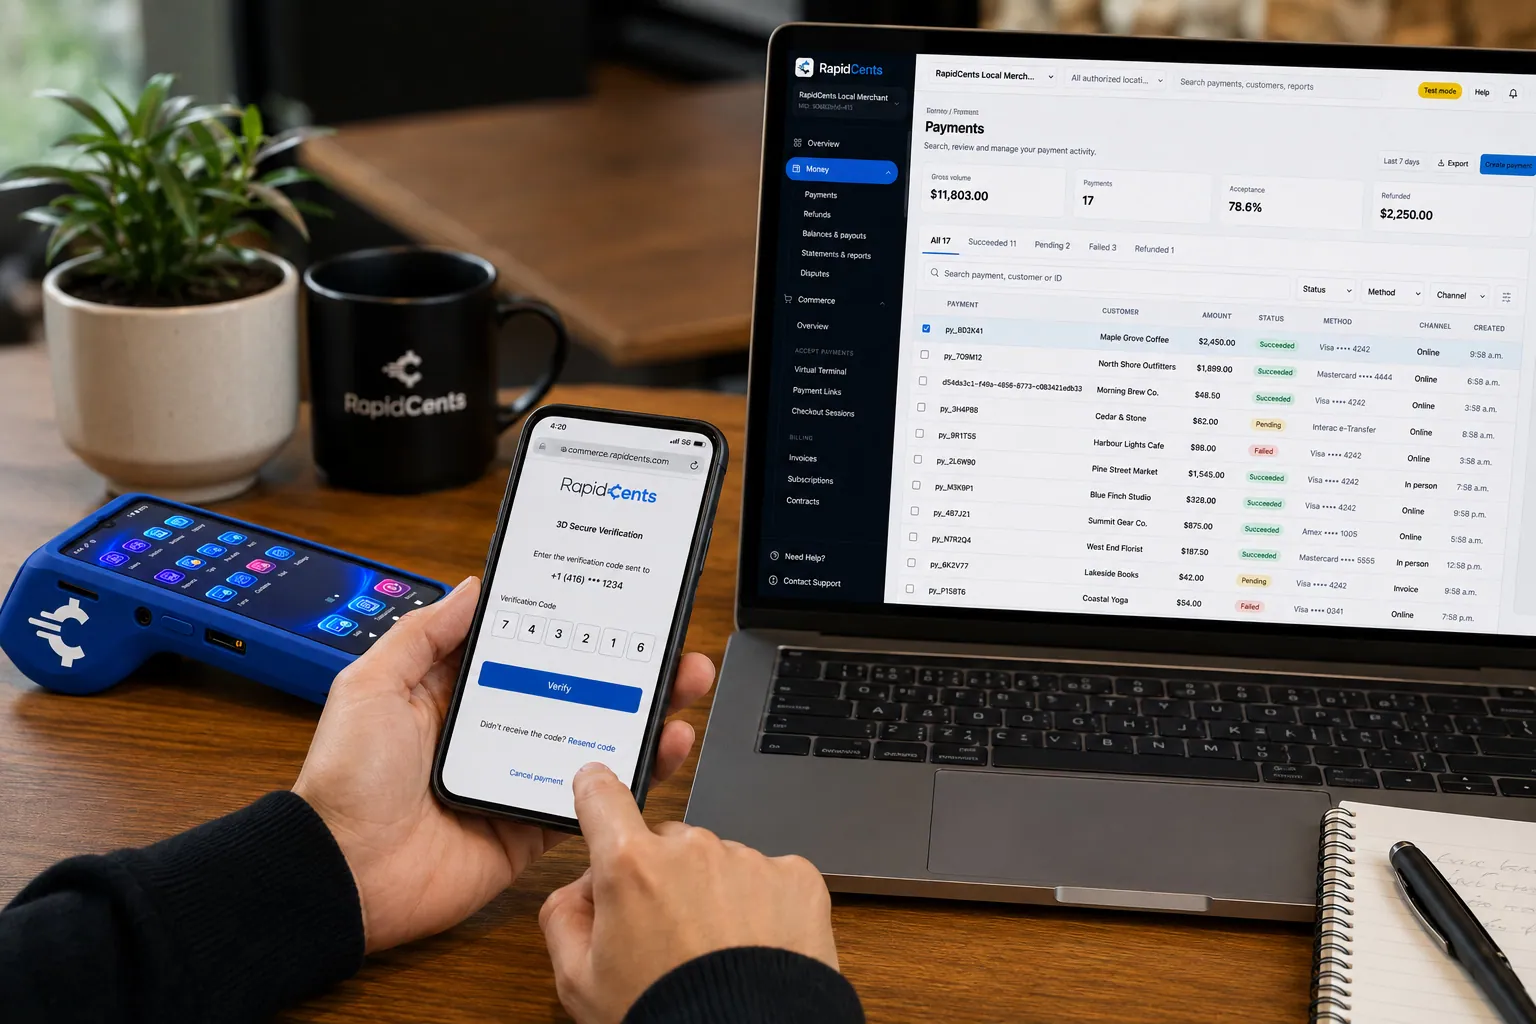
A cardholder completes 3-D Secure on RapidCents checkout, so the issuer can authenticate the online payment. 3-D Secure
Issuer authentication on online payments, which shifts fraud chargeback liability.
Explore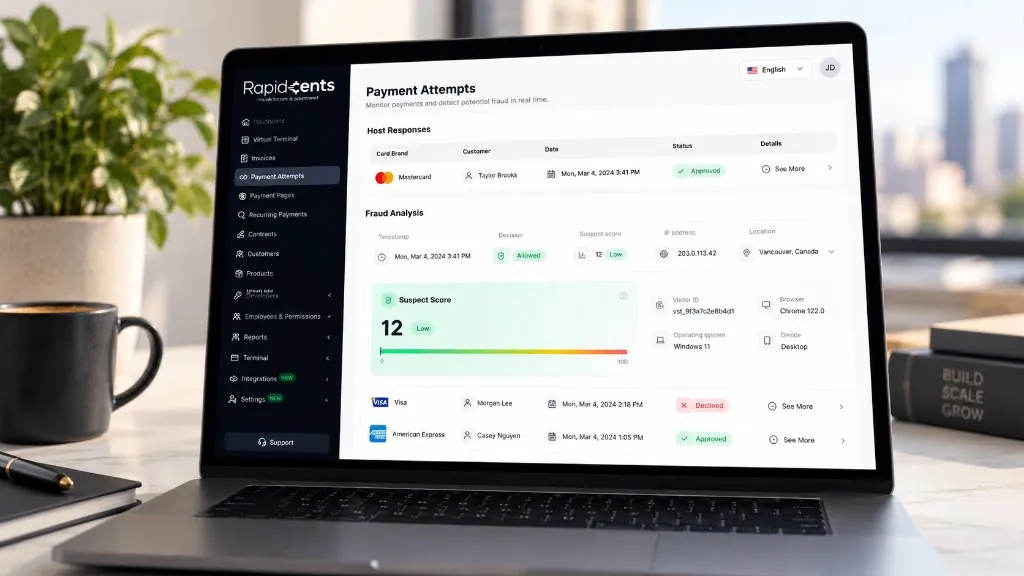
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud prevention
More than 180 signals checked on every payment attempt in under a second, and a fraud score you decide on.
Explore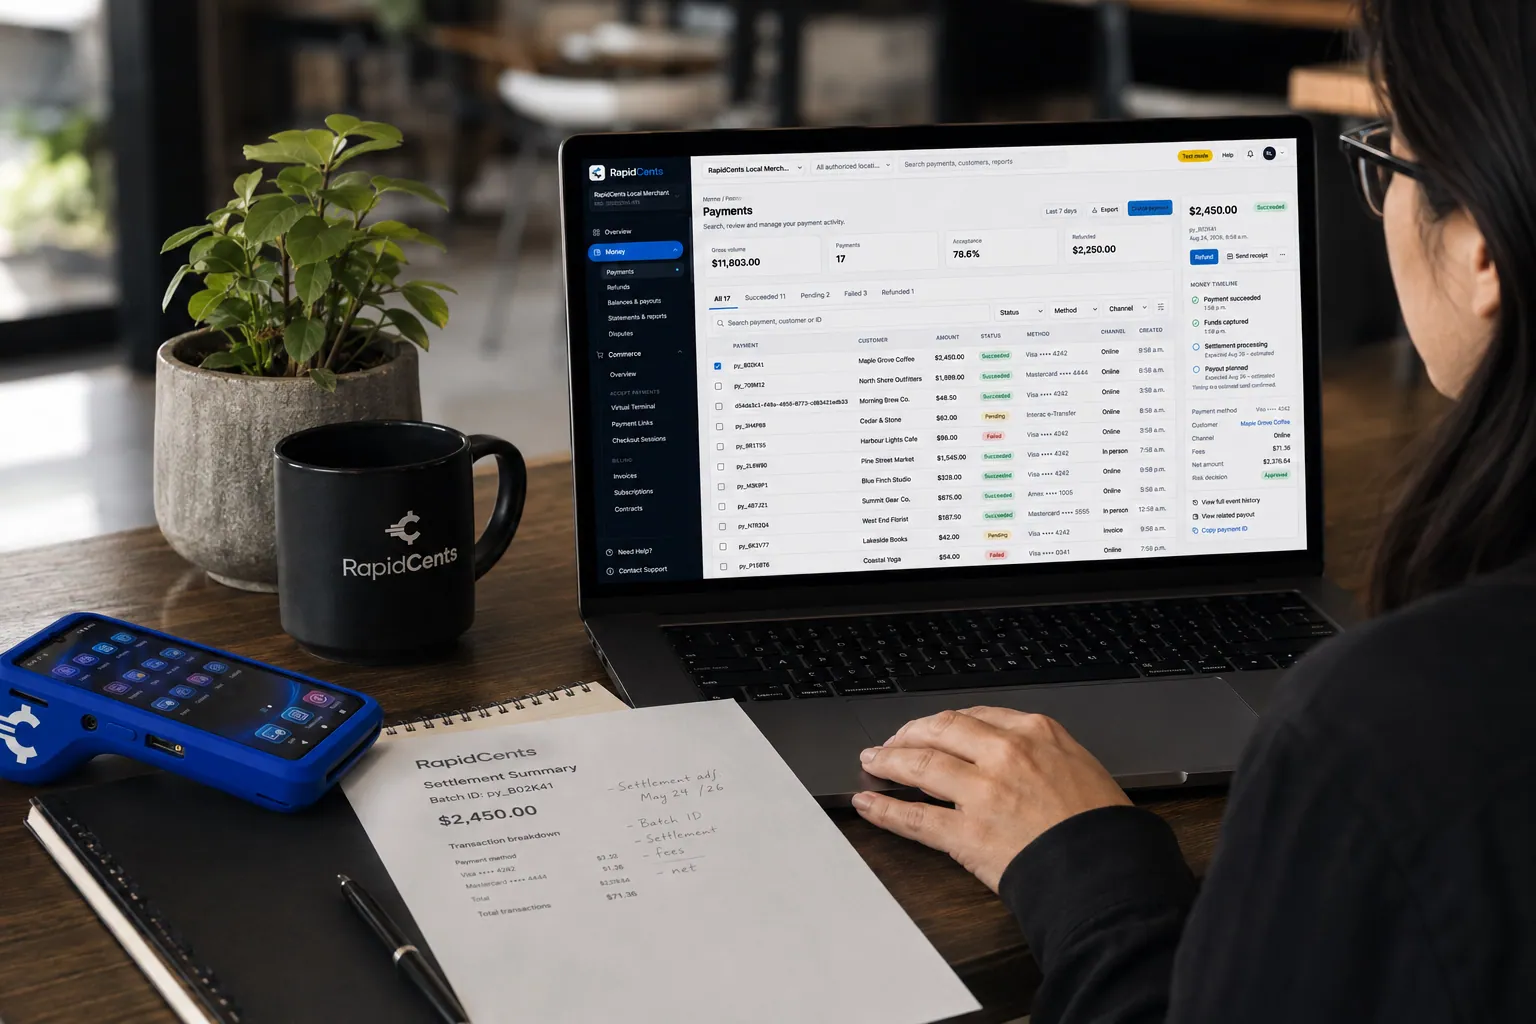
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting and reconciliation
Deposit-level detail that ties settlements back to the transactions behind them.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A payment specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Use a US store serving a buyer with a foreign-issued card. In practice, the verified authorization, authentication and reporting flow. Keep separate buyer location, issuing country, displayed currency and settlement currency so readers understand what cross-border acceptance actually covers. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. International Payments does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers an international decline, approved verification settings and refund/dispute handling. Any improved-approval claim needs evidence and scope. Do not suggest changing geography rules guarantees approval or permits restricted countries and business categories. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. International Payments does not, by itself, prove delivery or win a dispute.
What to confirm
Before you rely on this, confirm US eligibility, foreign-card brands, permitted markets, presentment/settlement currencies and conversion/cross-border charges. Keep separate overseas customer acceptance from onboarding foreign businesses or paying foreign sellers. Replace worldwide and all-currency claims with an approved availability table. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. International Payments does not, by itself, prove delivery or win a dispute.
Questions about International Payments
Why do issuers treat cross-border cards differently?
Issuers apply stricter rules to authorizations from another country. RapidCents shows the issuer's reason and supports 3-D Secure where it helps complete the sale.
Does this change my settlement?
Settlement continues through the same account and appears in the same deposit reporting.
Is 3-D Secure required?
It depends on the issuer and region. Rules can be applied selectively rather than to every transaction.
Can I see performance by country?
Approvals and issuer responses can be reviewed by issuing region.
Which card brands can I accept from outside your own market?
Visa, Mastercard and Amex credentials issued abroad. PIN debit is a domestic network, so it stays part of your volume rather than your cross-border volume.
Do I need a second gateway or a separate integration?
No. International acceptance is enabled on the account you already process on, through the same gateway integration, and the volume appears in the same reports rather than in a parallel system.
Cross-border orders feel riskier. What handles that?
Risk rules can hold foreign-issued cards to different velocity and verification thresholds than domestic ones, 3-D Secure can be triggered by region or amount, and disputes that still arrive are worked through Chargeback Protection.
Does accepting foreign cards change my pricing?
Cost follows card mix, and foreign-issued credentials are part of that mix. Interchange-plus pricing separates the network cost from the processing margin, so a cross-border transaction can be read on the statement instead of disappearing into a blended rate.
What is cross-border payment processing?
Cross-border payment processing is how a card payment is handled when the card was issued in a different country from the merchant's account. The authorization goes to the foreign issuer through the card network, and the approved funds settle to the merchant's own account. RapidCents runs it on the same account and reports as domestic payment processing.
Can a USA merchant accept a customer’s foreign-issued card?
For a business in the USA, state confirmed brands, channels and conditions; explain issuer decisions and country/risk restrictions. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What currency will my customer pay and my business receive?
For a business in the USA, keep separate display, presentment, conversion and settlement; name only verified currencies and fees. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Does international acceptance also cover overseas sellers or businesses?
For a business in the USA, distinguish customer acceptance, merchant onboarding and platform payouts, with specific eligibility reviews. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related products
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and…
ExploreA cardholder completes 3-D Secure on RapidCents checkout, so the issuer can authenticate the online payment. 3D Secure
3-D Secure asks the issuer to verify the cardholder and, where it applies, shifts liability for…
ExploreThe Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud Prevention
RapidCents checks more than 180 signals on every payment attempt in under a second — the device, IP…
Explore
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



