


Authentication where it earns its place
Add cardholder authentication without adding friction to every sale
3-D Secure asks the card issuer to authenticate the cardholder during an online checkout. Where authentication succeeds and network rules apply, liability for a fraudulent chargeback moves to the issuer. RapidCents applies it by rule, on amount, geography or risk signal, rather than on every sale. For businesses in Canada, confirm the rules set on your merchant account.
- Issuer-verified cardholders
- Liability shift where it applies
- Rules, not blanket friction

- PCI DSS Level 1
- SOC 2 Type II
- Canadian support
- Interchange-plus available
- All major cards: Visa, Mastercard, Amex, Discover, UnionPay, Diners Club & Interac Debit
Who it's for
Online merchants
Card-not-present sales carry the fraud liability.
International sellers
Some regions expect authentication by default.
High-ticket sellers
Larger orders justify the extra step.
Core capabilities
Risk-based rules
Trigger authentication by amount, geography or risk signal instead of every transaction.
Frictionless flow
Most authentications complete without a challenge screen.
Liability shift
Where authentication succeeds and the rules apply, fraud liability moves to the issuer.
Checkout integration
Works with hosted checkout and gateway integrations.
Outcome reporting
See authentication rates and their effect on approvals.
How it works
Set the rules that decide when authentication runs.
At checkout, the issuer evaluates the transaction.
Most authentications complete without a challenge.
A challenge appears only where the issuer requires it.
Reporting shows authentication and approval outcomes.
Dashboard and reporting
Transactions, deposits and exceptions visible in the RapidCents merchant dashboard.
Try it, edit values and click buttons
Merchant dashboard
- Today
- $4,218
- Deposits
- $12,482
- Disputes
- 2 open
- In-person
- $842
- Online
- $1,104
- Virtual terminal
- $392
Demonstration data only
Integrations
Merchant dashboard
Every transaction, deposit and exception lands in one dashboard.
APIs and webhooks
Connect the product to your own software with REST APIs and signed webhooks.
Partner connectors
Certified connectors for common POS, ERP and commerce platforms.
Works with 3D Secure
Capabilities on the same account, so the parts below connect without a second integration or a second contract.

A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted checkout
A branded payment page RapidCents hosts, which keeps card data off your servers.
Explore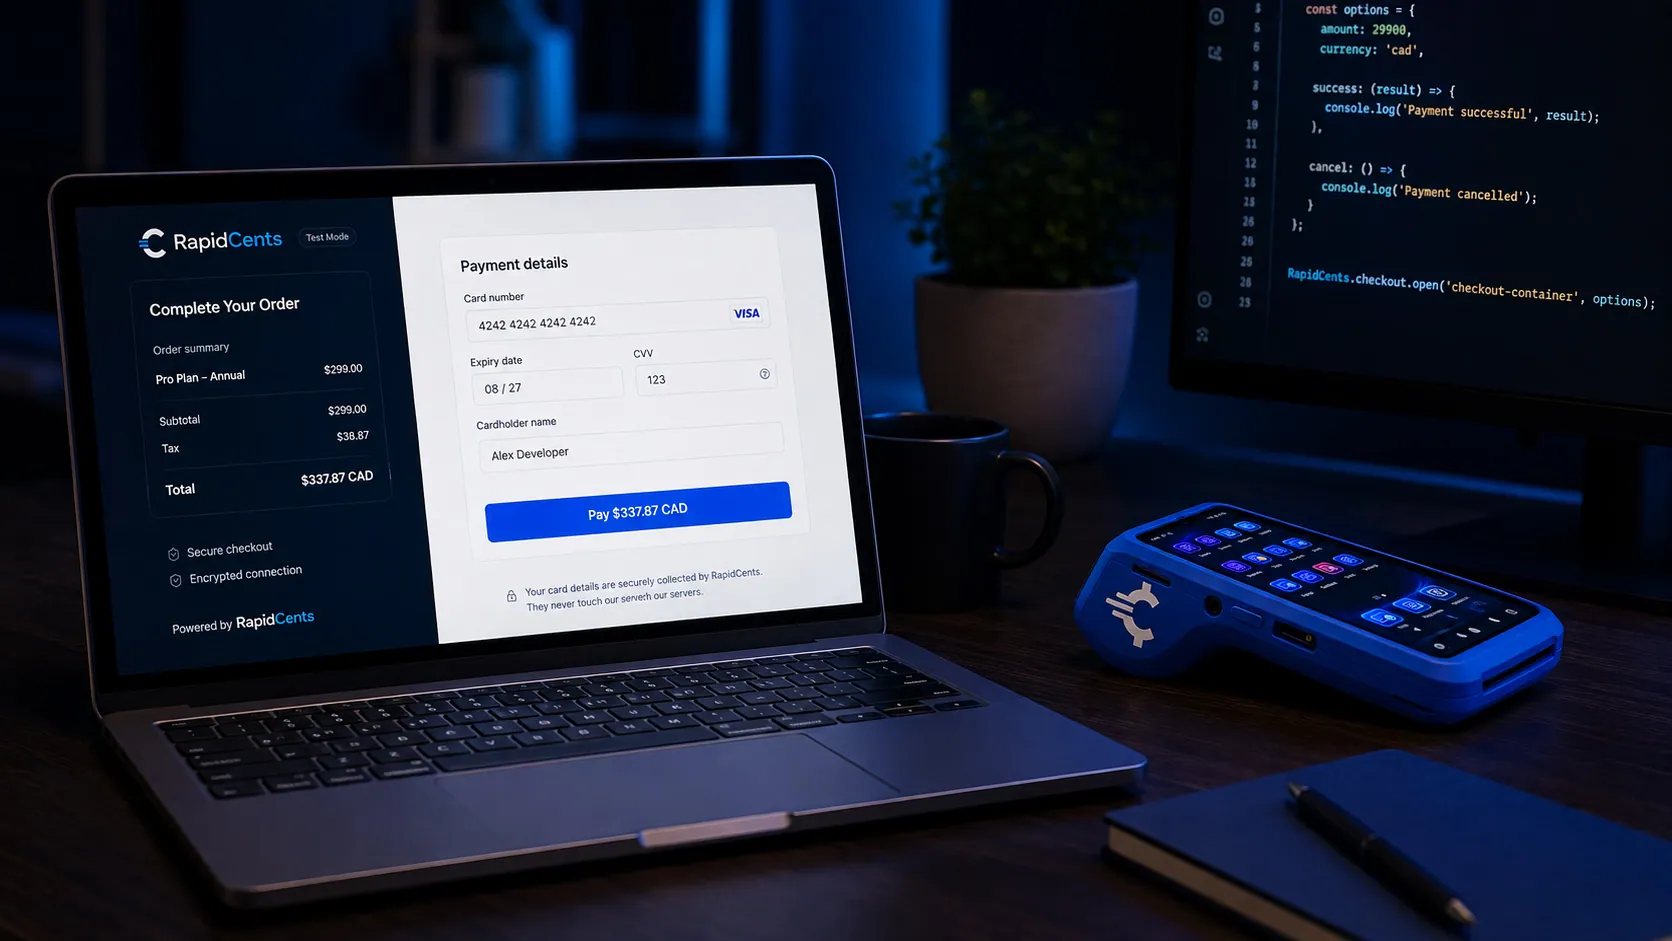
Rapid.js hosted card fields on a developer workstation, keeping card entry out of the merchant's PCI scope. Rapid.js
Embedded card fields that keep your checkout in your own design and out of PCI scope.
Explore
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment gateway
The authorization layer every online RapidCents payment runs through.
Explore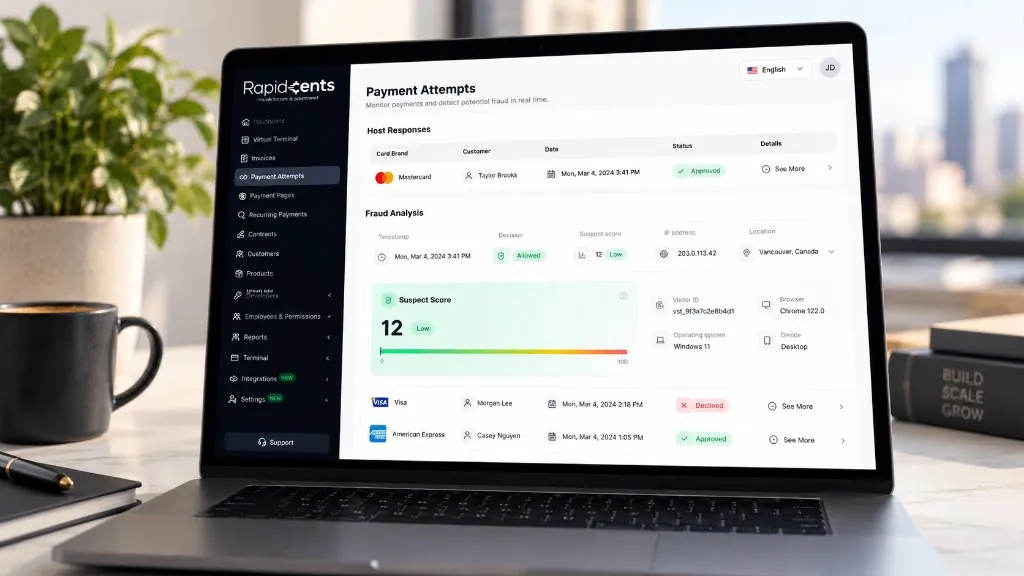
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud prevention
More than 180 signals checked on every payment attempt in under a second, and a fraud score you decide on.
Explore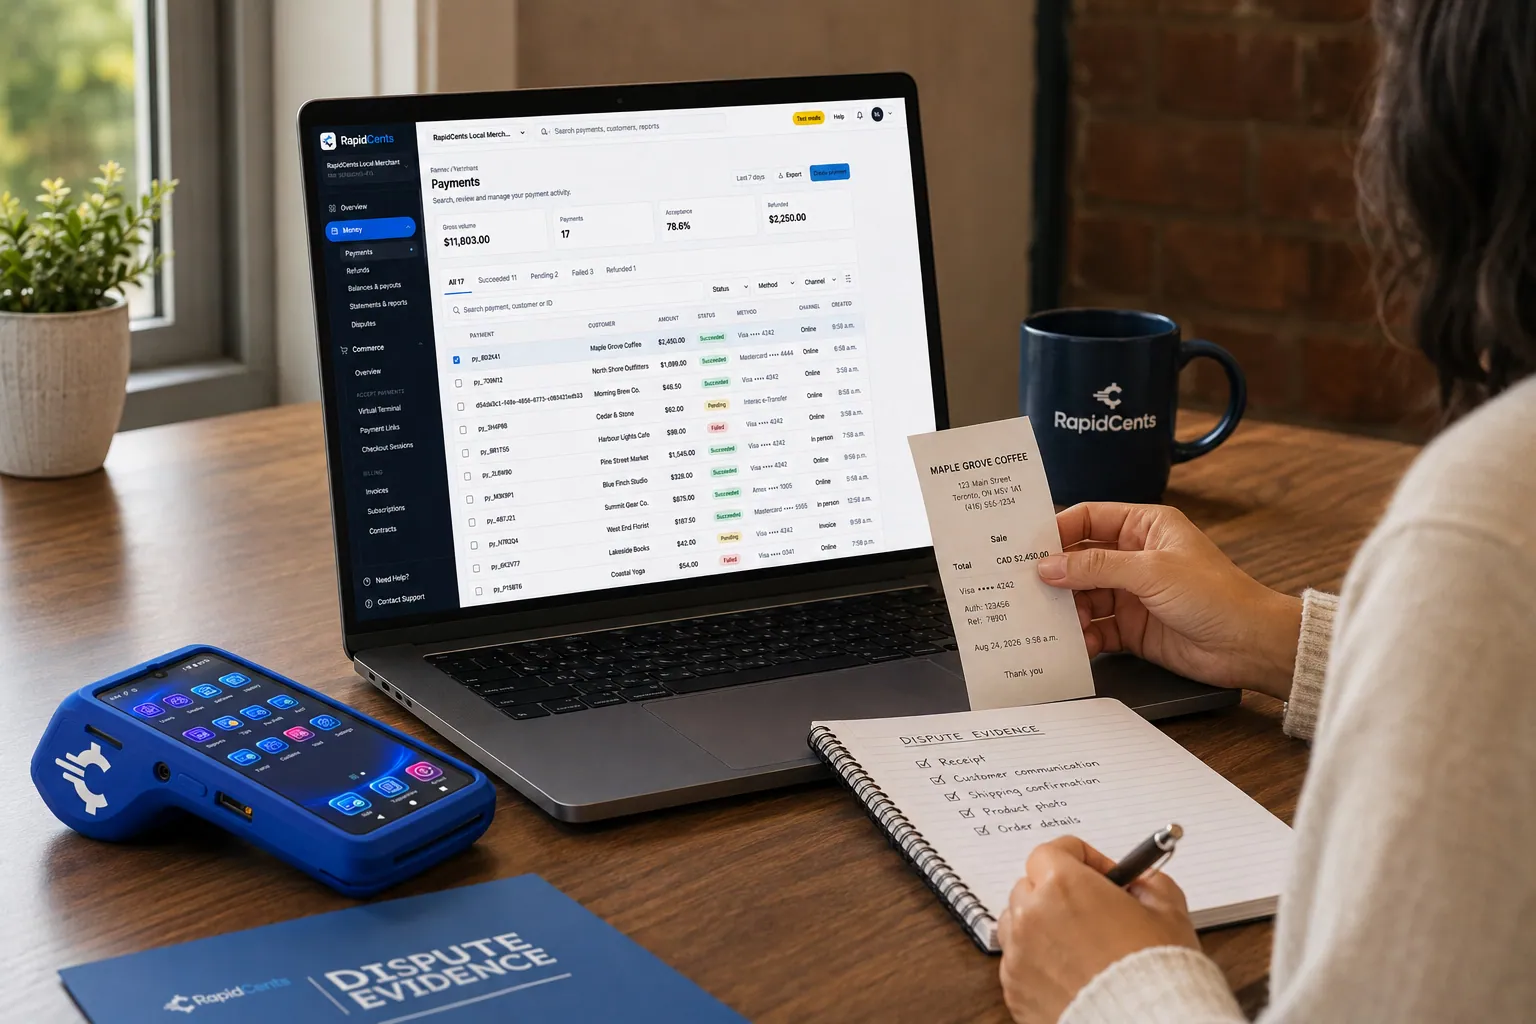
RapidCents assembles chargeback evidence from the original sale, with the terminal and receipts still at hand. Chargeback Protection
Dispute alerts and evidence assembly, so representment does not eat your week.
Explore


Security
PCI DSS Level 1
Processing runs on PCI DSS Level 1 audited infrastructure.
Tokenization
Card data is replaced with tokens, keeping raw credentials out of your systems.
Role-based access
Permissions and audit trails control who can see and do what.
Implementation
Discovery
A Canadian specialist reviews how your business gets paid today.
Configuration
Accounts, users and settings are prepared before you go live.
Testing
Run test transactions and confirm reporting before cutover.
Launch and support
Go live with training materials and post-launch support.
Pricing
Transparent pricing
Pricing depends on volume, card mix and configuration. Fee Check compares your current statement before you commit to anything.
Cards, currencies and settlement in Canada
What a RapidCents account in Canada accepts, the currencies it settles in, and when the money arrives.
Cards and methods accepted
Visa, Mastercard, American Express, Discover, UnionPay and Diners Club cards from any country, plus Interac Debit, Apple Pay, Google Pay and EFT/PAD bank payments, on one merchant account.
137+ currencies, settled in CAD or USD
Process in CAD, USD, EUR and 137+ currencies, and deposit payouts directly into your Canadian CAD bank account or your Canadian USD bank account, so USD sales are not converted twice.
Next-business-day funding and reconciliation
Batches close nightly and deposits arrive the next business day, based on cut-off times and eligibility, with deposit-level reporting in one RapidCents dashboard.
Questions about 3D Secure
Does 3-D Secure hurt conversion?
Applied to every transaction it can. Rule-based triggering limits it to the transactions where the protection is worth the step.
What is liability shift?
Where authentication succeeds and network rules apply, liability for a fraudulent chargeback moves to the issuer.
Will customers always see a challenge?
No. Most authentications complete in the background without a challenge screen.
Does it work with hosted checkout?
Yes, and with gateway API integrations.
Does 3-D Secure apply to in-person payments?
No. It authenticates the cardholder in a card-not-present checkout, which is where the merchant carries the fraud liability. In-person sales are protected by the chip and the terminal's own encryption instead.
Which transactions should trigger authentication?
The ones where the protection is worth the extra step: larger orders, regions whose issuers expect authentication by default, and transactions your risk signals flag. Authentication and approval reporting is what tells you whether a rule is set too wide.
Does 3-D Secure replace fraud screening?
No. Screening applies your own rules to the transaction, while 3-D Secure asks the issuer to authenticate the person behind the card. Most online merchants run both, and your rules decide which transactions get which treatment.
Is 3-D Secure charged as an extra?
It is configured on your RapidCents account alongside hosted checkout or the gateway, not sold as separate software. The account is priced interchange-plus: interchange and card network fees at cost, plus your RapidCents markup, stated in your Fee Schedule, and fees for equipment or services, if applicable.
What does 3-D Secure reporting show?
Authentication rates and their effect on approvals, for the transactions your rules sent to the issuer. The outcomes sit in the RapidCents merchant dashboard beside transactions, deposits and exceptions, so a rule that costs approvals is visible and can be narrowed.
Related products
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud Prevention
RapidCents checks more than 180 signals on every payment attempt in under a second — the device, IP…
ExploreA RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via…
ExploreA payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and…
Explore
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Canadian payment specialists
- Secure statement upload



