


Monthly Monitoring Billing and Card Updater for Alarm Companies
Alarm & Monitoring is for businesses in the USA. Compare payment options for installation deposits, monitoring bills and service visits; understand timing, payer authorization, exceptions and reconciliation for alarm and monitoring providers. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
Monitoring fee billed monthly across the subscriber base
Cards refreshed automatically before each cycle
Bank debit offered to subscribers who prefer it
Accounts that need a follow-up, listed with the issuer reason
Payment challenges
Keep monitoring collecting
Subscribers rarely cancel monitoring; RapidCents refreshes stored cards so the monthly charge stays current through expiry and reissue.
Too small to chase one at a time
The monthly amount is low enough that manually recovering a single account costs more than the account, so recovery has to be automatic.
Service continues while billing needs a follow-up
The panel keeps reporting whether or not the fee cleared, so RapidCents lists the accounts that still need a person before unbilled months accumulate.
Choose the right payment setup for Alarm & Monitoring
Choose alarm monitoring payment processing
For Alarm & Monitoring, map sign-up, scheduled billing, and renewal, online checkout and remote payment, and the sale and reconciliation with business systems before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Alarm & Monitoring
For Alarm & Monitoring, physical hardware may be secondary to the checkout flow. Prioritize gateway or payment-page requirements first, then add a terminal only when an in-person payment point is genuinely needed.
Compare payment processing fees
For Alarm & Monitoring, request a written fee breakdown covering scheduled billing, declined cards, and cancellations and online checkout and dispute handling. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Alarm & Monitoring payments
To set up Alarm & Monitoring payments, document how payment data moves into business systems and the checkout, confirmation, and refund path, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
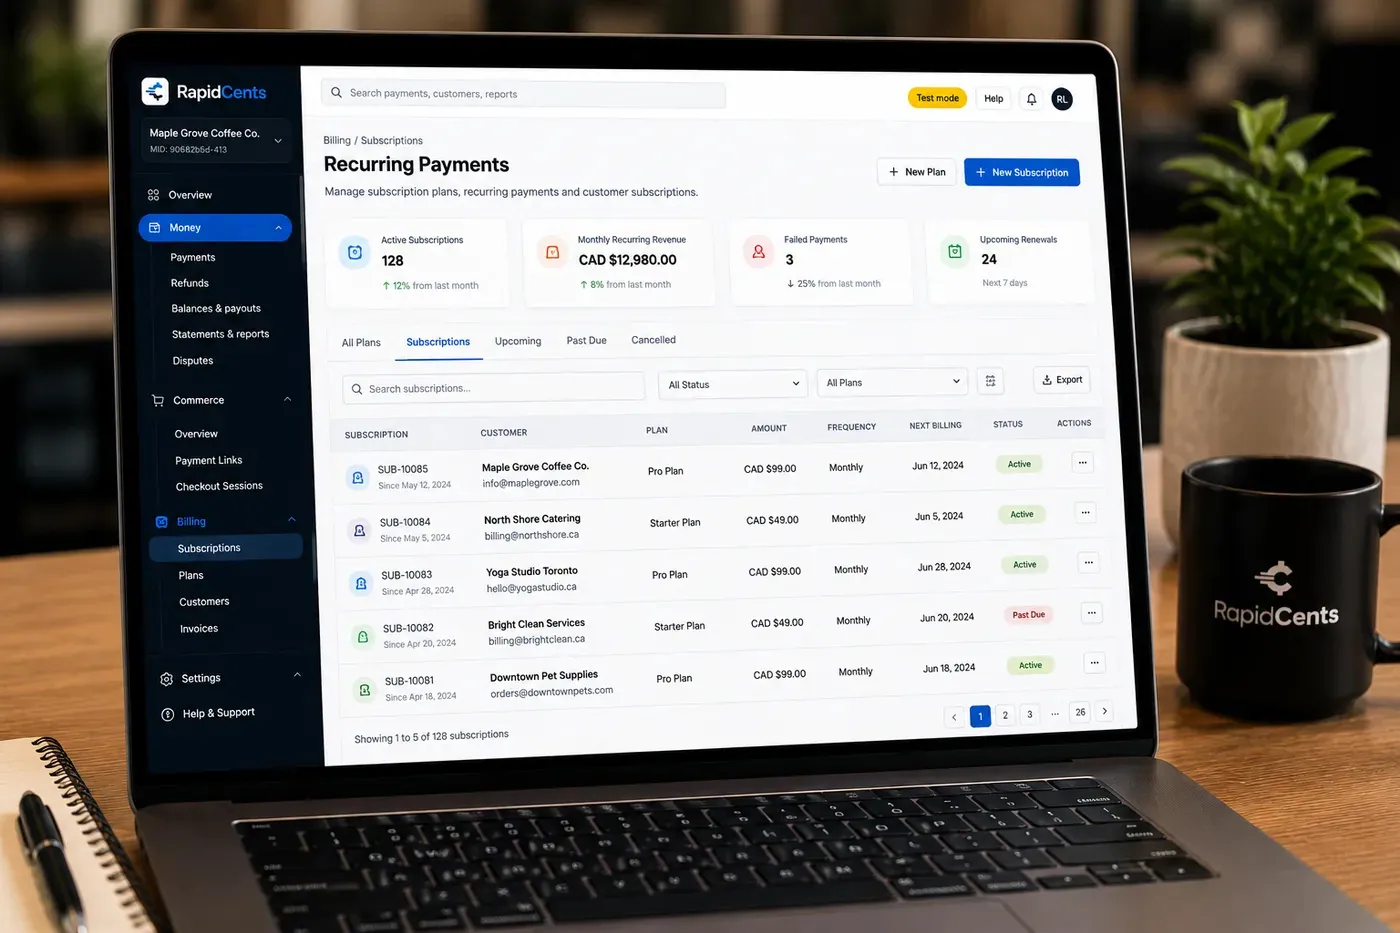
The RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring Payments
RapidCents recurring payments manage subscription plans, membership renewals and installment schedules with…
Explore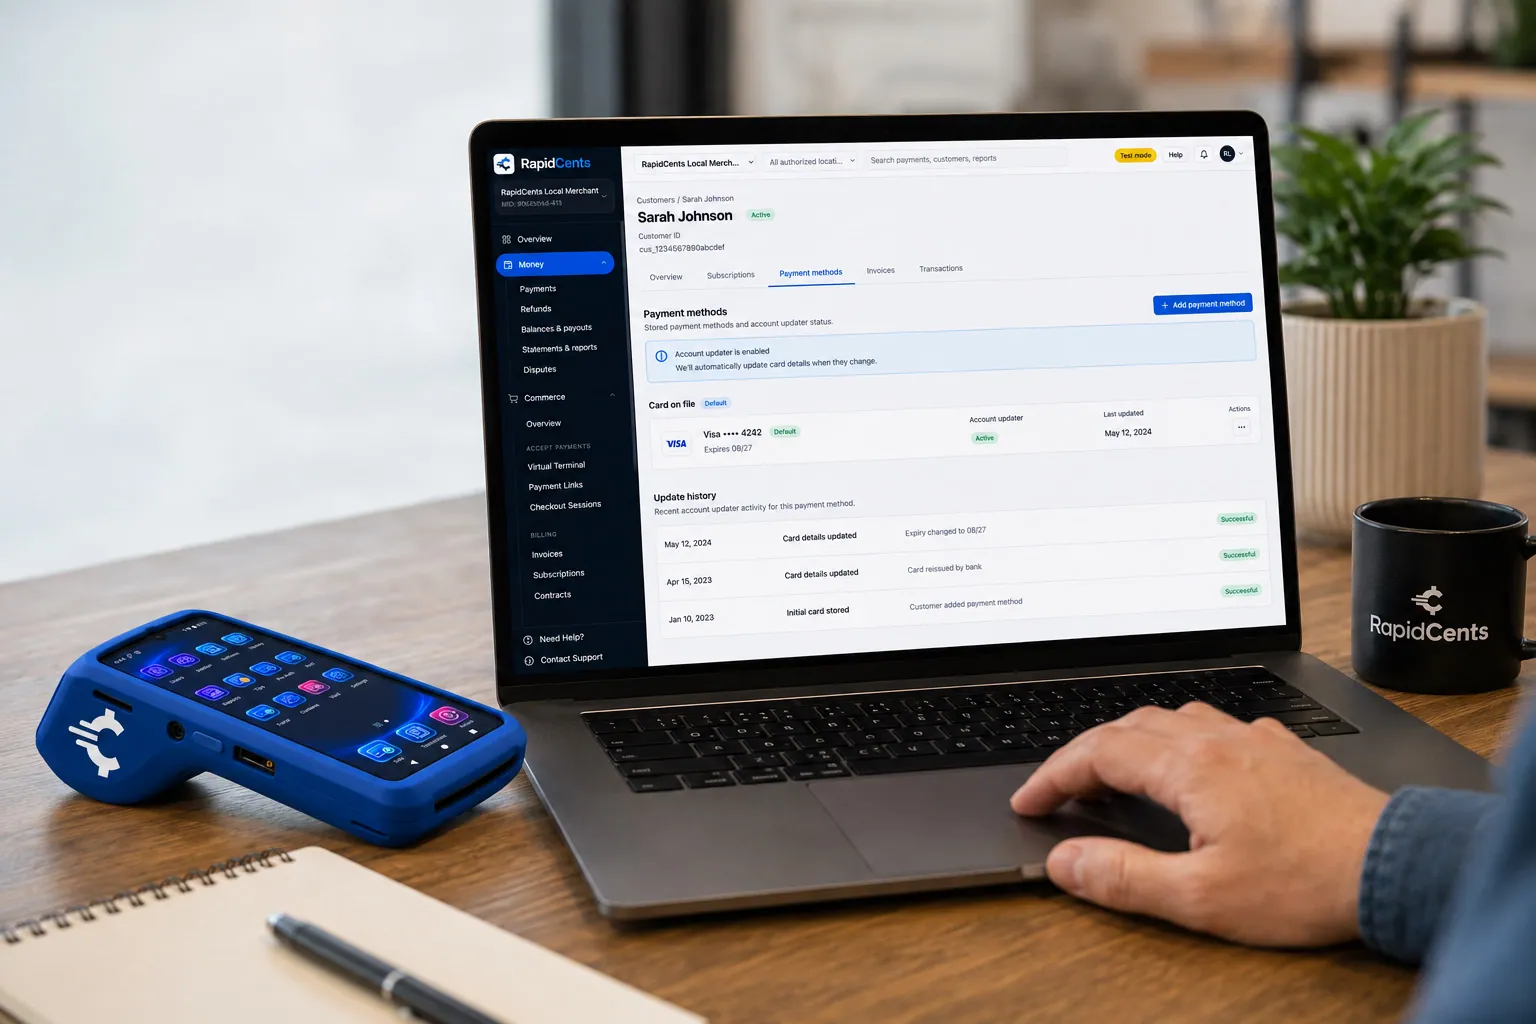
RapidCents refreshes a stored card after a reissue, so the vaulted credential keeps working without asking the customer again. Account Updater
Cards expire, get reissued and get replaced after fraud. Account Updater refreshes stored credentials with…
Explore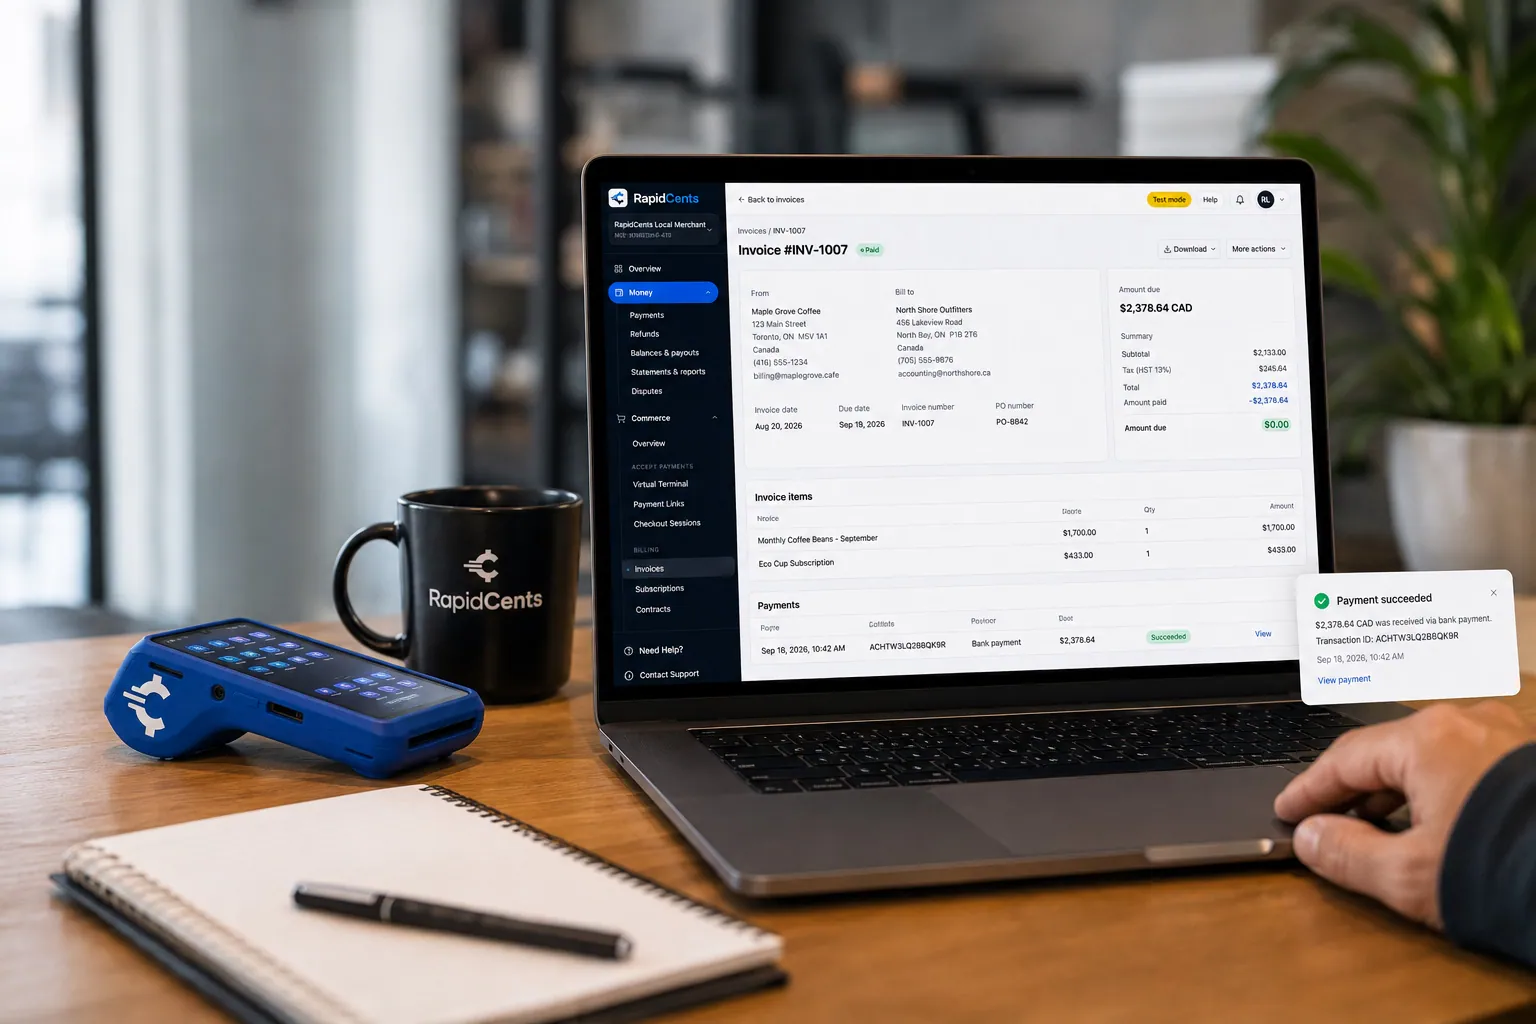
A merchant invoices a customer for bank debit through RapidCents, with card terminal capture available on the same desk. ACH / Bank Payments
Bank payments suit recurring and high-value invoices where card fees are the wrong tool. Collect directly…
Explore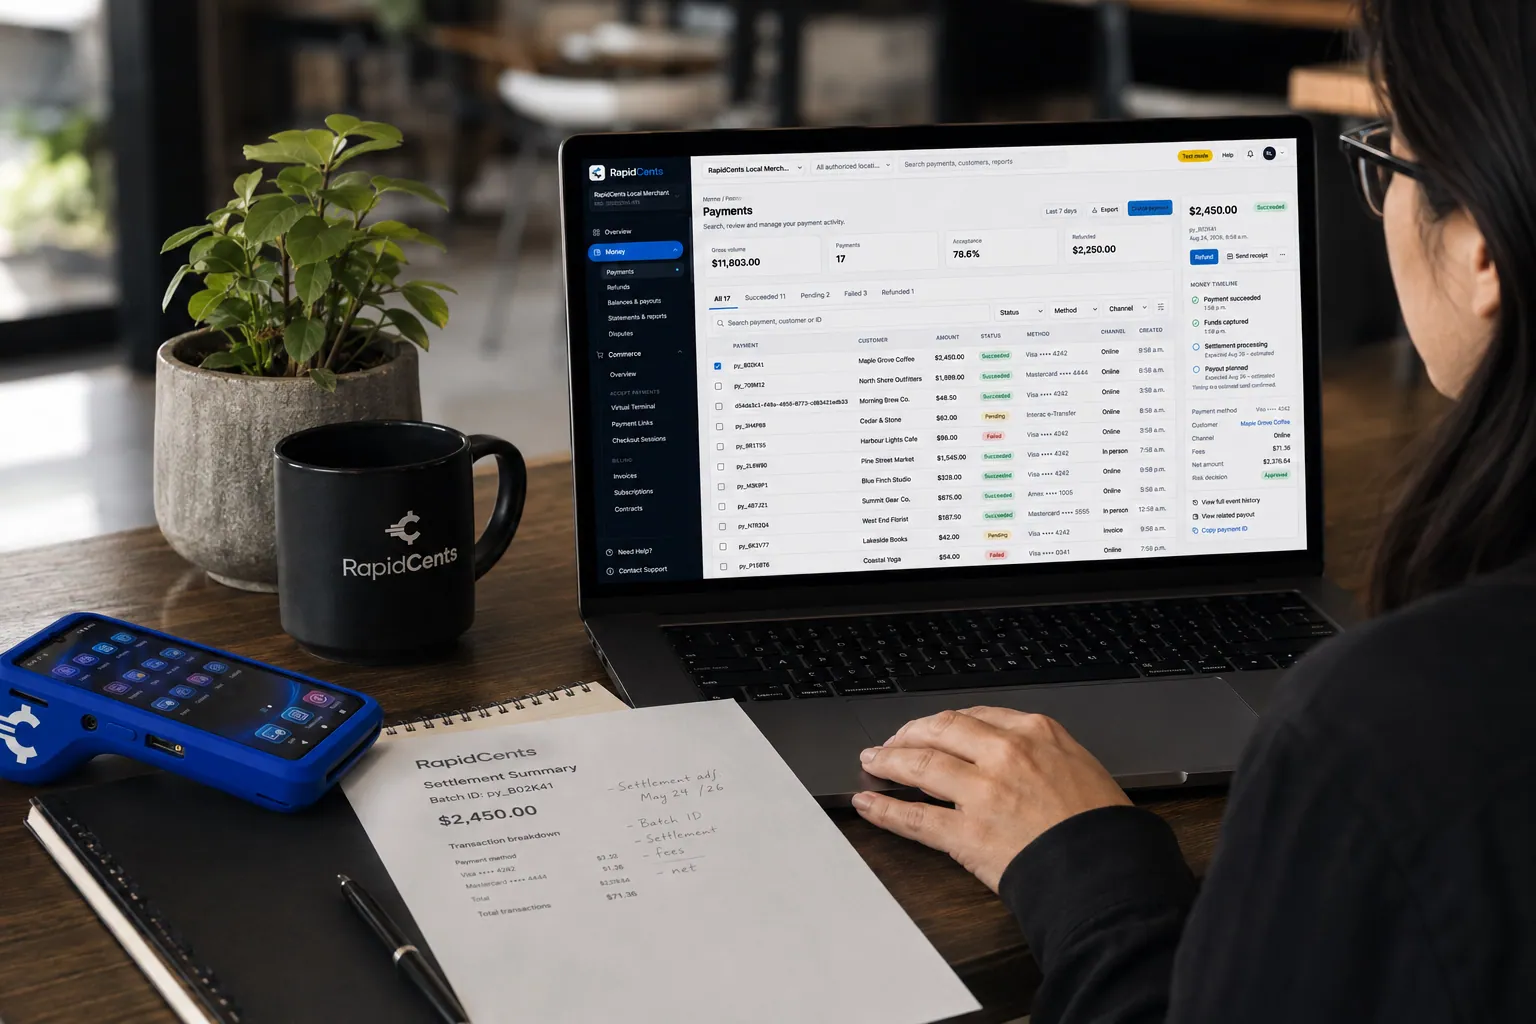
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF export…
Explore


How this gets set up
Subscriber signed onto a monthly monitoring charge
The installation ends with the monitoring fee set up as a recurring charge, by card or bank debit, before the panel is armed for the first time.
Bank debit offered for long-term accounts
Subscribers who intend to stay for years are pointed to pre-authorised debit, which does not expire the way a card does.
Cards refreshed ahead of each monthly run
Account updater replaces reissued and expired cards before the cycle, because at a few dollars a month nobody phones in to update one.
Accounts that need a person, worked from a list
Reporting names the accounts that still need a follow-up and why, so effort goes where the account is still live but the card on file needs updating.
Integrations
Manitou
An account's monitoring status in Manitou stays tied to the subscriber whose monthly charge is actually clearing.
SedonaOffice
Recurring monitoring invoices in SedonaOffice close out as each cycle's charge settles, account by account.
QuickBooks
Monitoring revenue and installation charges post into QuickBooks as separate accounts rather than one monthly total.
Operations, security and going live
Involuntary churn measured, not guessed
Reporting separates accounts that cancelled from accounts that merely failed to charge, which is the difference between a retention problem and a card problem.
A small charge across a very large base
The monthly amount is small enough that a subscriber rarely notices a missed cycle, so the reporting has to surface it instead of the customer.
Card data out of the dealer's hands
Cards captured at installation are tokenized, so a technician or dealer signing up a subscriber is not carrying card details back to the office.
Base migrated in cycle batches
An existing subscriber base moves over in batches aligned to billing dates, so no account is double-charged during the transition.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Keep separate the equipment installation deposit, activation date, recurring monitoring fee and a later repair visit; explain which agreement authorizes each charge. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Alarm & Monitoring does not, by itself, prove delivery or win a dispute.
The problem and the limit
Address cancellation effective dates, changed service addresses and failed monitoring payments. Do not suggest that an account updater guarantees payment or determines whether monitoring continues. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Alarm & Monitoring does not, by itself, prove delivery or win a dispute.
What to confirm
Ask for a redacted subscriber account showing installation completion, billing start, a declined cycle and an approved cancellation, with clear responsibility for customer follow-up. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Alarm & Monitoring does not, by itself, prove delivery or win a dispute.
Payment questions from Alarm & Monitoring
What should businesses compare when choosing alarm monitoring payment processing for Alarm & Monitoring?
Compare alarm monitoring payment processing against the real payment journey: sign-up, scheduled billing, and renewal, online checkout and remote payment, and the sale and reconciliation with business systems. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Alarm & Monitoring?
If Alarm & Monitoring sells primarily online, do not choose physical hardware before validating checkout. Add hardware only for a clearly defined in-person payment need.
Which payment channels are relevant for Alarm & Monitoring?
For Alarm & Monitoring, start with sign-up, scheduled billing, and renewal, online checkout and remote payment, and the sale and reconciliation with business systems. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Alarm & Monitoring?
For Alarm & Monitoring, compare costs related to scheduled billing, declined cards, and cancellations and online checkout and dispute handling using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Alarm & Monitoring?
For Alarm & Monitoring, document how payment data moves into business systems and the checkout, confirmation, and refund path, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
When should monitoring billing start after installation?
For a business in the USA, use the billing-start event stated in the monitoring agreement, such as confirmed activation, and record that date separately from installation payment. In practice, any agreed partial period and verify how the billing system receives activation status before claiming automatic scheduling. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What happens to a monitoring bill when a card payment fails?
For a business in the USA, keep the failed amount outstanding, review the reported payment status and contact the authorized subscriber through the approved process. Offer a supported update or retry route and reconcile any later success. Service continuation or suspension follows the monitoring agreement, not an assumed payment-platform rule. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can installation and monitoring charges be kept separate on one account?
For a business in the USA, itemize equipment, installation, activation and ongoing monitoring with their own dates and references. Apply an installation deposit to that work and start recurring charges under the monitoring authorization; confirm whether the customer record and invoices can display both without merging their balances. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Chambers of Commerce
Chambers bill annual and monthly memberships alongside event tickets, sponsorship…
Professional Associations
Professional bodies collect annual member dues, certification and exam fees…
Labour Unions
Unions collect dues by payroll deduction or card, plus initiation fees, benefit…
Coworking Spaces
Coworking operators run monthly desk and office memberships alongside day passes…
Subscription Boxes
Subscription box brands bill a recurring plan against a fixed ship date. RapidCents runs…
Religious Organizations
Congregations take one-time and recurring giving, building-fund pledges, hall rentals and…
Sports Leagues & Clubs
Leagues and clubs collect seasonal registration, team fees, tournament entries and…
Summer Camps
Camps take a deposit at booking then instalments before the session starts, plus canteen…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



