


High-ticket payments and layaway for jewellery stores
Jewelry Stores is for businesses in the USA. Compare payment options for custom-work deposits, layaway and collection balances; understand timing, payer authorization, exceptions and reconciliation for jewelry stores. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
Piece selected or a custom design quoted
Deposit taken to start the bench work
Layaway instalments recorded against the item
Balance settled when the piece is collected
Payment challenges
One sale that looks like fraud
A single high-value card purchase from an unfamiliar buyer triggers review, and the counter has to decide there and then whether to release the piece.
Layaway that runs for months
Instalments toward one ring accumulate over a long period, and every payment has to stay tied to the item held in the safe.
Custom work that cannot be resold
An engraved or resized piece fits one customer, so a failed deposit leaves the bench time and the metal unrecoverable.
Choose the right payment setup for Jewellery Stores
Choose jewelry store payment processing
For Jewellery Stores, map the deposit, staged payments, and final balance, online checkout and remote payment, and the counter or service point before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Jewellery Stores
For Jewellery Stores, start with the place customers pay in person: a countertop terminal, smart terminal, or portable device depending on the workflow. Verify that the hardware fits the real volume and workspace.
Compare payment processing fees
For Jewellery Stores, request a written fee breakdown covering deposits and final balances and online checkout and dispute handling. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Jewellery Stores payments
To set up Jewellery Stores payments, document the checkout, confirmation, and refund path, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
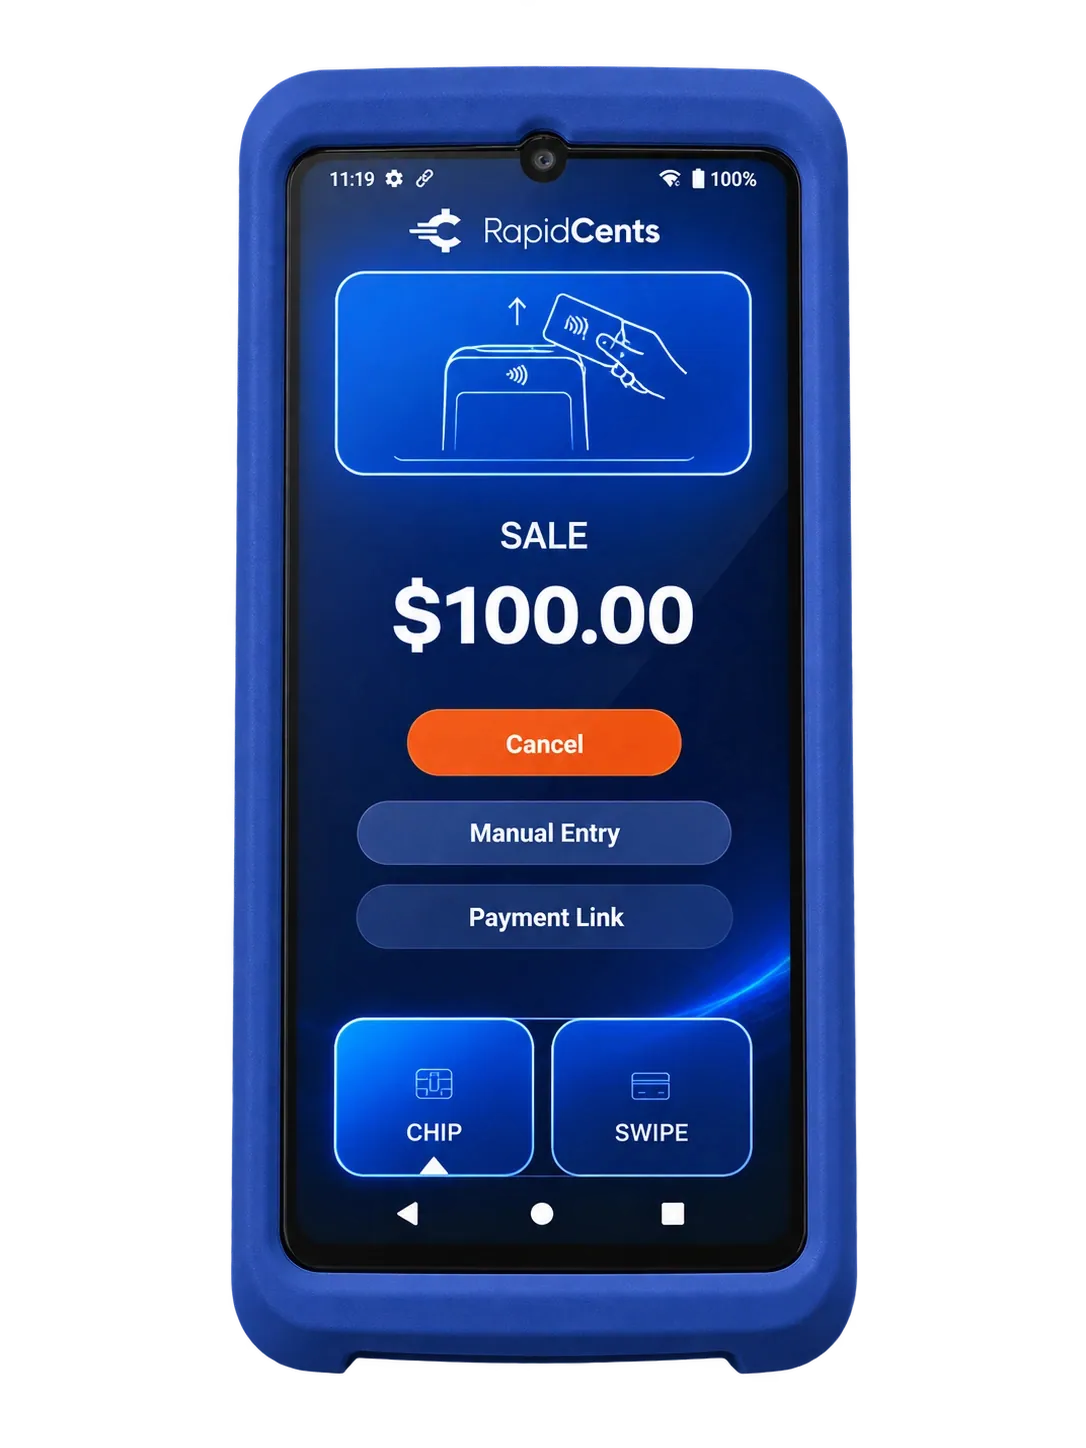
The RapidCents Rivo Go standing upright in its blue silicone case, showing the full-touch sale screen a customer reads across the counter. Payment Terminals
RapidCents payment terminals cover countertop, mobile and smart form factors so you can accept chip…
Explore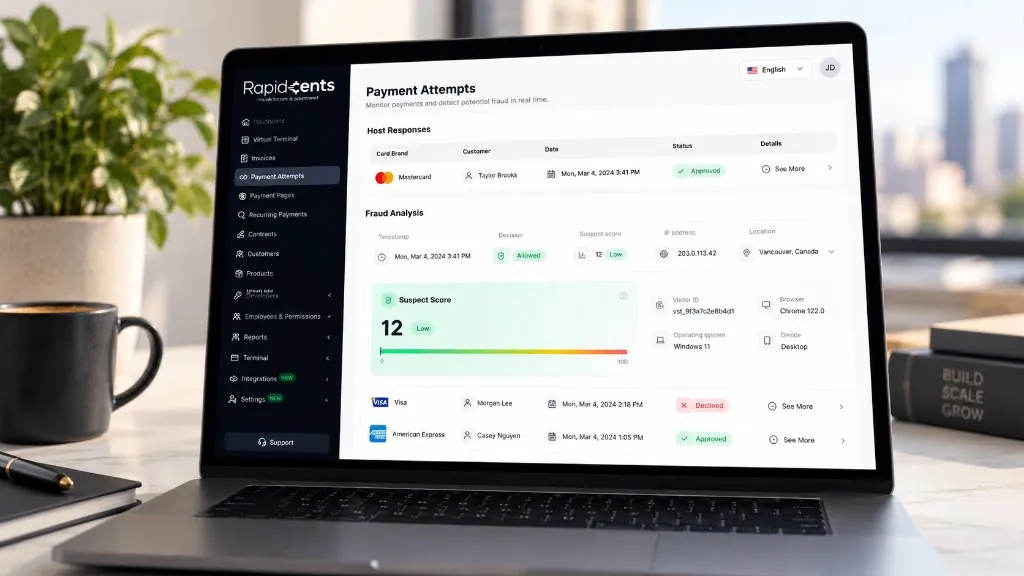
The Payment Attempts screen, shown with sample data: the host response for each attempt, then the fraud analysis behind it — decision, suspect score out of 100, IP address and location, visitor ID, browser, operating system and device. Fraud Prevention
RapidCents checks more than 180 signals on every payment attempt in under a second — the device, IP address…
Explore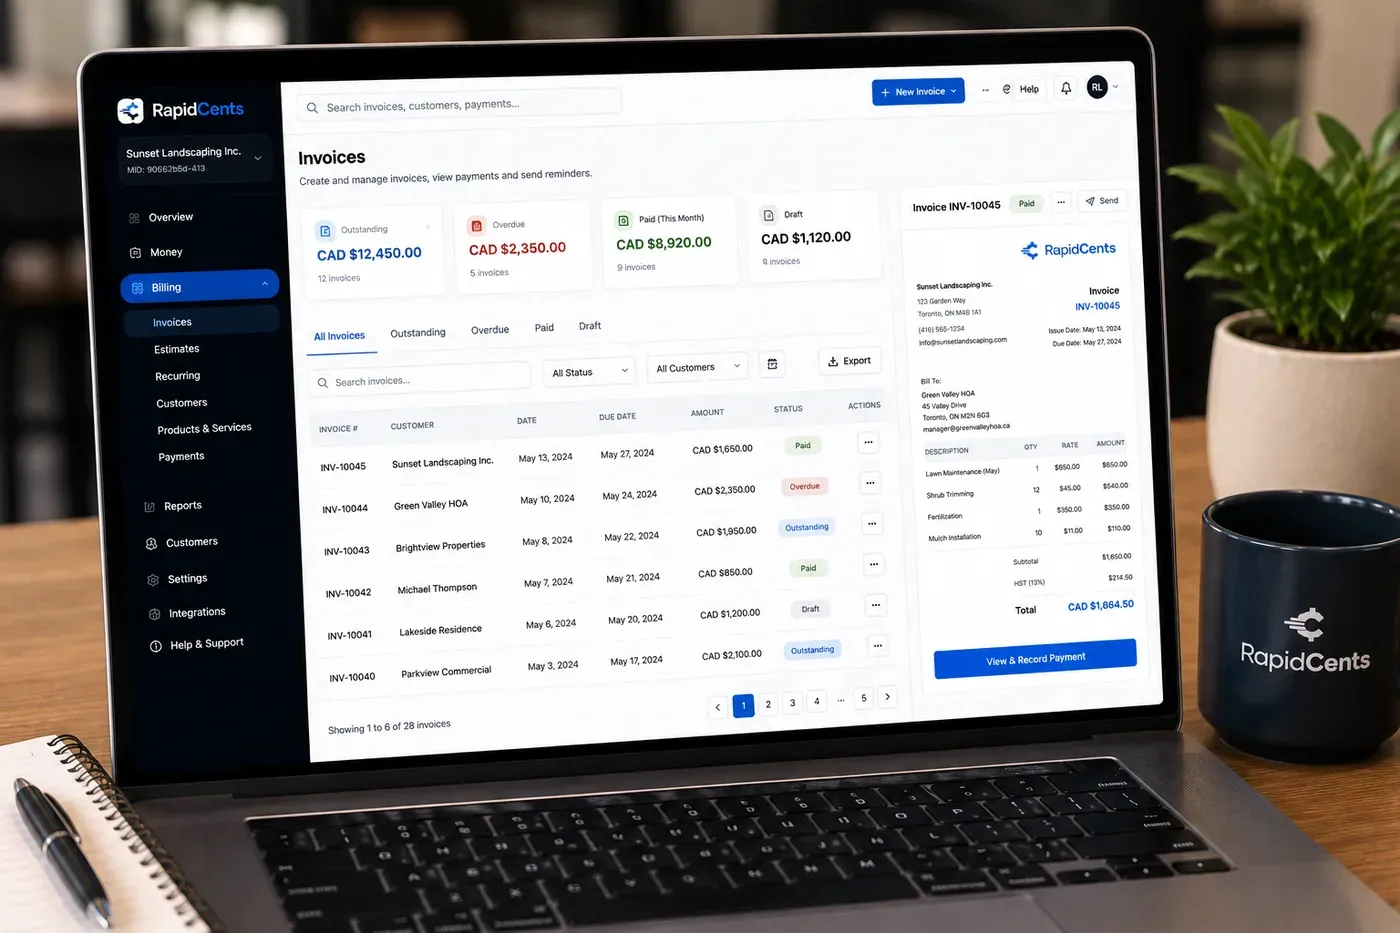
The RapidCents invoices screen: outstanding, overdue, paid and draft totals across the top, the invoice list below them, and a preview of one invoice on the right with its line items and a View & Record Payment button. Invoicing
RapidCents invoicing helps professional services, contractors and B2B suppliers create branded invoices…
Explore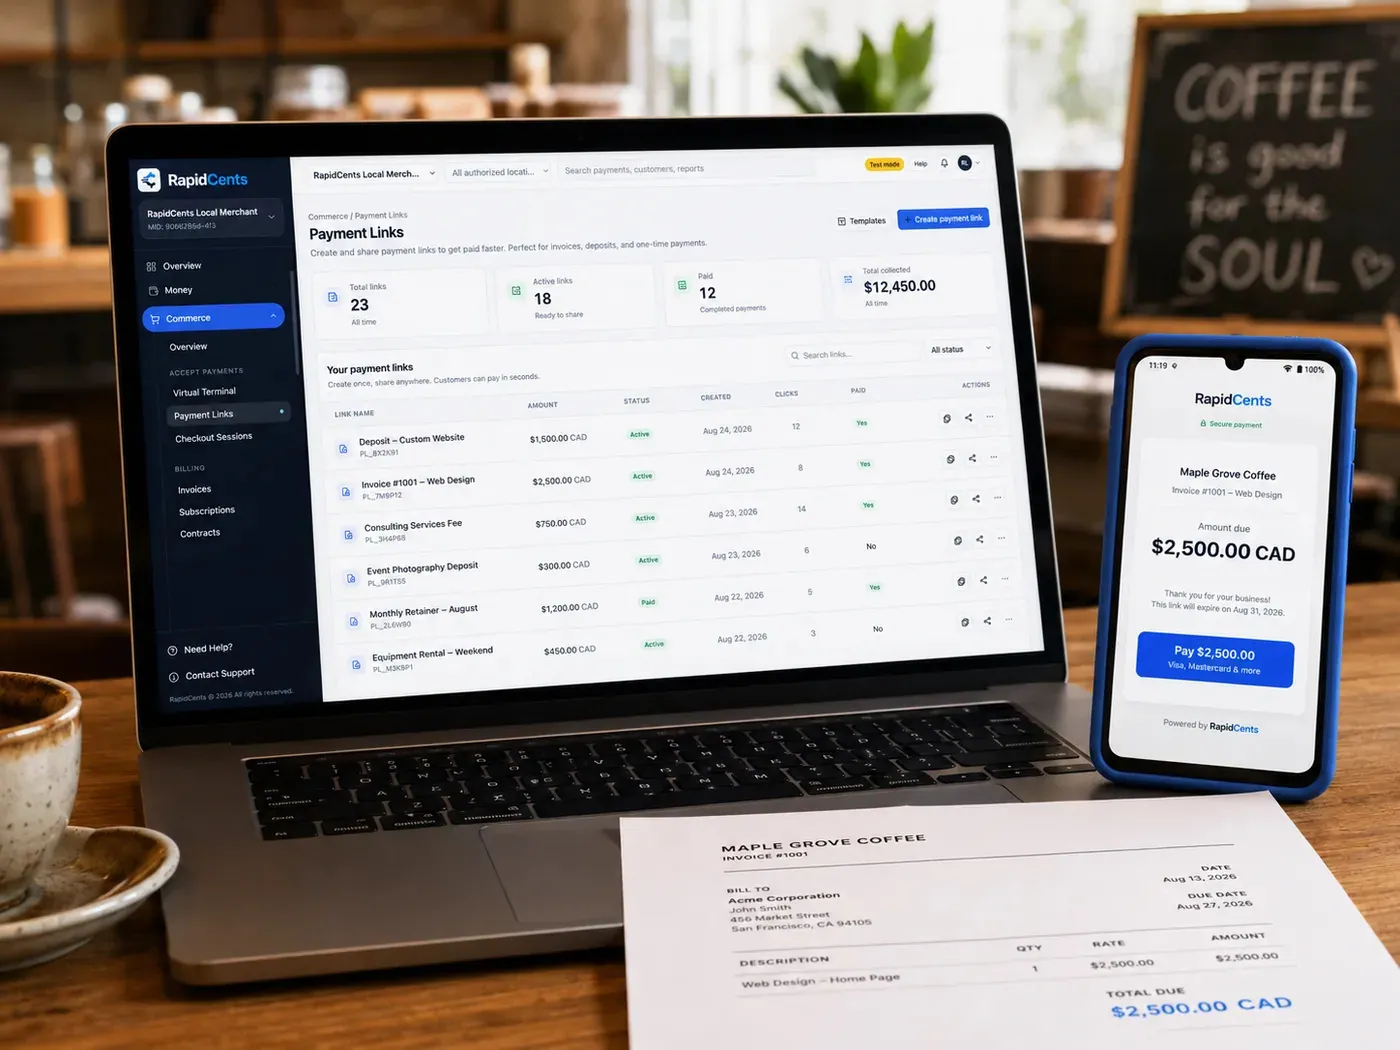
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore


How this gets set up
Custom piece quoted and deposited
A commission starts with a deposit on the counter terminal or a payment link, which is what buys the stone and books the bench time.
Layaway held on a schedule
Instalments are invoiced against the same piece, so the customer can see on one record what they have paid and what remains before pickup.
High-ticket card screened before the case opens
A five-figure card from a first-time customer runs through fraud tools before the piece leaves the display, not after it has walked out.
Balance and pickup
The final payment closes the order at the counter, and the invoice history is what the customer keeps for insurance and appraisal purposes.
Integrations
Lightspeed Retail
Lightspeed Retail holds the piece, its serial and the customer, so a deposit and a balance post against the item in the case rather than a line called ring.
The Edge exports
The Edge exports carry jewellery inventory, repair and layaway detail out as a file for matching against settlement, rather than posting payments back into it live.
Shopify
Shopify runs the online store, and taking its payments on your own merchant account means a high-ticket web order is screened by the same fraud rules as the counter.
Operations, security and going live
One sale, three payments, one record
Reporting ties deposit, instalments and balance to a single order, so a piece on layaway for eight months never looks like three unrelated sales.
Dispute exposure sized to the item
A single high-value piece attracts both real fraud and friendly chargebacks, so chargeback protection plus a documented pickup is what a jeweller has to be able to produce months later.
Layaway cards held as tokens
An instalment plan means holding a card for months, and keeping it as a vault token rather than as an imprint in a ledger under the counter is what keeps that exposure narrow.
Live before the fourth quarter
Terminals, the layaway invoice template and the fraud rules are set before the engagement and holiday season, with the rules tuned on a few real high-ticket sales first.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Follow a selected item or custom design through bench-work deposit, agreed layaway installments and final collection; keep every payment associated with the specific piece. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Jewelry Stores does not, by itself, prove delivery or win a dispute.
The problem and the limit
Cover an amended design, delayed collection and a high-value authorization review. An appraisal or signed pickup alone does not guarantee approval or eliminate an unauthorized-payment dispute. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Jewelry Stores does not, by itself, prove delivery or win a dispute.
What to confirm
Ask for a redacted item ledger with design approval, deposit, layaway schedule and collection acknowledgment; demonstrate refund handling and confirm transaction limits before promising high-ticket acceptance. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Jewelry Stores does not, by itself, prove delivery or win a dispute.
Payment questions from Jewellery Stores
What should businesses compare when choosing jewelry store payment processing for Jewellery Stores?
Compare jewelry store payment processing against the real payment journey: the deposit, staged payments, and final balance, online checkout and remote payment, and the counter or service point. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Jewellery Stores?
If Jewellery Stores sells primarily online, do not choose physical hardware before validating checkout. Add hardware only for a clearly defined in-person payment need.
Which payment channels are relevant for Jewellery Stores?
For Jewellery Stores, start with the deposit, staged payments, and final balance, online checkout and remote payment, and the counter or service point. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Jewellery Stores?
For Jewellery Stores, compare costs related to deposits and final balances and online checkout and dispute handling using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Jewellery Stores?
For Jewellery Stores, document the checkout, confirmation, and refund path, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
How should jewelry layaway payments stay linked to the item?
For a business in the USA, assign the specific item or custom-order reference to each installment, show the agreed price and schedule, and reduce the outstanding amount after confirmed payments. Keep the held inventory and payment ledger aligned; verify any layaway integration and avoid implying approval for unlimited card collection. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What records support a custom-design deposit and final collection?
For a business in the USA, retain the accepted design or specification, price, deposit authorization, approved changes and final collection acknowledgment with the order. Cover how previous payments reduce the balance; these records support reconciliation and dispute review without guaranteeing authorization or eliminating chargeback risk. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should a canceled jewelry layaway be refunded?
For a business in the USA, review the accepted layaway terms, payments received and any approved charges, then explain the agreed refundable or credited amount. Allocate refunds to the original payments using the supported process and update the item reservation; do not assume every layaway deposit is forfeited. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Retail
Retailers use countertop terminals, e-commerce checkout, returns and inventory-linked…
Convenience Stores
C-stores need fast EMV contactless, lottery and fuel integrations with reliable…
Grocery
Grocers and markets accept EBT where supported, contactless lanes and online pickup…
Liquor Stores
Liquor retailers comply with state rules while accepting countertop and mobile…
Furniture Stores
Furniture retailers take a deposit at order and the balance on delivery weeks later, and…
Sporting Goods
Sporting goods stores swing hard by season, run a service counter for tuning and fitting…
Garden Centres & Nurseries
Garden centres compress most of the year into spring, add mobile checkout out in the…
Auto Parts Retailers
Parts counters serve retail walk-ins and trade accounts on terms, so the same store needs…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



