


POS and Payment Terminals for Liquor and Wine Retailers
Liquor Stores is for businesses in the USA. Choose retail payment terminals and reconciliation workflows for licensed alcohol retail operations. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
ID checked before the sale is rung
Tap, chip or PIN debit taken at the till
Curbside or delivery order paid by payment link
Sale attributed to a store and a shift
Payment challenges
The age check comes before the card does
Payment cannot begin until the ID clears, so the terminal waits on the clerk rather than the other way round.
Delivery hands the bottle to someone else
An order paid online can be received by a person other than the cardholder, which is where disputes begin.
Records that have to survive a state audit
An itemized sale has to stay tied to the transaction that paid for it and the deposit it settled into.
Choose the right payment setup for Liquor Stores
Choose liquor store payment terminal
For Liquor Stores, map the counter or service point and each location and consolidated oversight before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Liquor Stores
For Liquor Stores, start with the place customers pay in person: a countertop terminal, smart terminal, or portable device depending on the workflow. Verify that the hardware fits the real volume and workspace.
Compare payment processing fees
For Liquor Stores, request a written fee breakdown covering cost detail by device and location. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Liquor Stores payments
To set up Liquor Stores payments, document the real payment journey, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
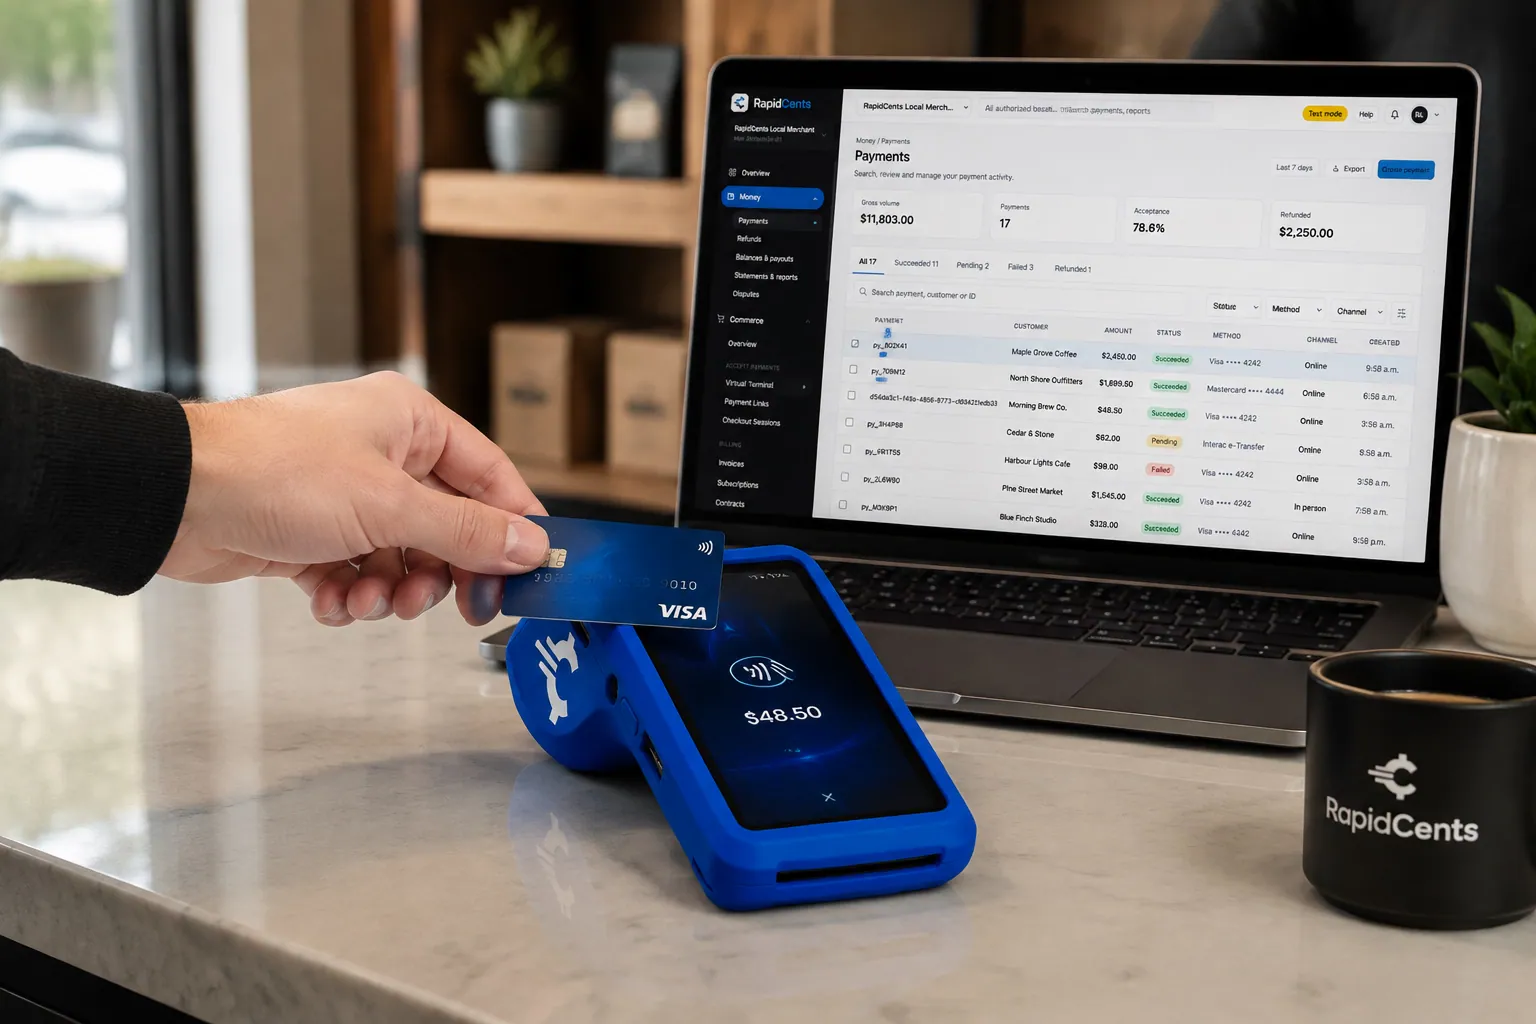
A fixed RapidCents countertop terminal taking card payments at the till, with settlement visible on the dashboard. Countertop Terminals
RapidCents countertop terminals sit at retail counters, restaurant hosts and reception desks where speed and…
Explore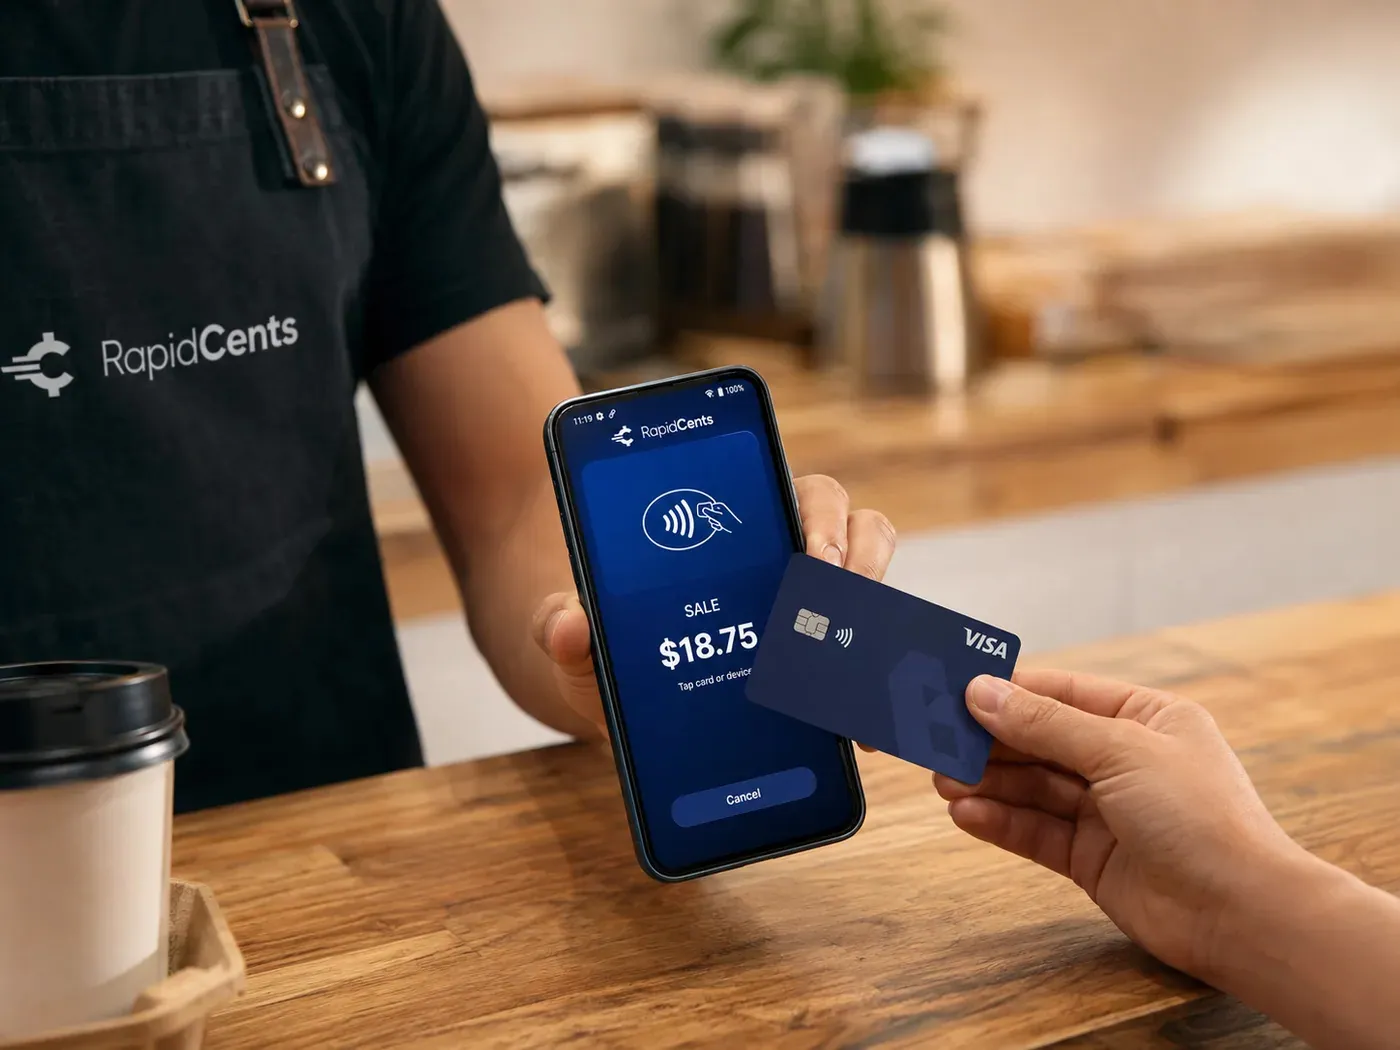
A café worker holds a phone running RapidCents Tap to Pay, showing an $18.75 sale and the contactless symbol, while a customer holds a Visa card to the screen. No separate card reader is present. Tap to Pay
RapidCents Tap to Pay turns supported iPhones and Android devices into contactless payment terminals without…
Explore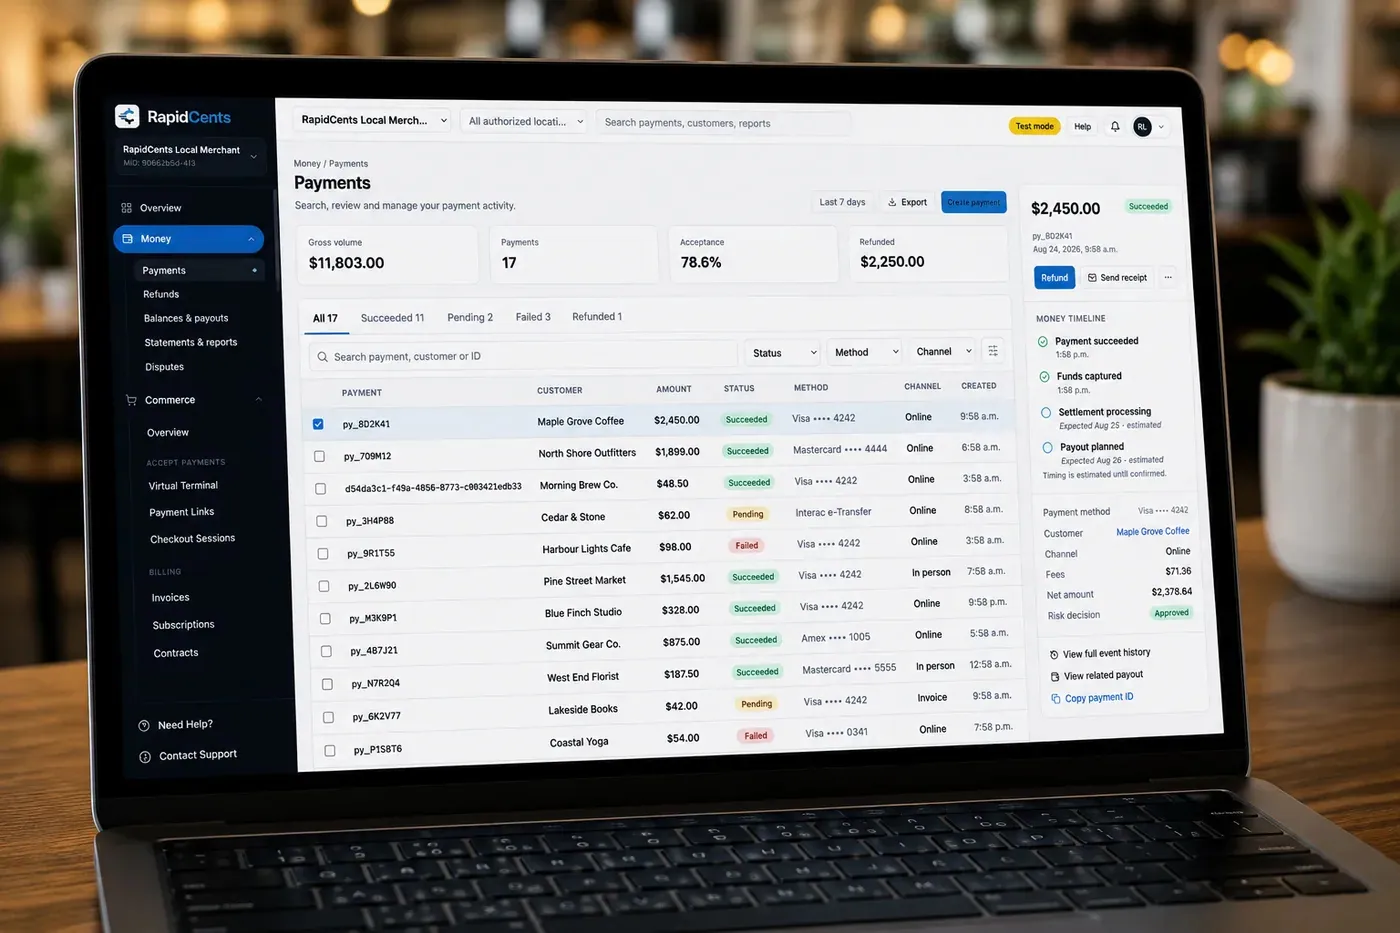
The RapidCents payments screen: gross volume, payment count, acceptance rate and refunds across the top, a filterable transaction list below, and a money timeline on the right tracing one payment from capture to planned payout. Merchant Dashboard
The RapidCents merchant dashboard gives owners, managers and finance staff a single signed-in view of live…
Explore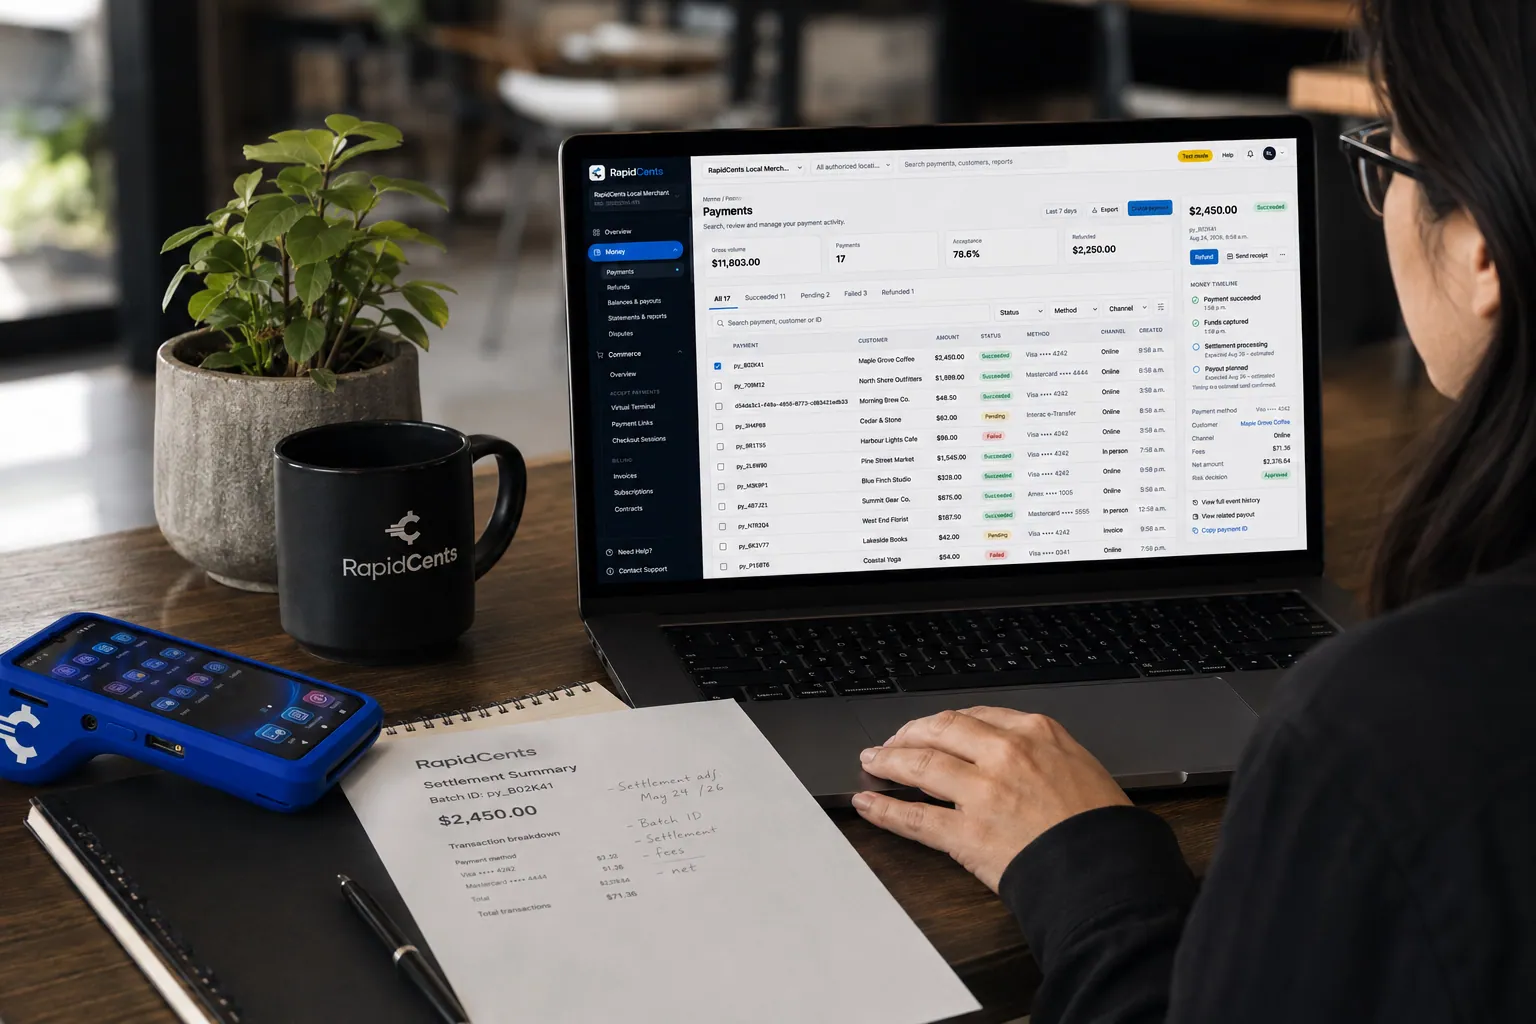
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF export…
Explore


How this gets set up
ID first, card second
The terminal sits where the clerk checks age before the card is presented, so the check is never rushed by a waiting payment.
An itemized receipt on every sale
Countertop terminals print a receipt tied to the sale, so the store keeps a per-transaction record of what left the shelf.
Curbside and delivery orders
Tap to Pay takes the card at the car or the door, at handover rather than at ordering.
Attribution by store and shift
Every sale stays attached to a location and a shift, which is what an operator with more than one storefront needs.
Integrations
Liquor POS
Liquor POS rings the bottle and the size, so the card total matches an itemized sale instead of an amount keyed from memory.
Lightspeed
Lightspeed holds the shelf count, so a card sale at the till moves the inventory it actually sold.
Operations, security and going live
Records that answer a question months later
Because a liquor retailer operates under state rules, its own records do the answering, so reporting keeps each sale attached to a store and a shift.
Returns credited to the original card
A return goes back to the card that paid, so the reversal is recorded against the sale it undoes rather than as an unattached cash-out.
Less cash in the safe at close
A higher card share reduces the float held by a store that closes late with high-value stock on the shelf.
Terminal changes outside peak hours
The counter cannot go dark on a Friday, so terminals are staged and tested before the busiest trade.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Follow a basket from the retail register to card payment and itemized receipt. Keep separate payment authorization from the store’s age-verification and product-sale responsibilities. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Liquor Stores does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers controlled refunds, duplicate-payment checks and end-of-shift balancing. Cover which evidence belongs in the POS and which details the payment dashboard actually retains. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Liquor Stores does not, by itself, prove delivery or win a dispute.
What to confirm
Use a U.S. Store example with a USD total and separately identified taxes. Before you rely on this, confirm merchant eligibility, register compatibility and device configuration before discussing delivery or remote sales. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Liquor Stores does not, by itself, prove delivery or win a dispute.
Payment questions from Liquor Stores
What should businesses compare when choosing liquor store payment terminal for Liquor Stores?
Compare liquor store payment terminal against the real payment journey: the counter or service point and each location and consolidated oversight. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Liquor Stores?
For Liquor Stores, start with the workstation where customers pay and the space available. A test of the real flow reveals the right form factor better than a feature comparison alone.
Which payment channels are relevant for Liquor Stores?
For Liquor Stores, start with the counter or service point and each location and consolidated oversight. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Liquor Stores?
For Liquor Stores, compare costs related to cost detail by device and location using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Liquor Stores?
For Liquor Stores, document the real payment journey, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
Does payment approval verify that an alcohol sale is permitted?
For a business in the USA, no; explain that authorization is a payment result and the merchant retains its applicable eligibility and sale checks. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How do staff reconcile terminal totals with liquor-store register totals?
For a business in the USA, specify the verified connection or reconciliation export and explain how voids and refunds appear. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Retail
Retailers use countertop terminals, e-commerce checkout, returns and inventory-linked…
Convenience Stores
C-stores need fast EMV contactless, lottery and fuel integrations with reliable…
Grocery
Grocers and markets accept EBT where supported, contactless lanes and online pickup…
Jewellery Stores
Jewellers sell high-value single items, hold custom orders on deposit and offer layaway…
Furniture Stores
Furniture retailers take a deposit at order and the balance on delivery weeks later, and…
Sporting Goods
Sporting goods stores swing hard by season, run a service counter for tuning and fitting…
Garden Centres & Nurseries
Garden centres compress most of the year into spring, add mobile checkout out in the…
Auto Parts Retailers
Parts counters serve retail walk-ins and trade accounts on terms, so the same store needs…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



