


Payment Processing for Real Estate Brokerages and Agents
Real Estate is for businesses in the USA. Identify approved brokerage service collections without implying support for earnest money, escrow or closing disbursements. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
Application fee paid online before the showing
Holding deposit keyed on the virtual terminal
Lease or offer deposit collected by payment link
Commission invoice settled at hosted checkout
Payment challenges
Money collected far from any desk
An agent takes a holding deposit at an open house with no terminal on hand and no office to return to that evening.
Refunding a deal that falls through
A conditional offer collapses and the deposit has to go back to the same card, cleanly and on the record.
Attributing a payment to a listing
One card payment can cover an amount the brokerage holds and a fee an agent earned, so reporting has to show which deal and which agent it belongs to.
Choose the right payment setup for Real Estate
Choose real estate payment processing
For Real Estate, map the deposit, staged payments, and final balance, online checkout and remote payment, and the invoice, retainer, and remote client payment before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Real Estate
For Real Estate, physical hardware may be secondary to the checkout flow. Prioritize gateway or payment-page requirements first, then add a terminal only when an in-person payment point is genuinely needed.
Compare payment processing fees
For Real Estate, request a written fee breakdown covering deposits and final balances and online checkout and dispute handling. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Real Estate payments
To set up Real Estate payments, document the checkout, confirmation, and refund path, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
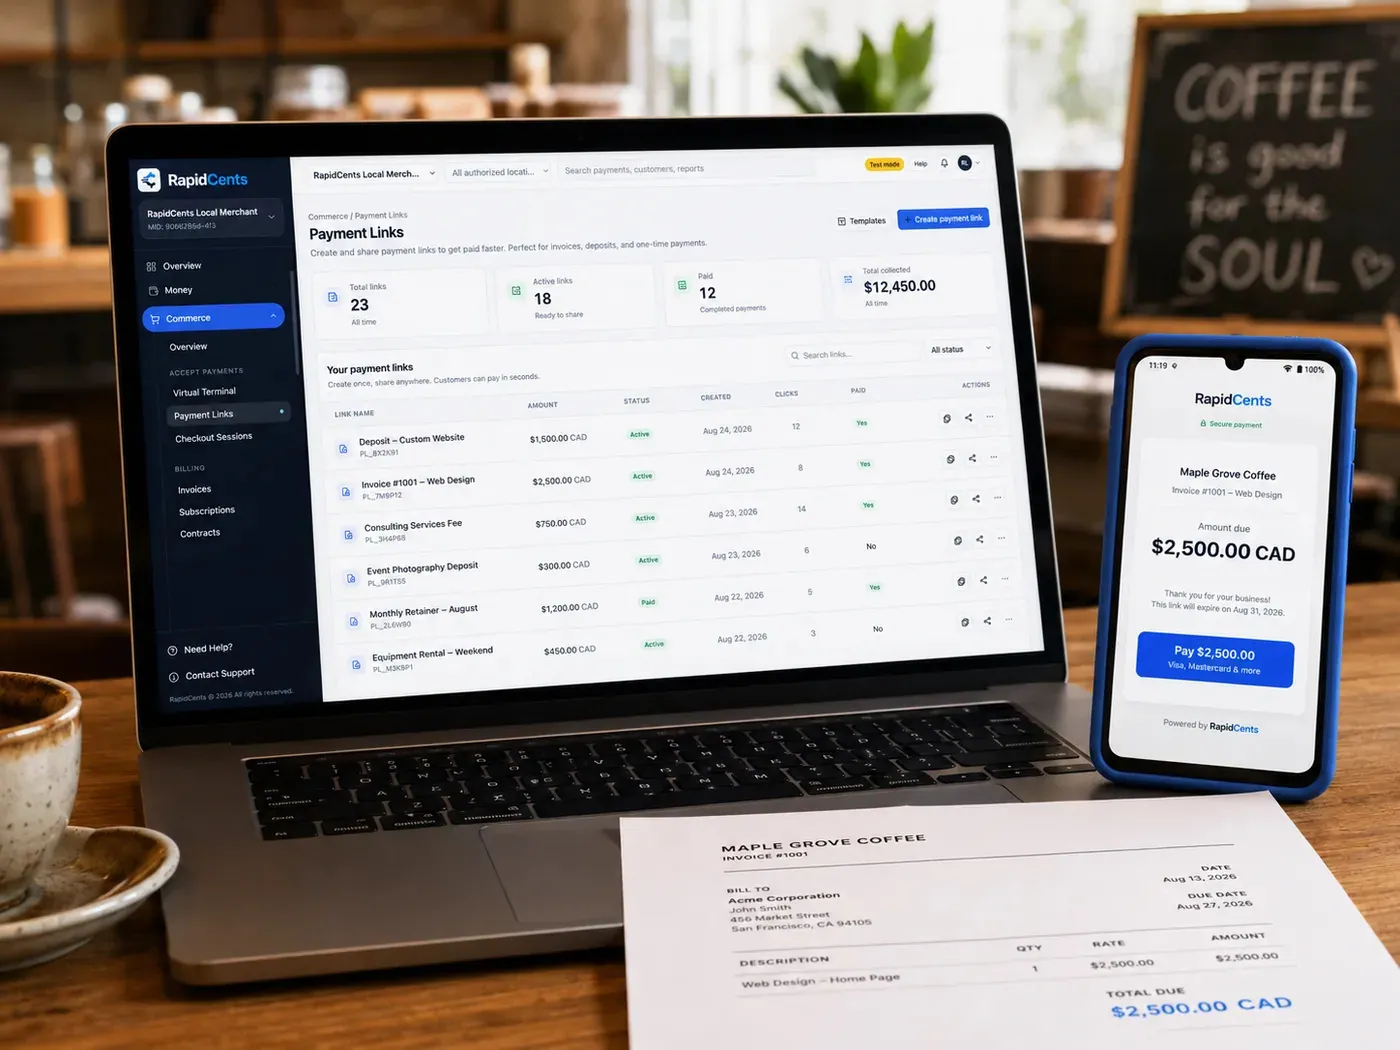
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore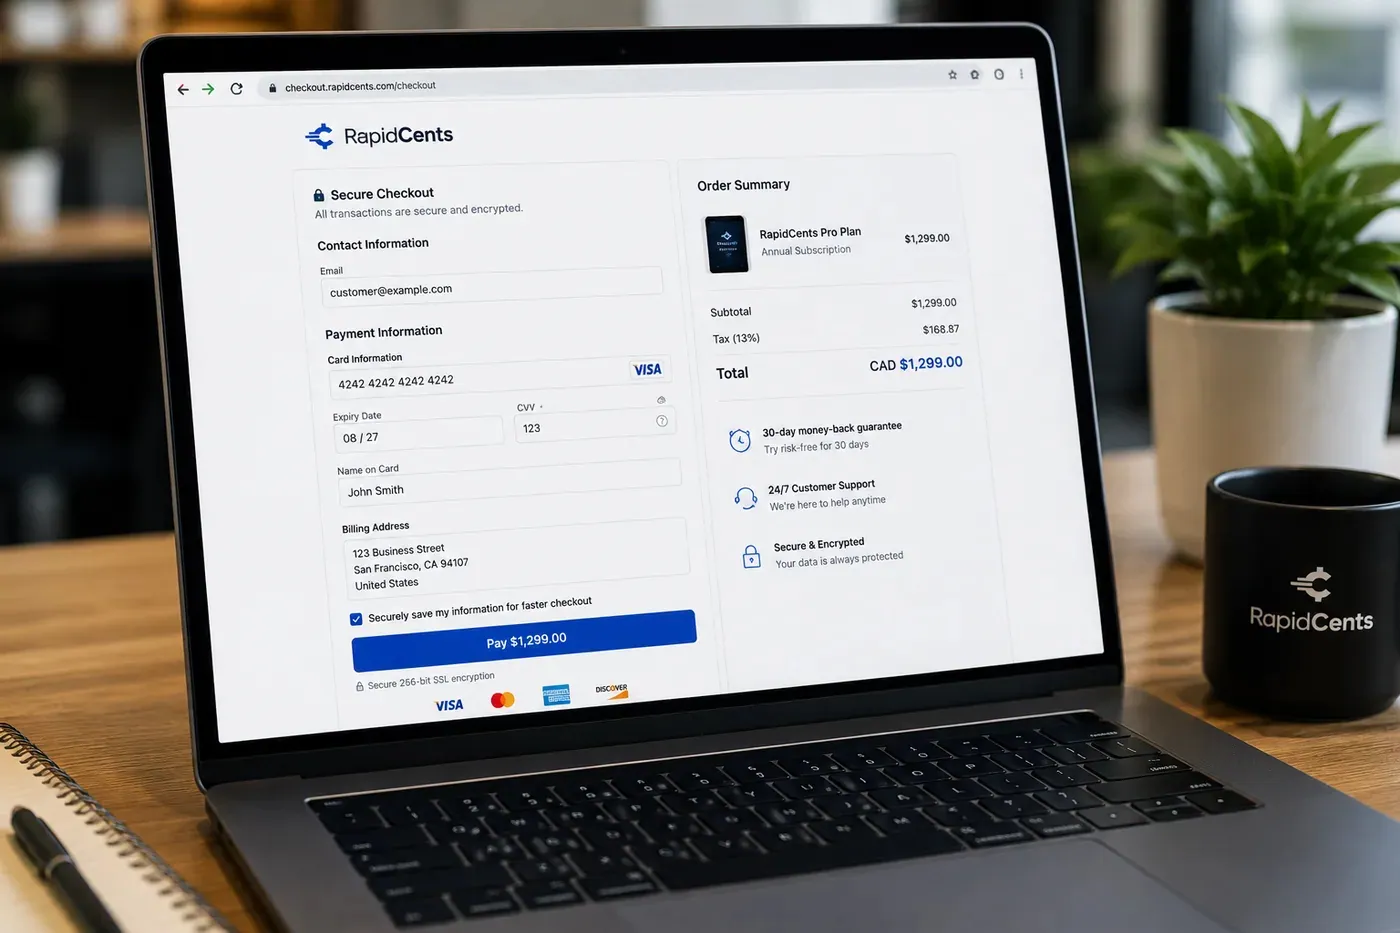
A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via iframe…
Explore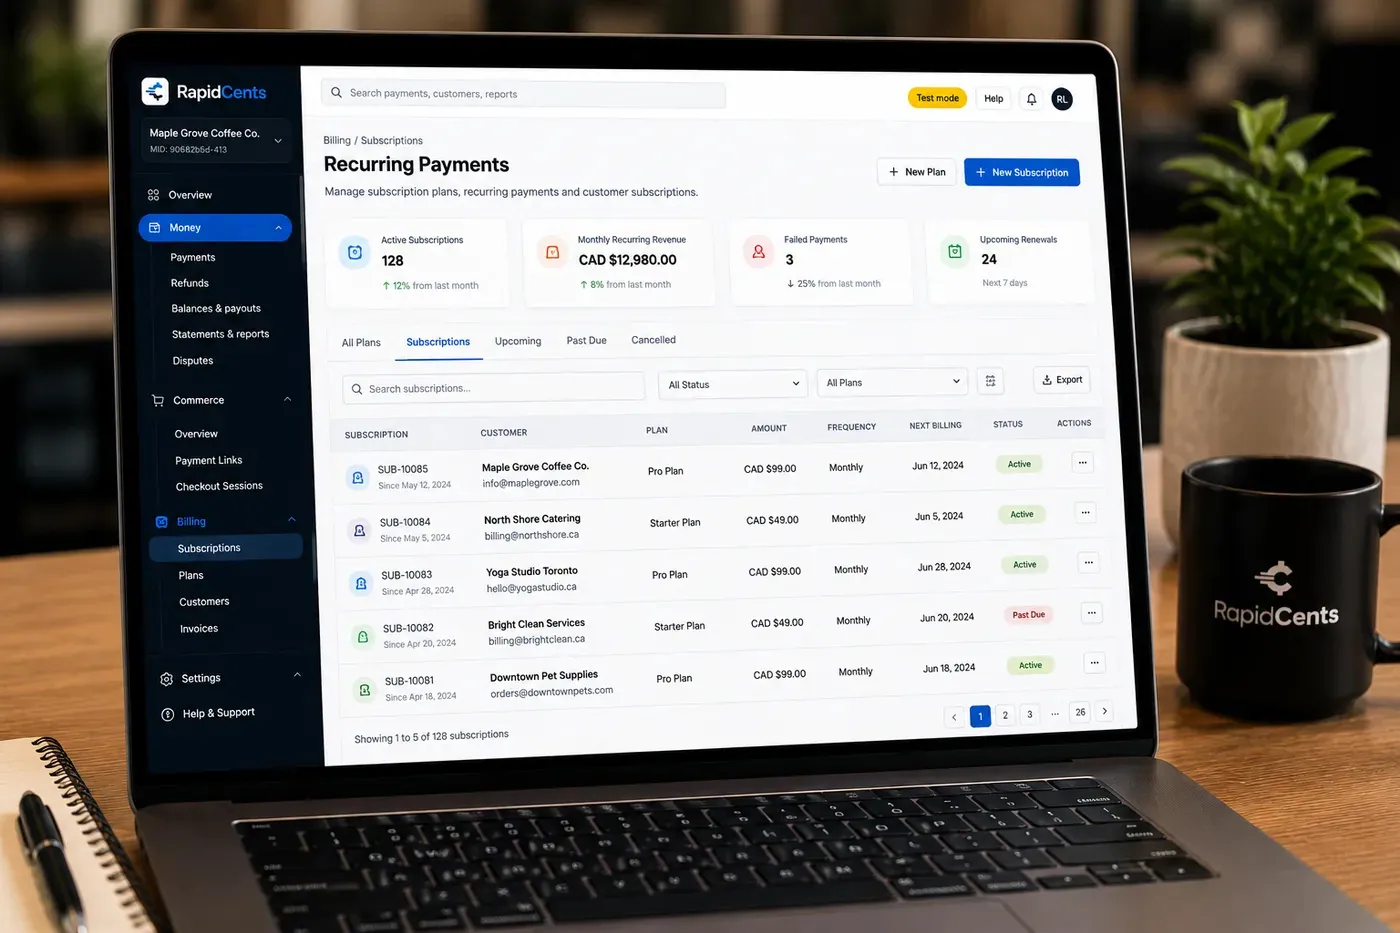
The RapidCents recurring payments screen showing active subscriptions, monthly recurring revenue, failed payments and upcoming renewals, above a list of subscriptions with their plan, amount, frequency and next billing date. Recurring Payments
RapidCents recurring payments manage subscription plans, membership renewals and installment schedules with…
Explore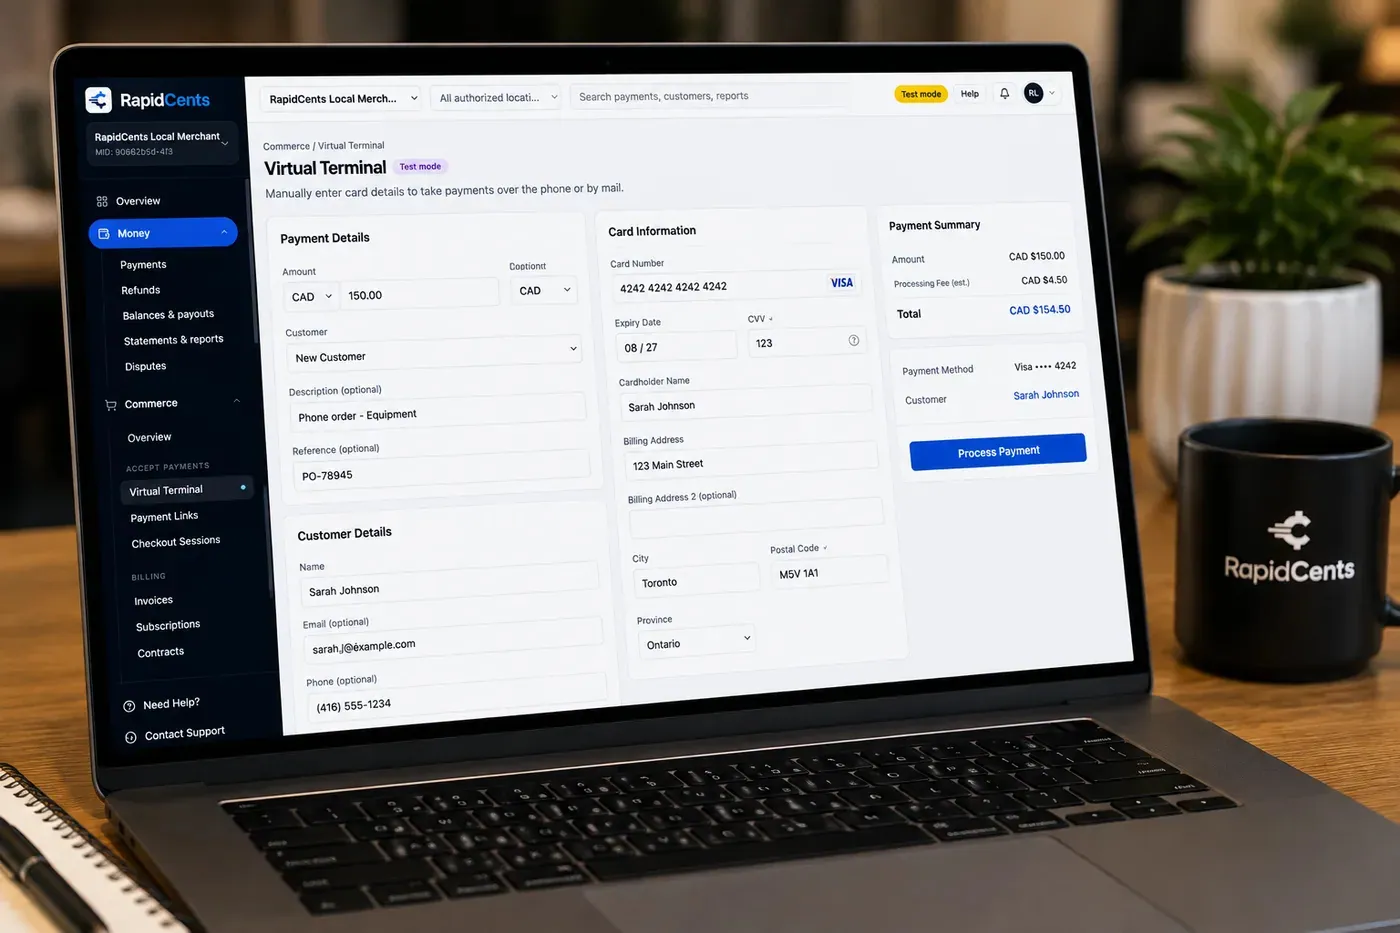
The RapidCents virtual terminal: payment details, card number, expiry and CVV keyed by hand on the left, with a payment summary on the right showing the amount, the estimated processing fee and a Process Payment button. Virtual Terminal
The RapidCents virtual terminal lets authorized staff enter mail-order and telephone-order payments through a…
Explore


How this gets set up
Application fee before the paperwork
A prospective tenant or buyer pays the application fee by payment link, so the file opens with the fee already cleared.
Deposit at signing
The holding deposit runs through hosted checkout on the listing site, or is keyed on the virtual terminal when the agent is out at the property.
Rent or commission on a set date
Once the lease is signed, rent moves to recurring payments and the brokerage invoices its commission on the closing date.
Every amount stays tied to the file
Reconciliation links a deposit back to the listing or lease it belongs to instead of an anonymous bank line.
Integrations
Buildium
Buildium tracks the unit, so a lease deposit or a rent payment posts against the property record instead of a bank line.
AppFolio exports
AppFolio exports move settlement detail into the property ledger as a file, not a live two-way sync.
Dotloop
Dotloop holds the signed paperwork, so the deposit that closed a loop stays attached to the documents that authorised it.
Operations, security and going live
Deposits never mixed with commission
Reporting keeps holding deposits and application fees distinguishable from brokerage commission, so an amount being held is not read as earned revenue.
Cards keyed on site, never written down
An agent taking a deposit at a property keys it into the virtual terminal there, so no card number travels back to the office on paper.
The usual dispute is an application fee
A fee charged for a deal that never closed is the most likely contested item, so the authorisation and receipt stay attached to the transaction.
Cut over between closings
The switch happens between transactions rather than mid-deal, so no deposit is in flight while the payment path changes.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Define the specific brokerage or property-service fee being collected and the responsible payer. Keep separate ordinary approved invoices from earnest money, escrow deposits and closing funds. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Real Estate does not, by itself, prove delivery or win a dispute.
The problem and the limit
In practice, client references, signed service scope and refund approval. Do not suggest that a successful payment completes a real-estate transaction or satisfies fiduciary account requirements. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Real Estate does not, by itself, prove delivery or win a dispute.
What to confirm
Use a U.S. Brokerage’s approved USD service invoice to explain reconciliation and account destinations. Have underwriting and counsel confirm the collection category before promoting any deposit or commission workflow. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Real Estate does not, by itself, prove delivery or win a dispute.
Payment questions from Real Estate
What should businesses compare when choosing real estate payment processing for Real Estate?
Compare real estate payment processing against the real payment journey: the deposit, staged payments, and final balance, online checkout and remote payment, and the invoice, retainer, and remote client payment. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Real Estate?
If Real Estate sells primarily online, do not choose physical hardware before validating checkout. Add hardware only for a clearly defined in-person payment need.
Which payment channels are relevant for Real Estate?
For Real Estate, start with the deposit, staged payments, and final balance, online checkout and remote payment, and the invoice, retainer, and remote client payment. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Real Estate?
For Real Estate, compare costs related to deposits and final balances and online checkout and dispute handling using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Real Estate?
For Real Estate, document the checkout, confirmation, and refund path, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
Can this service collect earnest money or closing funds?
For a business in the USA, answer only with explicit product, acquiring and legal approval; otherwise clearly limit the page to approved service invoices. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should a brokerage match a payment to the correct client engagement?
For a business in the USA, the practical view covers supported invoice and engagement references without placing sensitive transaction details into public payment messages. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can commission or referral payments be disbursed through this setup?
For a business in the USA, distinguish accepting a customer payment from paying third parties; do not imply disbursement or escrow capability. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Law Firms
Law firms collect retainers, trust-account coordination and client invoices with secure…
Accounting Firms
Accounting and bookkeeping firms bill recurring engagements, project milestones and…
Professional Services
Consultancies and agencies use invoicing, retainers, recurring billing and virtual…
B2B & Wholesale
Wholesale distributors accept large ticket B2B cards, invoicing and net-term payment…
Insurance
Insurance agencies collect premiums via payment links, recurring billing and virtual…
Property Management
Property managers run tenant rent portals, maintenance invoicing and HOA assessments with…
Freight & Logistics
Carriers and 3PLs invoice shippers, collect COD balances and manage fuel surcharge…
Marketing Agencies
Agencies bill monthly retainers plus project milestones and pass-through ad spend, so one…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



