


Launch secure online checkout without building payments from scratch
Accept payments online is for businesses in the USA. Evaluate accept payments online for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Counter businesses adding e-commerce
The card is no longer present, which changes interchange, fraud exposure and who carries liability on a disputed order.
Service businesses collecting deposits
A quote accepted online, a deposit collected before work starts, a balance taken later.
Teams choosing an integration path
Hosted, embedded or API: three different amounts of work, and three different compliance positions.
Common challenges
PCI scope follows the card data
A checkout that touches the card number puts your servers in scope. Hosted pages and embedded fields keep the entry surface on RapidCents, which is what keeps the assessment small.
Card-not-present disputes land on you
Without authentication, fraud liability for an online order generally sits with the business. That is what 3-D Secure changes, and only where its rules apply.
Order state driven by the browser
A customer who closes the tab after paying never returns to your success page. If the order only updates on redirect, that payment is invisible.
The RapidCents approach
Decide where the card is entered: a hosted page, embedded fields inside your own checkout, or a payment link.
Drive order state from the webhook rather than the redirect, so a closed tab does not lose a paid order.
Set 3-D Secure rules by amount, geography or risk signal instead of authenticating every sale.
Test in the sandbox — approval, decline, refund and the authentication challenge — before production credentials are issued.
Reconcile the first online deposits against orders before any previous route is retired.
Recommended capabilities
Hosted checkout
A RapidCents-hosted payment page carrying your logo, accent colour and receipt footer, with wallet buttons on supported browsers and session expiry on abandoned carts.
Payment links
A pay-by-link URL sent by email or SMS, with partial amounts for deposits, custom references for reconciliation and deactivation once paid.
Gateway API
Authorize and capture as separate steps for ship-later orders, customer tokens for repeat purchases, idempotency keys and signed webhooks.
3-D Secure
Issuer authentication triggered by rule. Most authentications complete without a challenge screen, and where one succeeds and network rules apply, fraud chargeback liability moves to the issuer.
Tokenization
The card number is replaced by a token at capture, so your systems hold a reference that cannot be used anywhere else.
Related products
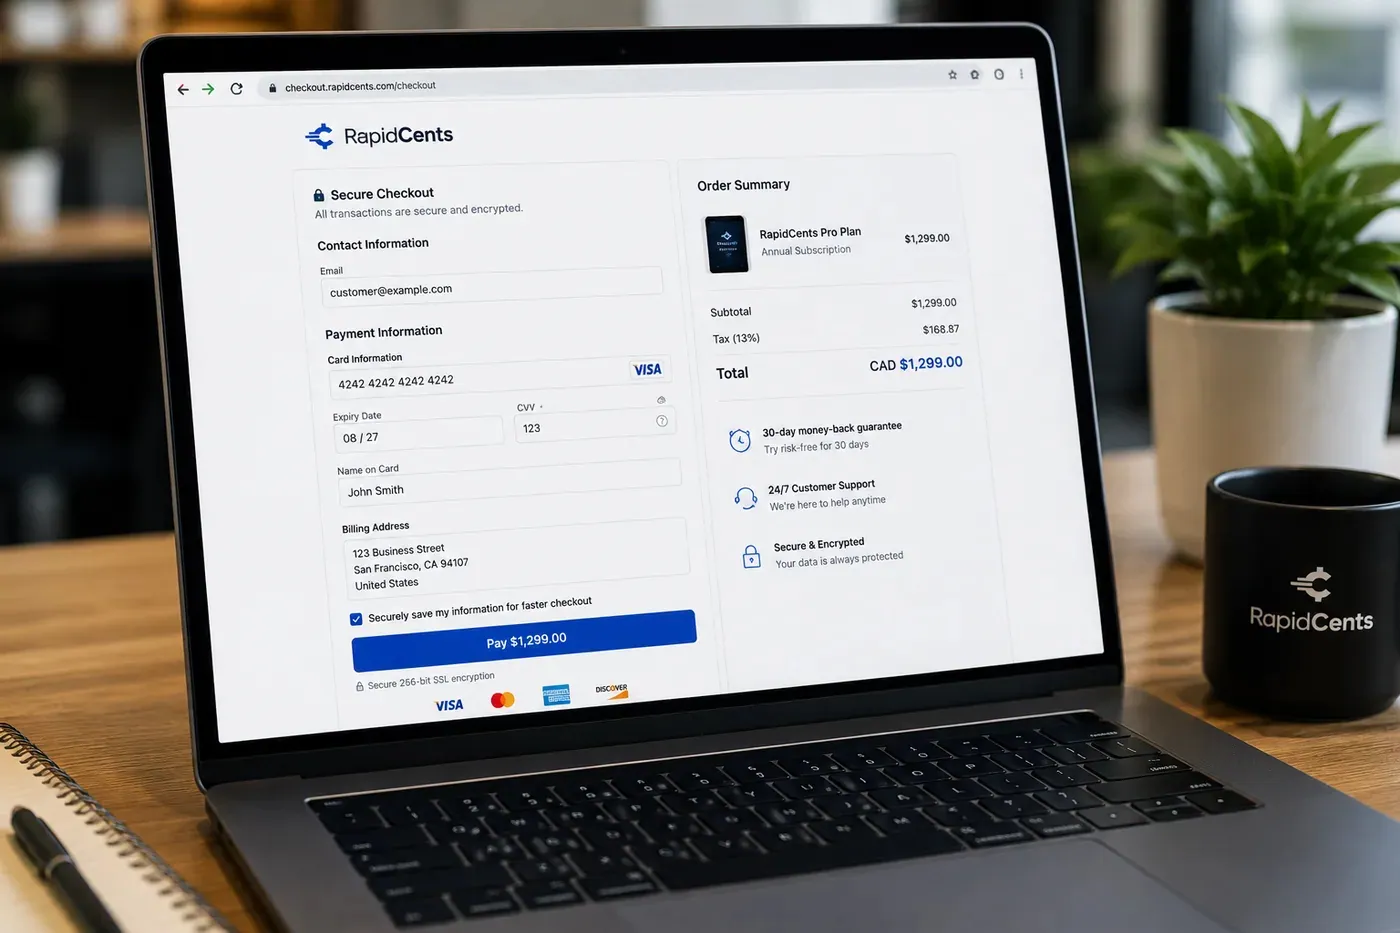
A RapidCents hosted checkout page at checkout.rapidcents.com, with the order summary and totals on the left and the card fields on the right, footed by SSL and PCI DSS assurances. Hosted Checkout
RapidCents hosted checkout delivers PCI-scoped payment pages you redirect customers to or embed via iframe…
Explore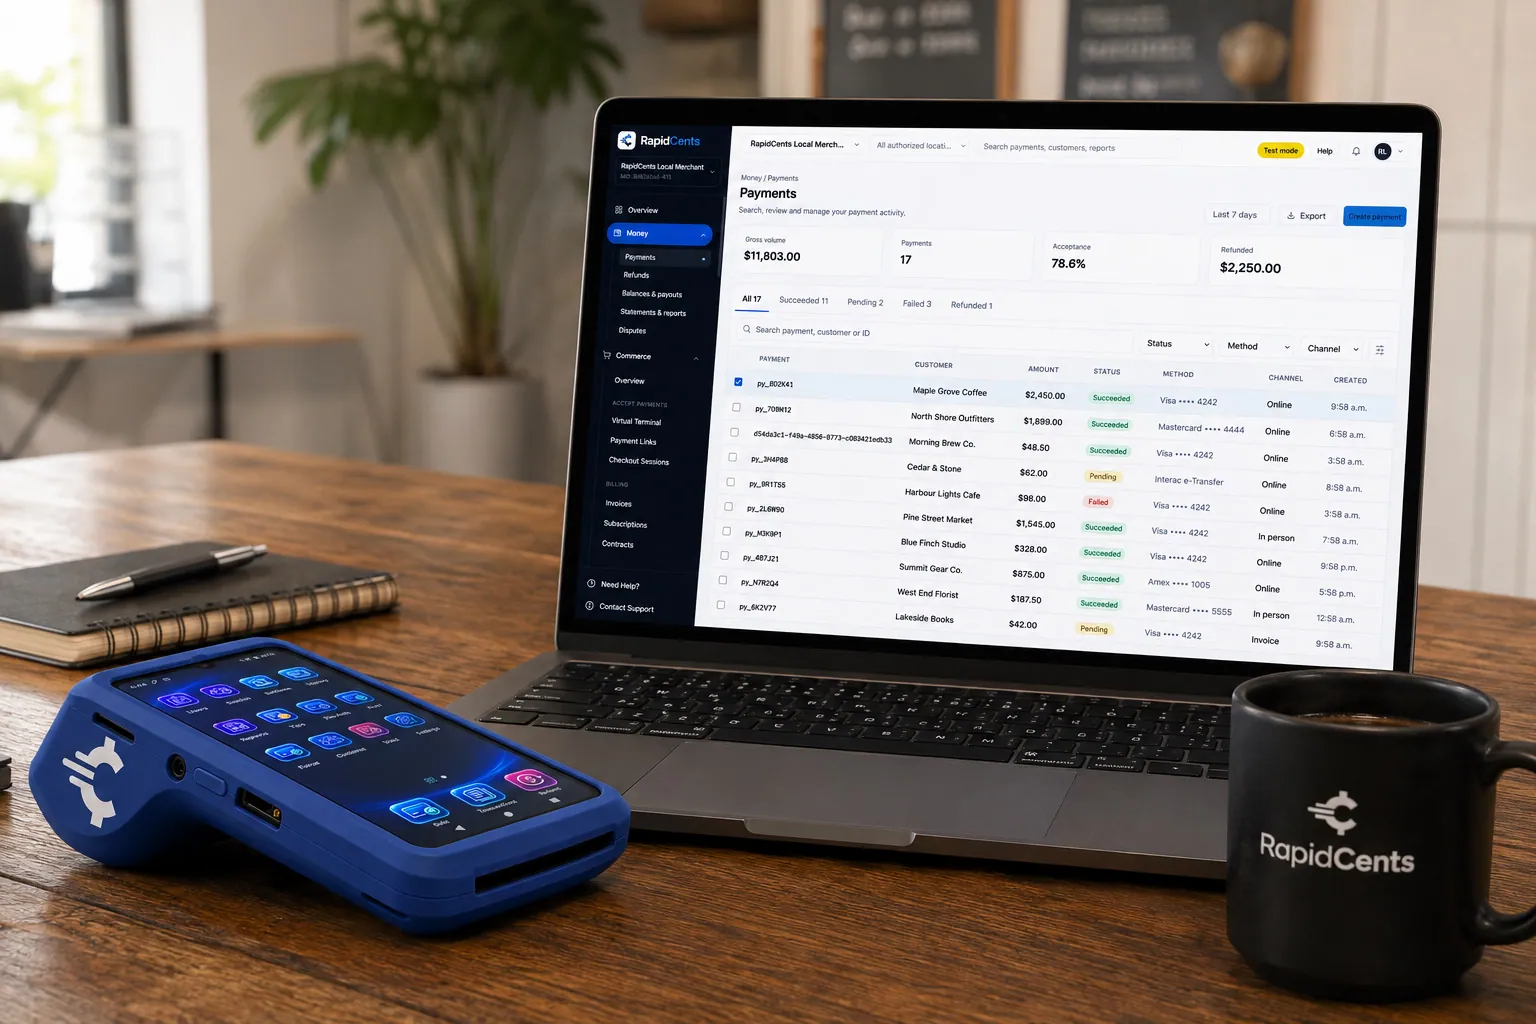
A payment-gateway integration desk: API response on screen, RapidCents terminal ready for a test sale. Payment Gateway
The RapidCents payment gateway exposes REST endpoints for authorize, capture, void, refund and tokenize…
Explore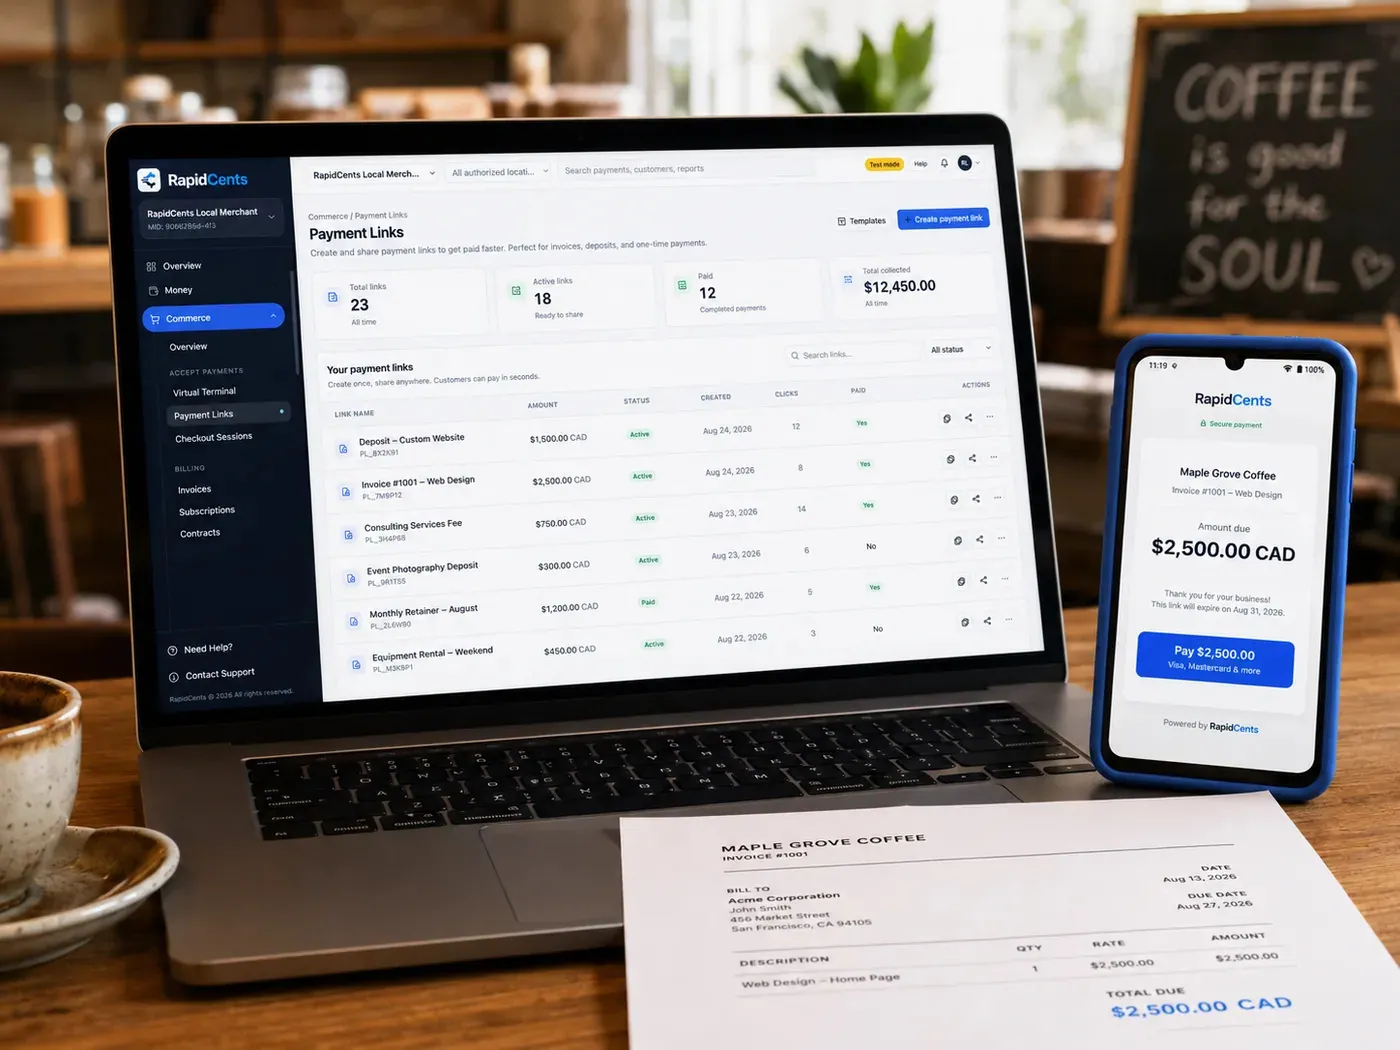
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore


Implementation approach
Integration planning
Map your checkout experience to a hosted, embedded or API approach. The decision is mostly about how much of the interface you need to own.
Sandbox certification
Complete the test cases for the flows you will run, refunds and the authentication challenge included.
Webhook setup
Configure and verify the events that drive order state, and confirm your endpoint rejects an unsigned request.
Go-live checklist
Authentication rules, receipt content and support contacts confirmed, then live traffic monitored through the first settlement cycle.
What does not change
Your storefront
Hosted checkout is a step in the flow, not a replacement for your site. Customers return to your pages afterwards.
Your in-person setup
Adding online acceptance does not change the terminals at the counter. Both channels report into the same dashboard.
Your PCI responsibility
Hosted pages and embedded fields reduce what is in scope. Annual validation on the questionnaire matching your integration remains yours.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Make this the implementation and payment-flow decision page: compare hosted checkout, embedded fields and API work for a U.S. Merchant's existing website. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments online does not, by itself, prove delivery or win a dispute.
The problem and the limit
In practice, authorization, capture, order confirmation and webhook handling with approved examples. Do not promise a fixed conversion effect from enabling or disabling 3DS. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments online does not, by itself, prove delivery or win a dispute.
What to confirm
In practice, U.S. Currency, funding conditions and the responsibility shared between merchant, developer and provider. Link to the narrower product pages for implementation detail. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Accept payments online does not, by itself, prove delivery or win a dispute.
Frequently asked questions
Do I need a developer?
Not for payment links or a hosted page reached from an existing site. You do for an embedded checkout or an API integration, because order state, refunds and webhook handling are code.
Why is my online rate higher than my counter rate?
Because interchange depends on how the card was presented. A card-not-present transaction carries higher interchange than the same card tapped at a terminal, since the risk profile of the transaction is different.
Should I turn on 3-D Secure for everything?
Applied to every sale, authentication costs conversion. Applied by rule — above an amount, from certain geographies, on risk signals — it protects the transactions where the liability shift is worth the extra step.
When do online payments reach my bank?
Batches settle and eligible accounts fund next day. Online and in-person volume appear on the same deposit report.
What happens if a customer disputes an online order?
The dispute arrives with a deadline and a reason code. Transaction and authorization detail is assembled for the response, and delivery or service evidence is what you add. Whether liability sits with you depends in part on whether the transaction was authenticated.
Can I take an online payment without a website?
Yes. A payment link or a hosted payment page can be sent directly to a customer, which is often enough for a service business that quotes and invoices rather than selling from a catalogue.
Which online payment setup suits my U.S. website?
For a business in the USA, compare developer effort, user-interface control and the actual payment flow; confirm available options. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
When does an online payment become a confirmed order?
For a business in the USA, distinguish authorization, capture, webhook events and merchant fulfillment decisions; describe the tested configuration. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
What should we test before accepting live online payments?
For a business in the USA, cover success, decline, authentication, duplicate submission, refund and reconciliation cases with current documentation. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



