


Match transactions, deposits and accounting records
Reconciliation solution is for businesses in the USA. Evaluate reconciliation solution for a U.S. business and understand the prerequisites, operational tradeoffs and commercial conditions. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.
- Payment specialists
- Interchange-plus available
- Guided migration
- Post-launch support
Who this solution is for
Controllers and bookkeepers
Whoever ties the bank statement to the sales ledger and then has to explain the difference.
Multi-channel operators
Counter, online and keyed sales settling on different rhythms into the same account.
Businesses on accounting software
Where the export format decides whether the month takes an hour or a week.
Common challenges
Batch timing versus posting date
A sale on the last day of the month can settle in the next one. Without the batch detail, that looks like a missing deposit.
Net deposits
A deposit arriving net of fees does not equal the sales it represents, and the difference has to be attributable line by line rather than estimated.
Channel totals counted differently
Two systems that both report sales but treat refunds, tips or day boundaries differently will not agree, and neither of them is wrong.
The RapidCents approach
Start from the deposit rather than the sales total, because the bank is the fixed point.
Open the deposit detail to see which batch it came from and what was deducted.
Separate the channels, since in-person, online and keyed report differently and settle differently.
Export with the fee columns — interchange, assessment and processor fee — so the deduction is explained rather than assumed.
Schedule the export so the file arrives on the day the close starts, instead of someone logging in to produce it.
Recommended capabilities
Deposit-level detail
Each settlement tied to the transactions behind it, with the fees deducted shown against it.
Channel breakdown
In-person, online and keyed totals separated within the same report.
Fee detail export
Interchange, assessment and processor fee as separate columns, so cost is auditable at transaction level.
Accounting exports
CSV and PDF output for import into accounting systems, with saved filters kept as reusable report definitions.
Scheduled delivery
Reports emailed weekly or at month-end automatically, so the close does not start with a manual pull.
Related products
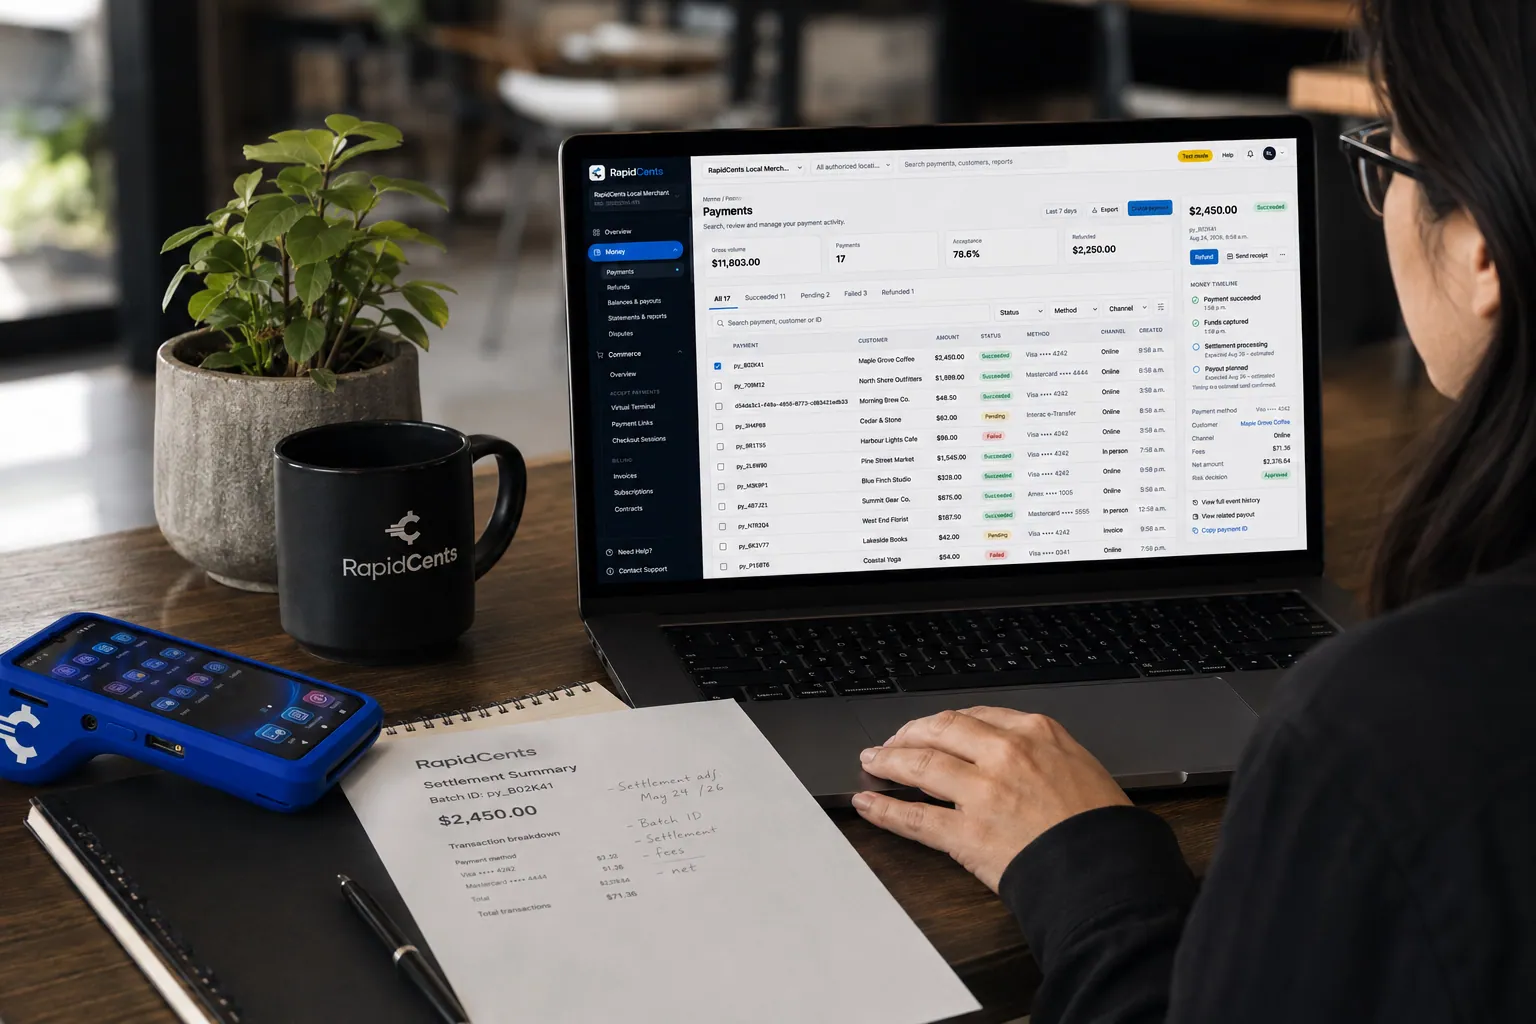
A merchant reviews RapidCents reports for volume, mix and payouts, with the terminal that took the sales on the desk. Reporting
RapidCents reporting delivers customizable transaction, settlement and fee reports with CSV and PDF export…
Explore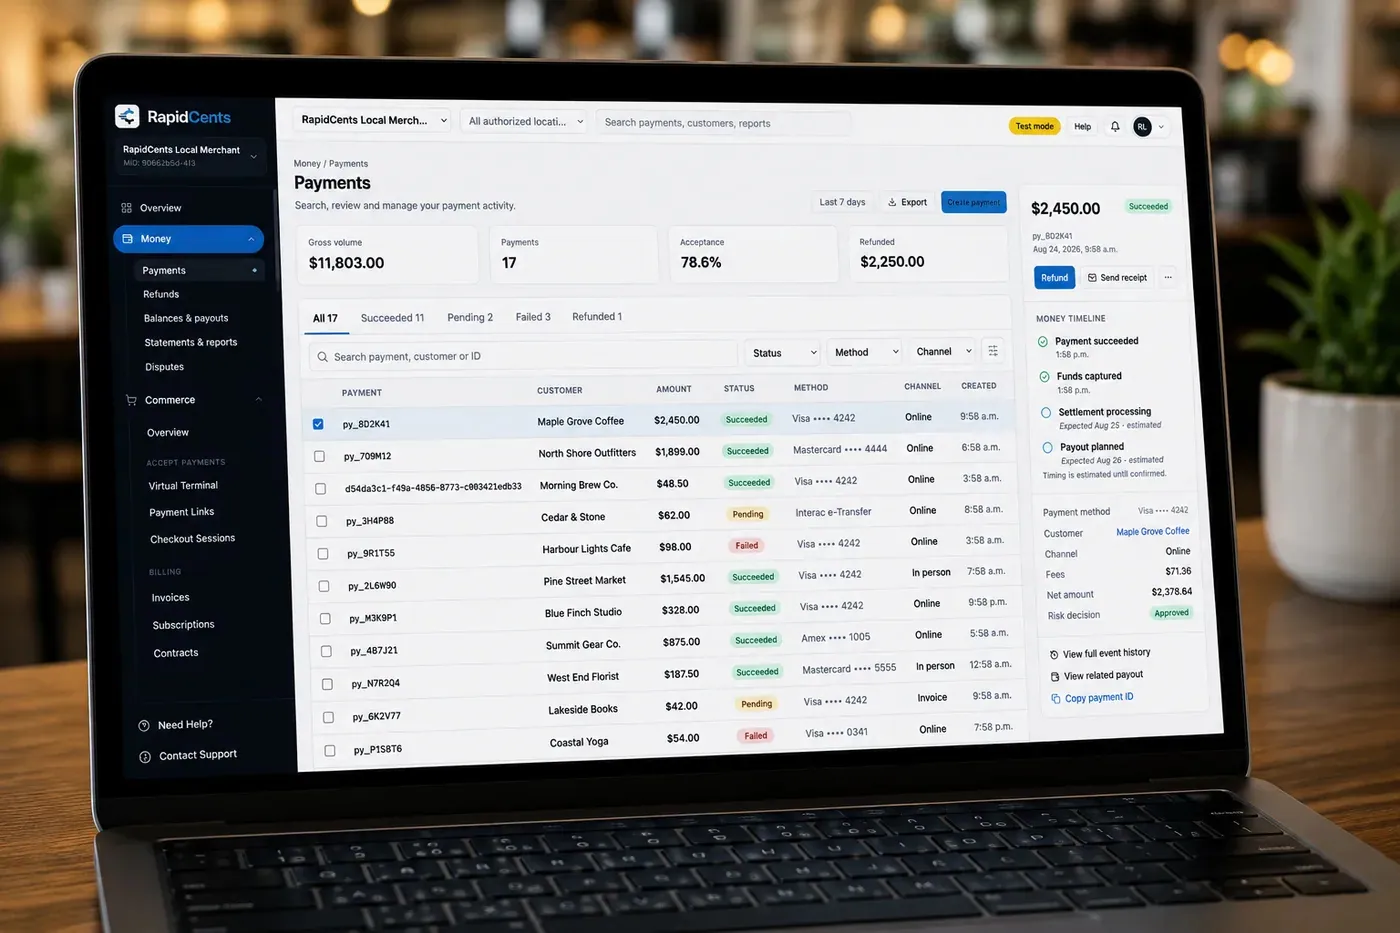
The RapidCents payments screen: gross volume, payment count, acceptance rate and refunds across the top, a filterable transaction list below, and a money timeline on the right tracing one payment from capture to planned payout. Merchant Dashboard
The RapidCents merchant dashboard gives owners, managers and finance staff a single signed-in view of live…
Explore


Implementation approach
Map the close
Establish which reports the month actually needs and who reads them, before configuring anything.
Configure exports
Date ranges, channel filters and fee columns saved as templates rather than rebuilt each period.
Test against a closed month
Run the new export against a period already reconciled, so any discrepancy is in the report rather than in the books.
Automate and review
Put the export on a schedule, then check the first automated cycle against a manual pull.
What does not change
Your accounting software
Exports import into the system you already run. Reconciliation improves the input, not the ledger.
Your close process
The sequence your finance team follows stays. What changes is how much of it is spent locating detail.
Settlement timing itself
Batches settle and eligible accounts fund next day. Reporting makes the timing visible; it does not change it.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Follow a U.S. Day's transactions through adjustments and fees to a bank deposit. In practice, why sales totals and cash received may differ. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Reconciliation solution does not, by itself, prove delivery or win a dispute.
The problem and the limit
The practical view covers identifiers and report fields needed to investigate an unmatched item. Keep separate downloadable reports from a verified live accounting connection. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Reconciliation solution does not, by itself, prove delivery or win a dispute.
What to confirm
In practice, cutoff dates, time zones, held transactions and exception ownership under the actual setup. Provide a clearly labeled sample reconciliation instead of claiming automatic perfection. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Reconciliation solution does not, by itself, prove delivery or win a dispute.
Frequently asked questions
Why does my deposit not match my sales?
Three ordinary reasons: fees deducted before the deposit, a batch that closed after the day boundary, and refunds netted against the same settlement. Deposit detail shows which of the three applies rather than leaving it to be inferred.
Can I get the fee breakdown per transaction?
Yes. The fee detail export carries interchange, assessment and processor fee as separate columns, which is what makes an effective rate calculation checkable rather than a summary you have to trust.
How do I handle a sale and its refund in different months?
The refund settles in the period it was processed, against its own batch. Deposit-level detail links it back to the original transaction, so the two are matched across the boundary rather than netted into one figure.
Do exports work with QuickBooks or Xero?
Reports export as CSV and PDF for import into accounting systems. The practical work is agreeing the mapping once and saving it as a report definition, so the format does not drift between periods.
Can the finance team have access without seeing everything?
Yes. Roles are separate — cashier, manager and admin — with audit trails, so a bookkeeper can hold reporting access without refund permissions.
What causes tips to reconcile badly?
Tips added on the device after the sale amount is captured, and tips mapped to the wrong general ledger account in an integrated setup. The first appears as a batch total differing from the POS total; the second only shows up in the ledger.
Why does a bank deposit differ from the day's sales total?
For a business in the USA, in practice, relevant timing, refunds, fees and adjustments as possibilities, using the actual settlement model. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can reconciliation data sync with our accounting software?
For a business in the USA, name only tested software, versions and connection types; distinguish export from automatic posting. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should finance investigate an unmatched payment?
For a business in the USA, in practice, the approved sequence of reference checks and escalation, without exposing sensitive payment data. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



