


Payment terminals for towing and roadside, release fees collected at the scene
Towing & Roadside is for businesses in the USA. Tow operator evaluating on-scene and remote collection with itemized charges, authorized payer records and clear vehicle-release boundaries. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
Call taken, truck dispatched to the scene
Roadside payment collected before the hook comes off
Release and storage fees paid at the yard
Insurers and fleets invoiced with the job report
Payment challenges
The customer is not having a good day
Payment is taken at a breakdown or a collision, from someone who did not choose to be there.
No release without payment
The vehicle does not leave the yard until storage is settled, so the charge has to go through at the gate.
Three payers, one tow
The driver, the insurer and the fleet may each owe part of the same job, and only one of them is standing in front of you.
Choose the right payment setup for Towing & Roadside
Choose towing payment terminal
For Towing & Roadside, map the deposit, staged payments, and final balance, the field and customer visits, and the counter or service point before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Towing & Roadside
For Towing & Roadside, prioritize a portable payment terminal when payment happens away from a fixed counter. If staff also collect at a desk, assess a separate countertop setup instead of forcing one device to cover two jobs.
Compare payment processing fees
For Towing & Roadside, request a written fee breakdown covering deposits and final balances and device use in the field. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Towing & Roadside payments
To set up Towing & Roadside payments, document testing the field workflow, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
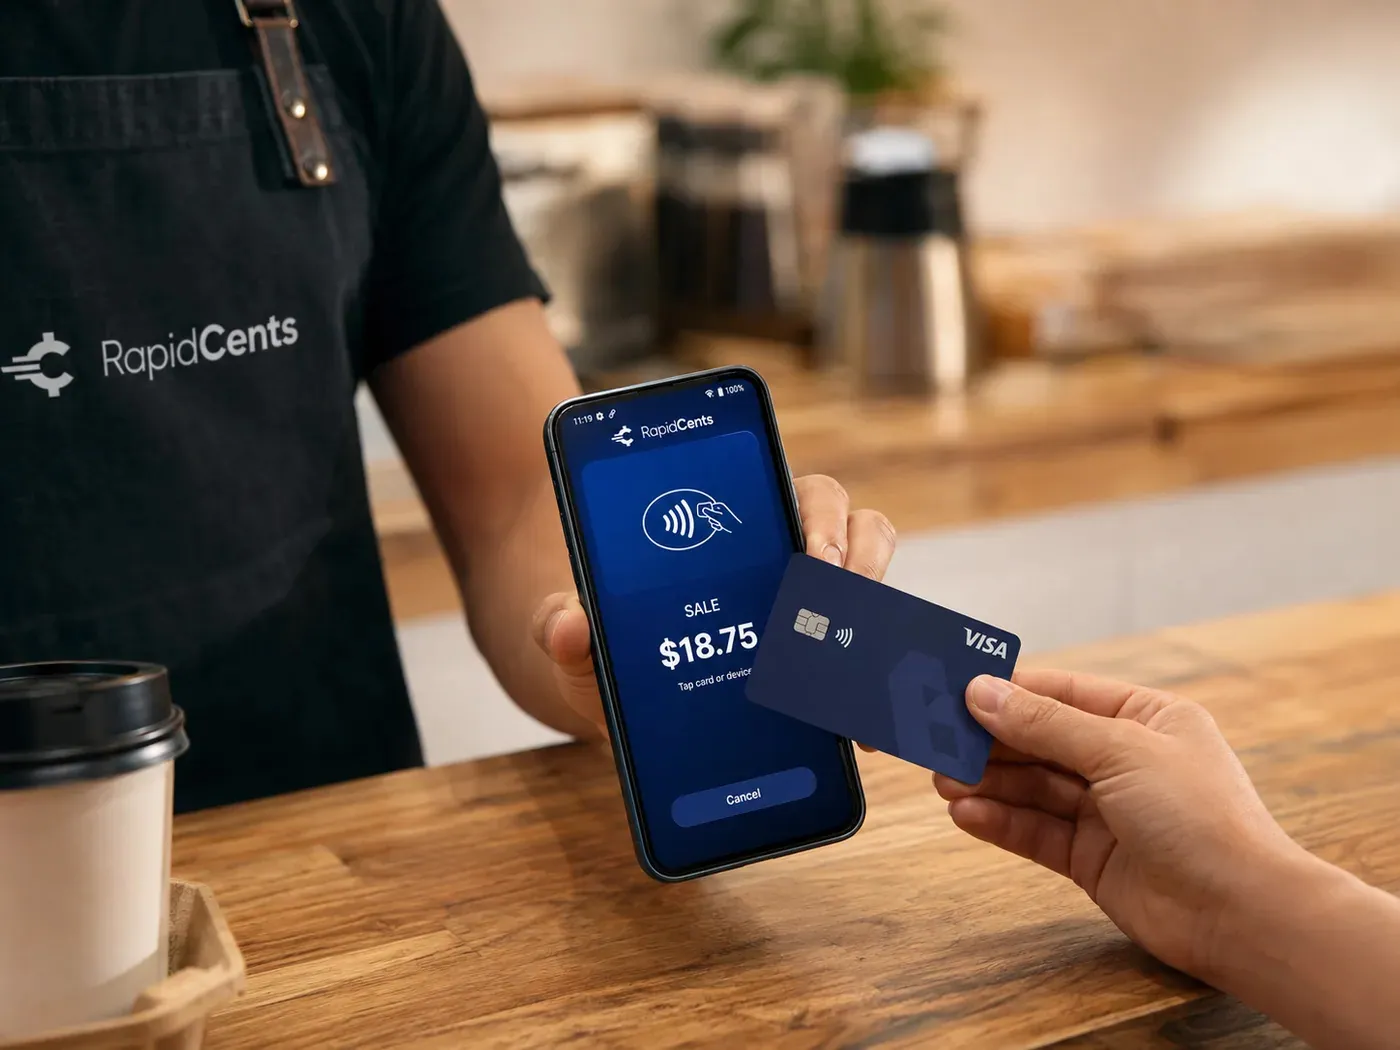
A café worker holds a phone running RapidCents Tap to Pay, showing an $18.75 sale and the contactless symbol, while a customer holds a Visa card to the screen. No separate card reader is present. Tap to Pay
RapidCents Tap to Pay turns supported iPhones and Android devices into contactless payment terminals without…
Explore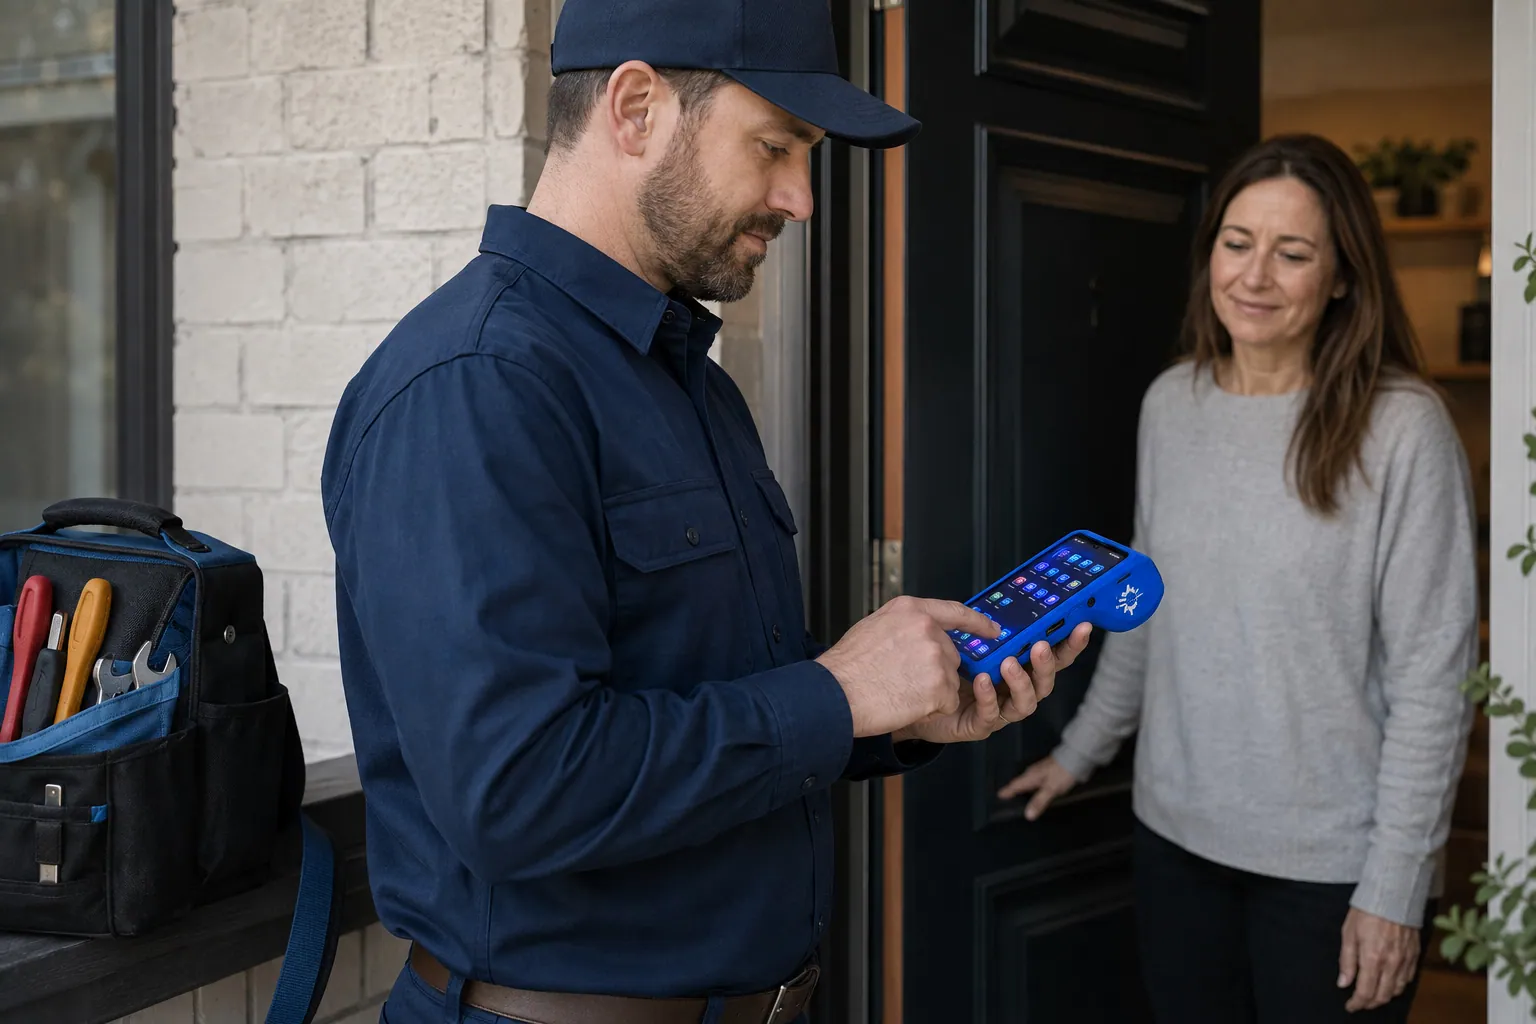
A staff member takes a card payment on a RapidCents handheld terminal, with the same sale appearing on the dashboard. Mobile Terminals
RapidCents mobile terminals are battery-powered wireless devices with LTE and Wi-Fi so staff accept payments…
Explore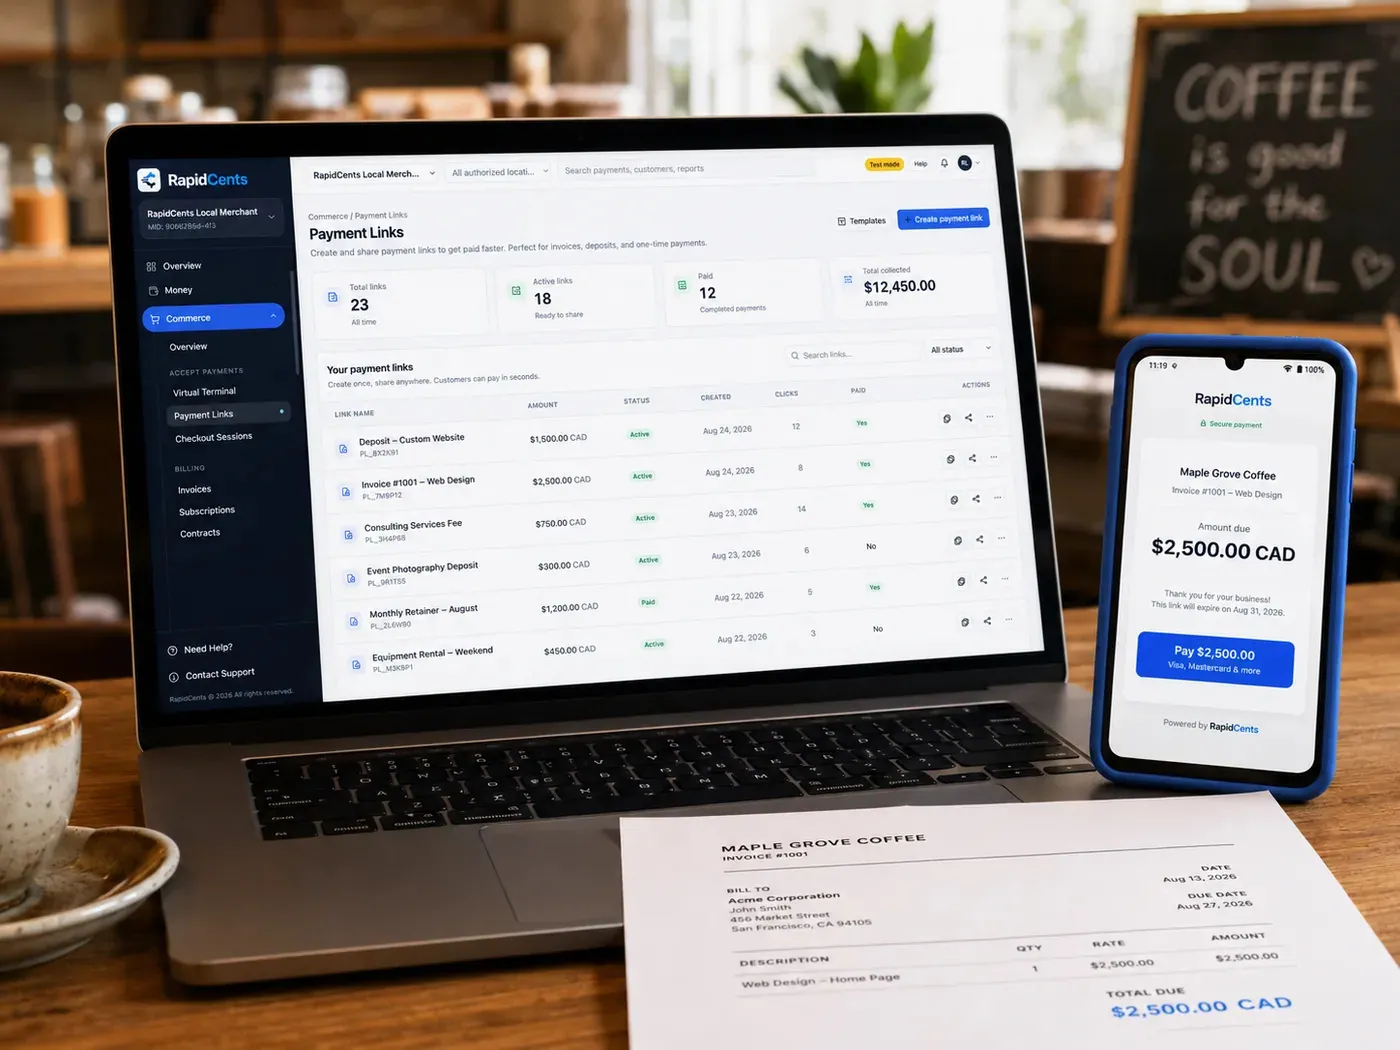
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore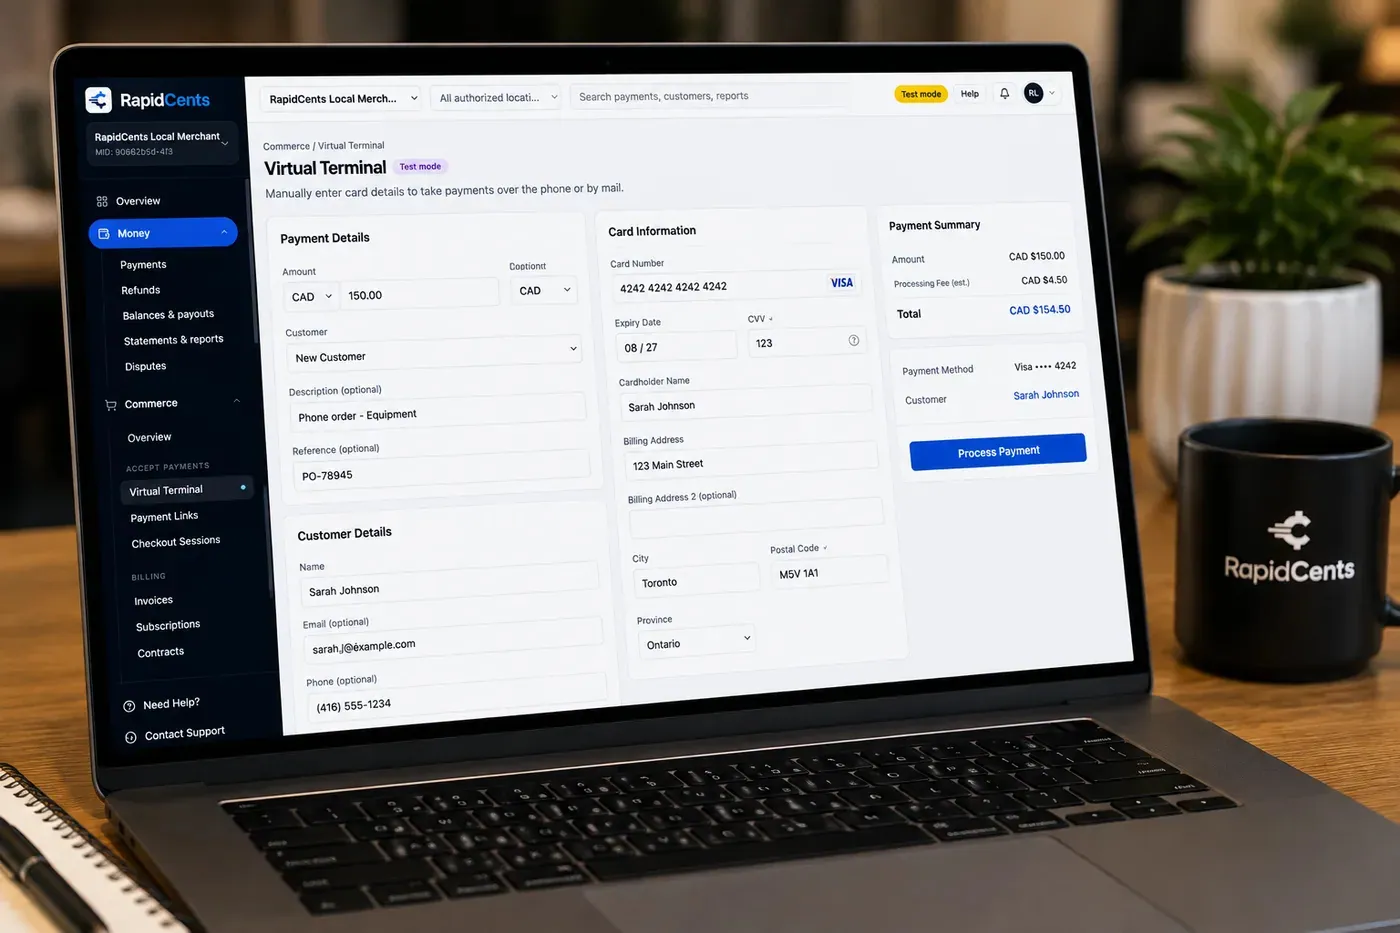
The RapidCents virtual terminal: payment details, card number, expiry and CVV keyed by hand on the left, with a payment summary on the right showing the amount, the estimated processing fee and a Process Payment button. Virtual Terminal
The RapidCents virtual terminal lets authorized staff enter mail-order and telephone-order payments through a…
Explore


How this gets set up
Card taken at the scene
The driver taps the motorist's card on a phone at the roadside, because the vehicle is leaving and so is the customer.
Release fee at the impound gate
Storage and release charges are collected at the yard before the vehicle is handed over, on an LTE terminal rather than at a counter.
When a third party is paying
If an insurer, a fleet or a property manager is covering the bill, the charge goes out as a payment link or is keyed in the virtual terminal.
Receipt emailed before the truck leaves
The emailed receipt naming the vehicle and the charges is what the motorist submits to their own insurer.
Integrations
Towbook
Towbook holds the call, the vehicle and the storage clock, and the payment posts to that call so the yard knows a vehicle is cleared for release.
Omadi exports
Omadi exports move dispatch and payment detail out as a file for the operator's own records — an export, not a live sync.
Operations, security and going live
Tow, storage and release read as separate charges
Reporting has to show which part of a bill was the tow and which was daily storage, because those are the lines a customer disputes.
Disputes come weeks after the tow
A chargeback on a release fee is answered with the receipt and the record of who authorised the tow, not from memory.
No card numbers on a tow slip
Tapping at the scene or keying in the virtual terminal keeps card details off the paper slip that rides in the truck.
Live on every truck, not just the office
Going live means each driver's phone or in-cab terminal is enrolled and tested, since the yard counter is rarely where the money is taken.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Trace a US roadside call from the quoted service to authorized mileage or equipment charges and payment. Keep separate roadside assistance, towing and any later storage invoice with clear references. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Towing & Roadside does not, by itself, prove delivery or win a dispute.
The problem and the limit
In practice, approval for changed work, itemized receipts and duplicate-charge investigation. A successful payment does not determine whether a vehicle may legally be held, released or charged an additional fee. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Towing & Roadside does not, by itself, prove delivery or win a dispute.
What to confirm
Use a USD example with an authorized remote payer to compare a payment link and technician terminal. Verify connectivity, staff permissions and job references; do not promise funds are final at authorization. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Towing & Roadside does not, by itself, prove delivery or win a dispute.
Payment questions from Towing & Roadside
What should businesses compare when choosing towing payment terminal for Towing & Roadside?
Compare towing payment terminal against the real payment journey: the deposit, staged payments, and final balance, the field and customer visits, and the counter or service point. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Towing & Roadside?
Because Towing & Roadside also collects away from a fixed counter, test a portable terminal in real conditions. If staff also collect at a desk, validate the need for a separate countertop setup.
Which payment channels are relevant for Towing & Roadside?
For Towing & Roadside, start with the deposit, staged payments, and final balance, the field and customer visits, and the counter or service point. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Towing & Roadside?
For Towing & Roadside, compare costs related to deposits and final balances and device use in the field using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Towing & Roadside?
For Towing & Roadside, document testing the field workflow, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
Can a family member pay remotely while the driver is at the scene?
For a business in the USA, an authorized payer can use an approved remote payment flow when available. Before you rely on this, confirm the amount and job reference, and verify the completed transaction in the trusted system rather than relying on a screenshot. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should extra mileage or specialized recovery work be charged?
For a business in the USA, disclose and obtain approval for the additional work and amount, then itemize it on the service record and payment request. Applicable fee and release rules require separate review. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Does a successful card payment automatically authorize vehicle release?
For a business in the USA, no. The operator must follow its approved release process and applicable requirements. Payment status is one operational input, distinct from ownership, identity, holds and other release conditions. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Taxi & Transportation
Taxi, limo and private hire fleets equip drivers with in-vehicle mobile terminals, fleet…
Parking
Parking operators accept pay-by-plate, monthly permits and event surcharges via…
Automotive
Dealers and repair shops take service deposits, repair order payments and phone…
Car Wash
Car washes sell memberships, unlimited plans and single washes with fast lane terminals…
Car Dealerships
Dealerships take a card deposit to hold a vehicle, cap card payment on the purchase…
Limousine & Charter
Limo and charter operators quote a trip, take a card to secure the booking, and settle…
Courier & Delivery
Couriers bill business accounts on terms and retail senders at drop-off, with drivers…
Driving Schools
Driving schools sell course packages up front or on instalments then draw lessons down…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



