


Payment processing for car dealerships: deposits, service and parts
Car Dealerships is for businesses in the USA. Compare payment options for vehicle deposits, service invoices and parts sales; understand timing, payer authorization, exceptions and reconciliation for car dealerships. The sections below separate the workflow, the control and its limit, and the account facts to confirm before you rely on them.

- PCI DSS Level 1
- SOC 2 Type II
- All major card brands: Visa · Mastercard · Amex · Discover · PIN debit
- Interchange-plus available
- Specialist onboarding support
Operational workflows
Card deposit by payment link to hold a vehicle
Vehicle balance settled off card at delivery
Service and parts tickets rung on terminals in the drive lane
Sales, service and parts reported separately per rooftop
Payment challenges
A card cap on the vehicle itself
The deposit goes on a card and the balance cannot, so a single deal settles across two different rails.
Deposits returned when financing falls through
A hold taken on Saturday afternoon has to come back cleanly when the approval does not arrive on Monday.
The service drive is the busy counter
A service department writes far more tickets in a day than the showroom does, and every one of those customers is waiting for a car on a hoist.
Choose the right payment setup for Car Dealerships
Choose car dealership payment processing
For Car Dealerships, map the deposit, staged payments, and final balance, the counter or service point, and each location and consolidated oversight before choosing a setup. Select channels that match those moments, then confirm that the chosen solution genuinely covers each channel.
Payment hardware for Car Dealerships
For Car Dealerships, start with the place customers pay in person: a countertop terminal, smart terminal, or portable device depending on the workflow. Verify that the hardware fits the real volume and workspace.
Compare payment processing fees
For Car Dealerships, request a written fee breakdown covering deposits and final balances and cost detail by device and location. Compare the effective cost across the real card and channel mix; do not choose on a headline rate alone.
Set up or switch Car Dealerships payments
To set up Car Dealerships payments, document the real payment journey, confirm compatibility before purchase, then test a real payment flow before going live.
Recommended products
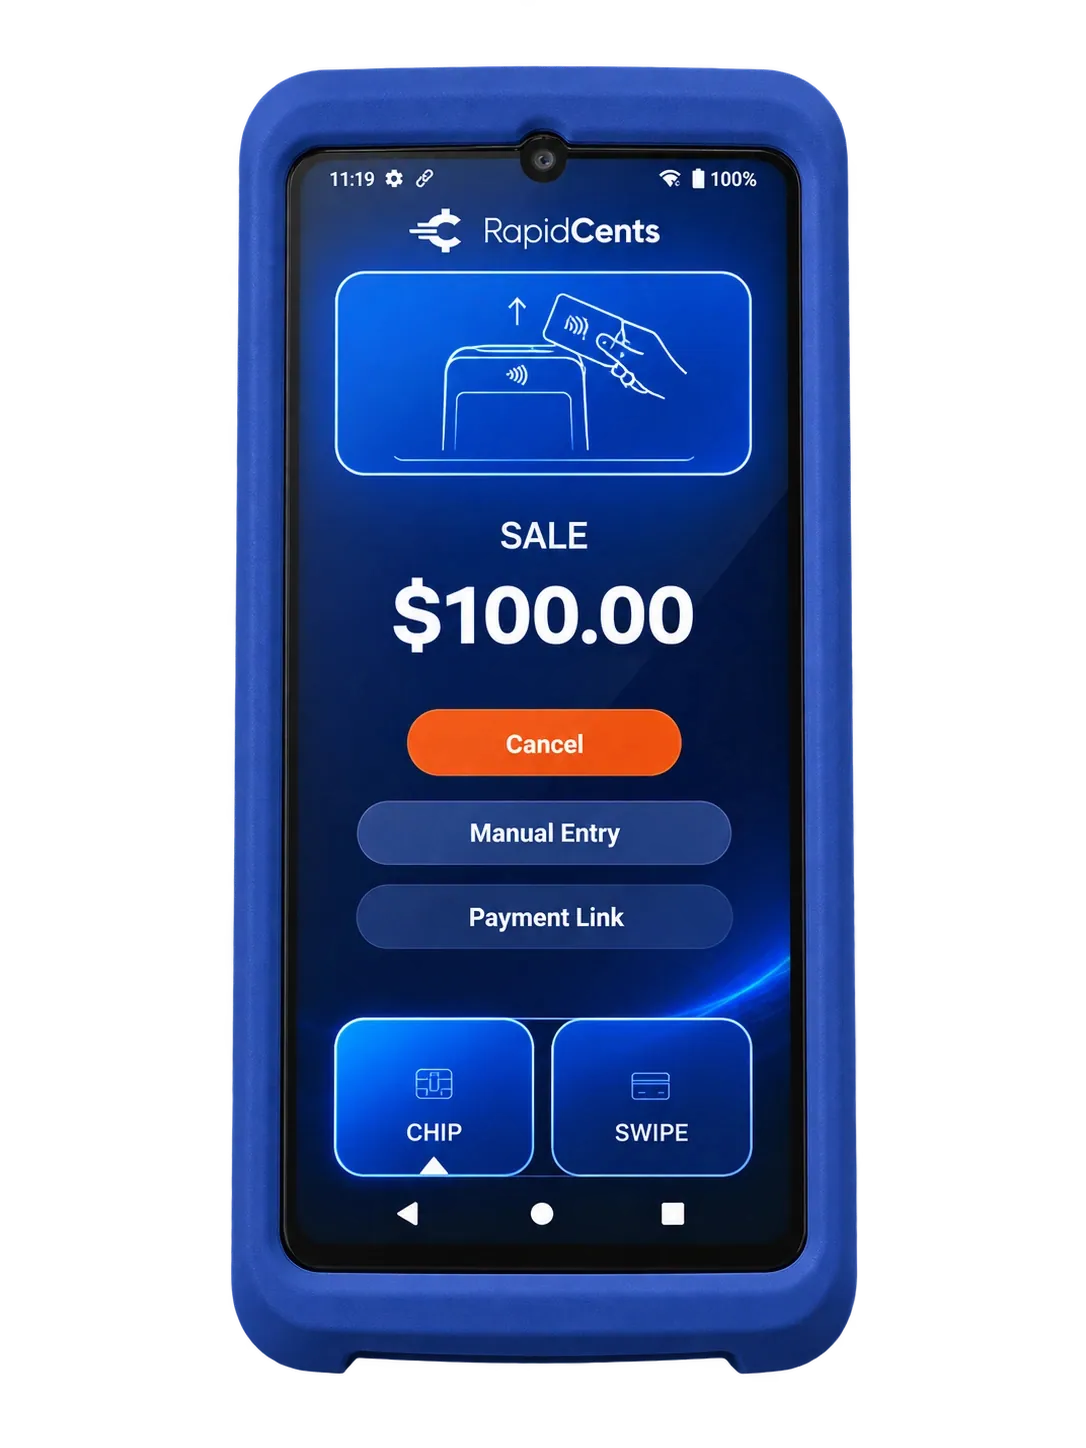
The RapidCents Rivo Go standing upright in its blue silicone case, showing the full-touch sale screen a customer reads across the counter. Payment Terminals
RapidCents payment terminals cover countertop, mobile and smart form factors so you can accept chip…
Explore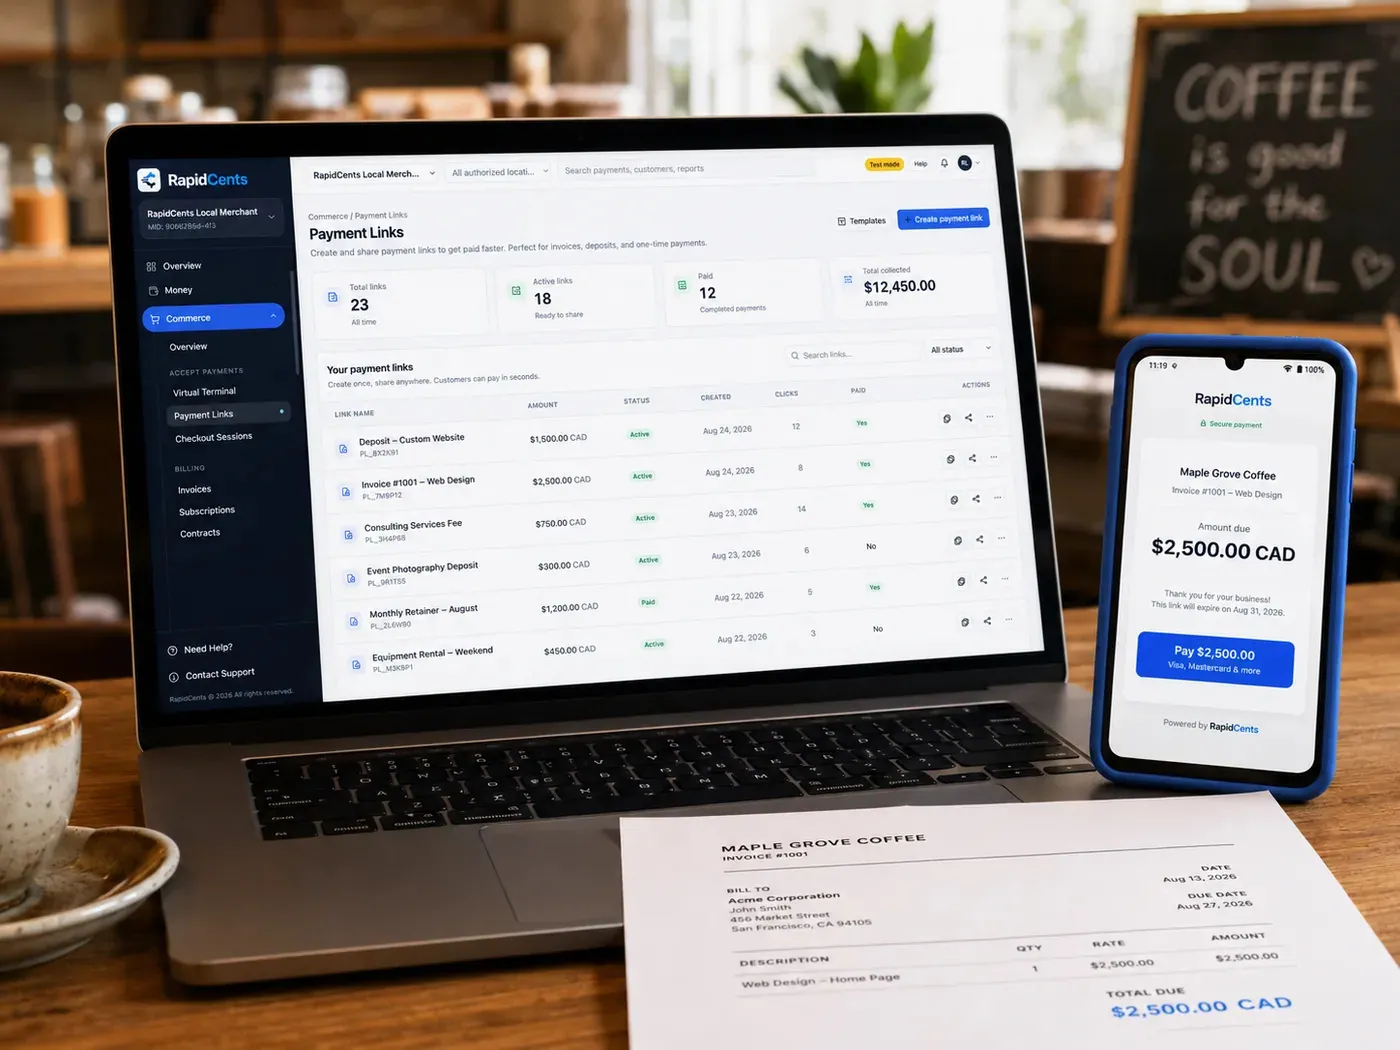
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore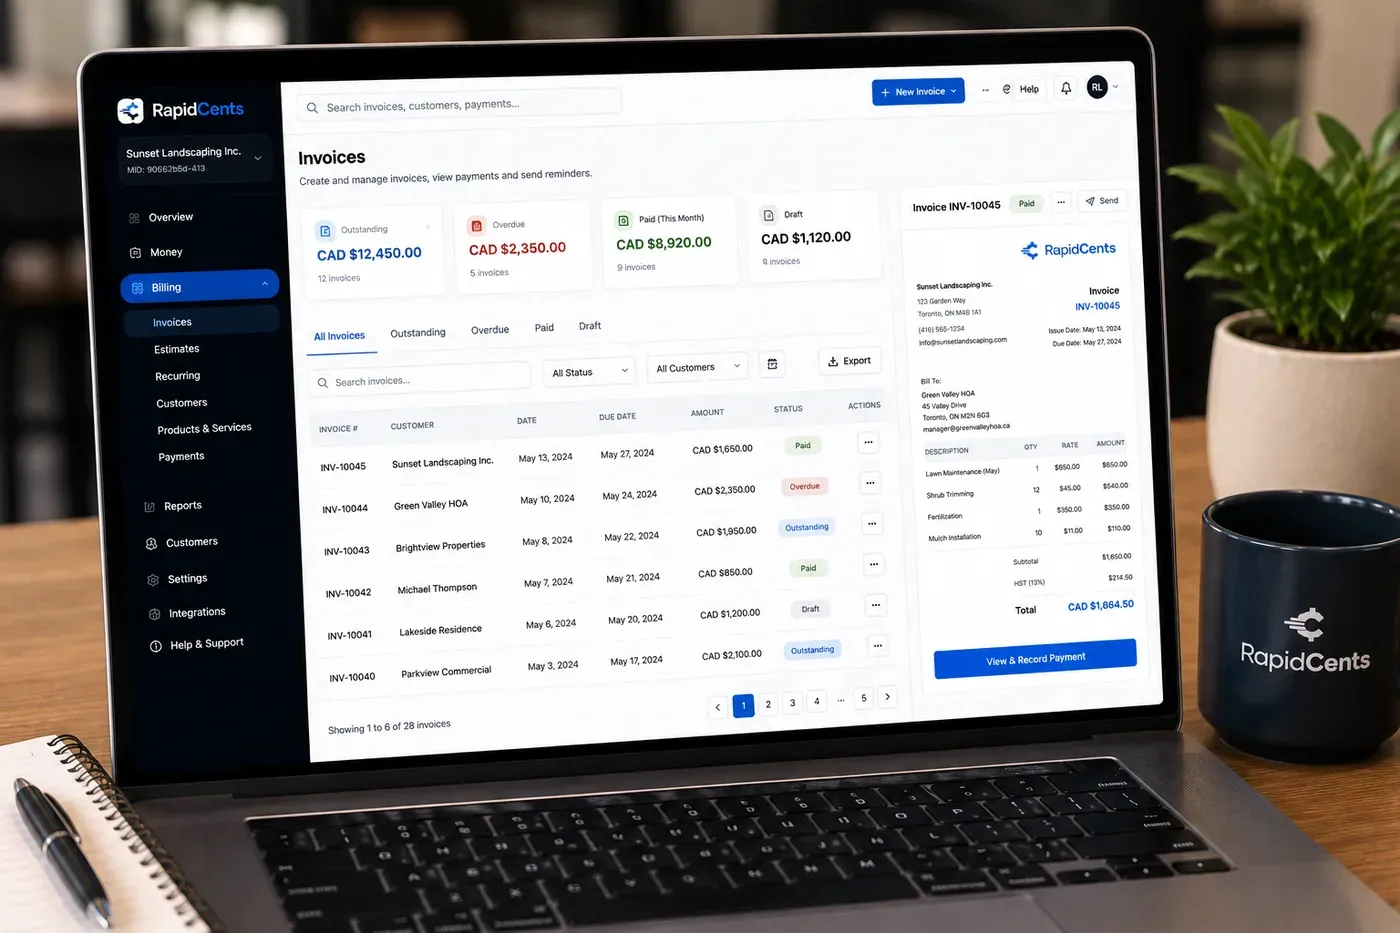
The RapidCents invoices screen: outstanding, overdue, paid and draft totals across the top, the invoice list below them, and a preview of one invoice on the right with its line items and a View & Record Payment button. Invoicing
RapidCents invoicing helps professional services, contractors and B2B suppliers create branded invoices…
Explore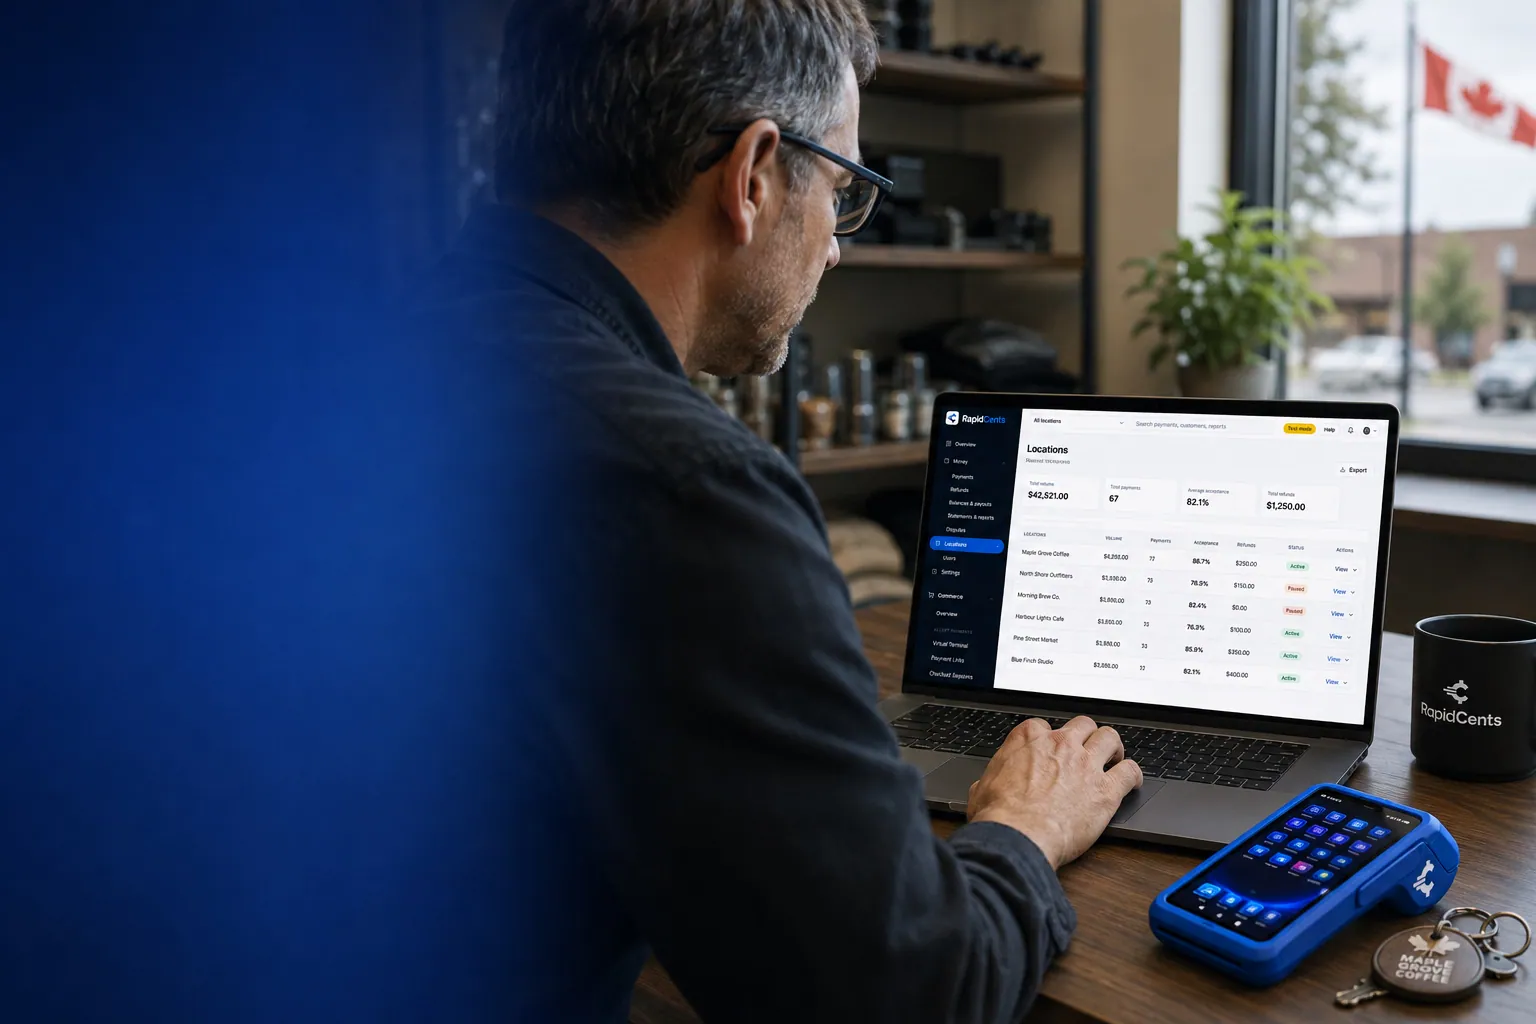
One RapidCents account comparing sales across locations, with a terminal representing the store-level capture. Multi-Location
RapidCents multi-location tools organize stores, franchises and regions in a hierarchy with location-level…
Explore


How this gets set up
The deposit before the drive out
A payment link sent from the sales desk takes the deposit that holds a unit, so a buyer two hours away commits before setting off.
Service drive and parts counter
Payment terminals go where the daily transaction count actually lives, on the service cashier and the parts counter.
Fleet work invoiced, not rung
Commercial fleet and body shop accounts are invoiced on terms instead of being pushed through the service till.
Rooftops kept separate
Each location and each department reports on its own line inside one merchant account.
Integrations
CDK exports
CDK exports carry the settled service and parts amounts out as a file for the DMS ledger rather than writing back into it live.
PBS Systems
PBS Systems holds the deal and the repair order, so a payment recorded against a repair order closes it out at the cashier instead of being matched later.
Xero
Xero receives each rooftop's deposits, service and parts revenue on separate lines, so one store's numbers do not absorb another's.
Operations, security and going live
Sales deposits, service and parts read apart
Unit deposits, service drive volume and parts sales report separately, because three managers and three margins are reading them.
The card share stays controlled
The dealership sets how much of a purchase it takes on card; the link deposit stays small and traceable while the balance is settled off card.
A deposit needs a paper trail
A deposit paid on a link carries the buyer's own confirmation, which matters when a hold is disputed or refunded because financing fell through.
Service drive first
The highest-volume counter goes live first, and the sales desk deposit link follows once daily service reconciliation has settled into a rhythm.
For businesses in the USA
A direct answer for a business in the USA: the workflow, the limit, and what to confirm next.
The payment workflow
Keep separate a card deposit used to reserve a vehicle from the vehicle’s remaining purchase balance, service-lane bills and parts-counter payments. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Car Dealerships does not, by itself, prove delivery or win a dispute.
The problem and the limit
In practice, what happens if the buyer cancels or financing does not close. State deposit terms clearly; do not imply full vehicle balances or every card type are accepted. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Car Dealerships does not, by itself, prove delivery or win a dispute.
What to confirm
Use a redacted vehicle reservation and deposit refund example; show reporting by sales, service and parts without claiming an unverified dealer-management integration. Confirm eligibility, presentment currency, settlement currency and the enabled payment methods on the USA merchant account before quoting them. An illustrative amount is an example, not a fee or a funding promise. Car Dealerships does not, by itself, prove delivery or win a dispute.
Payment questions from Car Dealerships
What should businesses compare when choosing car dealership payment processing for Car Dealerships?
Compare car dealership payment processing against the real payment journey: the deposit, staged payments, and final balance, the counter or service point, and each location and consolidated oversight. Start with the required channels and hardware, then confirm compatibility and support before committing.
What payment hardware is practical for Car Dealerships?
For Car Dealerships, start with the workstation where customers pay and the space available. A test of the real flow reveals the right form factor better than a feature comparison alone.
Which payment channels are relevant for Car Dealerships?
For Car Dealerships, start with the deposit, staged payments, and final balance, the counter or service point, and each location and consolidated oversight. Keep only the channels that match those moments, then verify the complete customer flow before offering them.
How should payment processing fees be evaluated for Car Dealerships?
For Car Dealerships, compare costs related to deposits and final balances and cost detail by device and location using actual transactions. Request a written breakdown of fees and terms rather than relying on an advertised rate alone.
What should be confirmed before setting up payments for Car Dealerships?
For Car Dealerships, document the real payment journey, verify the needed compatibility, and test the flow before going live. This exposes manual steps and exceptions before customers encounter them.
Can a customer pay a vehicle reservation deposit remotely?
For a business in the USA, an approved remote deposit flow may be offered with a vehicle or reservation reference, amount and disclosed terms. Cover how the dealership confirms payment and later applies or refunds it; verify underwriting and transaction limits before describing availability for a particular vehicle. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
How should service and parts payments be separated from vehicle sales?
For a business in the USA, use separate department, repair-order, parts-order and vehicle-sale references in the supported system. Reconcile each department's receipts and refunds to its ledger, and describe dealer-management integration only where verified; a shared settlement deposit should not erase the underlying allocations. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Can a dealership accept the full vehicle purchase price by card?
For a business in the USA, make acceptance conditional on the dealership's policy, merchant approval, transaction limits and the issuer's authorization. In practice, any permitted split payment and written fee disclosure only after verification; approval for a reservation deposit does not establish eligibility for the full vehicle balance. This depends on the approved USA account setup and does not remove the merchant's own records or dispute duties.
Related industries
Taxi & Transportation
Taxi, limo and private hire fleets equip drivers with in-vehicle mobile terminals, fleet…
Parking
Parking operators accept pay-by-plate, monthly permits and event surcharges via…
Towing & Roadside
Tow operators capture release fees and roadside payments in the field with LTE mobile…
Automotive
Dealers and repair shops take service deposits, repair order payments and phone…
Car Wash
Car washes sell memberships, unlimited plans and single washes with fast lane terminals…
Limousine & Charter
Limo and charter operators quote a trip, take a card to secure the booking, and settle…
Courier & Delivery
Couriers bill business accounts on terms and retail senders at drop-off, with drivers…
Driving Schools
Driving schools sell course packages up front or on instalments then draw lessons down…
Take the next step
Talk to a RapidCents specialist
RapidCents Fee Check reads a processing statement and shows interchange separately from the markup. Upload a statement for an instant breakdown, or open a merchant account and start accepting payments on one account.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



