


Payment processing for apparel wholesalers and uniform suppliers
Payment processing for apparel wholesalers means collecting from the retailers, schools and employers you supply, by invoice payment link, virtual terminal, stored card or bank payment, against approved orders. The key jobs are custom-uniform production deposits, partial seasonal shipments and size-exchange credits. RapidCents integrates with many major platforms, so you keep the order and accounting software you run.

- PCI DSS Level 1
- SOC 2 Type II
- All major cards: Visa, Mastercard, Amex, Discover, UnionPay, Diners Club & PIN Debit
- Interchange-plus available
- Specialist onboarding support
How apparel, textile and uniform wholesalers get paid
B2B textile payments repeat four jobs: production deposits on custom work, invoices for seasonal shipments, reorders on account and credits for exchanges. Each job starts from an approved order, so every payment carries the order, invoice and reference your finance team needs.
Production deposits on custom uniforms
A school, team, employer or retailer approves artwork and a size run, then pays a deposit before production starts. You send a payment link or a signed quote with the deposit request. If the artwork is revised, you send an updated request first. Finance sees the deposit against the order number.
Seasonal stock orders by shipment
A retailer buyer places a spring or fall order that ships in waves. Each shipment gets its own invoice and payment link, so the buyer pays what arrived. If an item is backordered, it stays off the invoice until it ships. Finance sees every payment against a shipment reference.
Reorders on account
A store reorders basics by phone or email. Your staff take the card on the virtual terminal, or charge a stored card the buyer authorized for repeat orders. If a card is declined, the buyer gets a fresh payment link. Finance sees the order reference on each receipt.
Exchanges, returns and credits
A buyer returns the wrong size run or swaps sizes after delivery. You record the approved exchange as a credit or refund against the original invoice. If the invoice is already paid, the exchange becomes an adjustment on it, not a second charge. Finance sees one clear adjustment.
How do you take a deposit on a custom uniform order?
Send the buyer the approved artwork, size run and quote together with a payment link or signed deposit request, then collect the deposit before production. The payment record keeps the order number and approval reference, so the deposit is matched to the accepted design and not to a guess.
How the deposit request runs
A uniform supplier confirms the design, logo placement, fabric and size run with the buyer. Your staff then send a payment link or a Contracts & eSignatures request with the deposit amount and the order number as the reference. The buyer signs, pays and receives a receipt. Production starts when the deposit shows as paid.
Deposit terms and artwork changes
Agree what the deposit covers, what happens if artwork changes and who may approve the order. To reuse a card for the balance, ask for the cardholder's authorization first. When the quantity changes after approval, issue a new request or an adjustment instead of editing a paid record.
A school-wear polo order, deposit first
Say a school-wear supplier agrees a custom polo order with a district's purchasing office: embroidered logo, a size run from youth small to adult XL and a $2,400 deposit. The deposit link carries the quote number and the approved artwork file name. The balance invoice later references the same order.
How can a retailer pay a partial seasonal shipment?
Yes. For garment wholesale invoice payments, invoice each shipment separately, or apply a part payment to an open invoice, and keep the shipment reference on every payment. The retailer pays what has arrived, and your reporting shows the remaining balance. A part payment does not change the agreed terms and is not financing.
How a split shipment is collected
A retailer's fall order ships in three waves. Your staff issue an invoice for each shipment with a payment link, and the buyer pays that link in full or enters a partial amount you allow. Each payment carries the invoice number and the shipment reference. Open balances stay visible in your reports.
Part-payment rules and failed payments
Decide up front whether part payments are allowed and who may approve them. Backordered items stay off the invoice until they ship, so the buyer never pays for goods still waiting. If a payment fails, resend the link instead of keying the card again without the buyer's agreement.
Three waves of knit tops
Say a boutique orders 300 knit tops for fall. The first shipment of 120 is invoiced at $3,600 and paid by link. The second shipment of 100 is paid in two parts. The last 80 are backordered, so that invoice is not issued until they ship.
RapidCents products for apparel and uniform wholesalers
Uniform supplier merchant services at RapidCents pair Invoicing, Payment Links, Contracts & eSignatures and Bank Payments with Virtual Terminal and Reporting. Together they follow the supplier sequence: approved order, deposit or invoice, authorized collection, receipt, credit and reconciliation.

The RapidCents invoices screen: outstanding, overdue, paid and draft totals across the top, the invoice list below them, and a preview of one invoice on the right with its line items and a View & Record Payment button. Invoicing
RapidCents invoicing helps professional services, contractors and B2B suppliers create branded invoices…
Explore
The RapidCents payment links screen listing created links with their amount, status, click count and whether they have been paid, beside a phone showing the branded page a customer opens to pay $2,500.00. Payment Links
RapidCents payment links let staff generate branded pay-by-link URLs for invoices, deposits, balances and…
Explore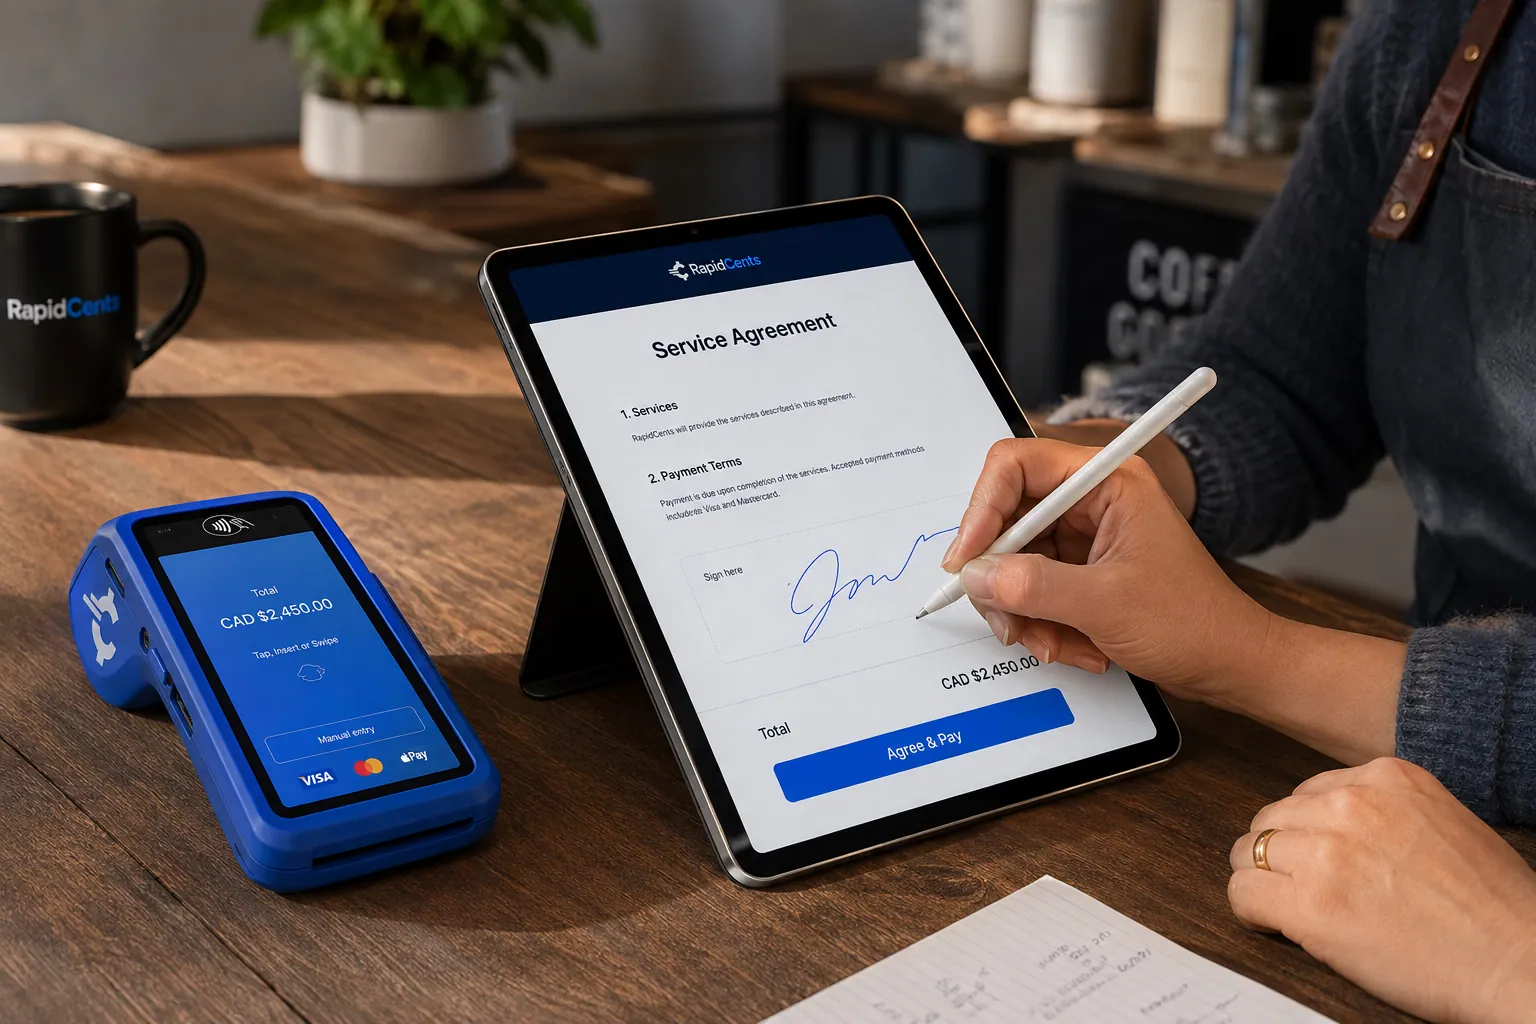
A merchant sends a RapidCents contract for e-signature with payment attached, terminal ready for an in-person counterpart. Contracts & eSignatures
Quotes, service agreements and enrolment forms usually end in a payment. Send the document, capture the…
Explore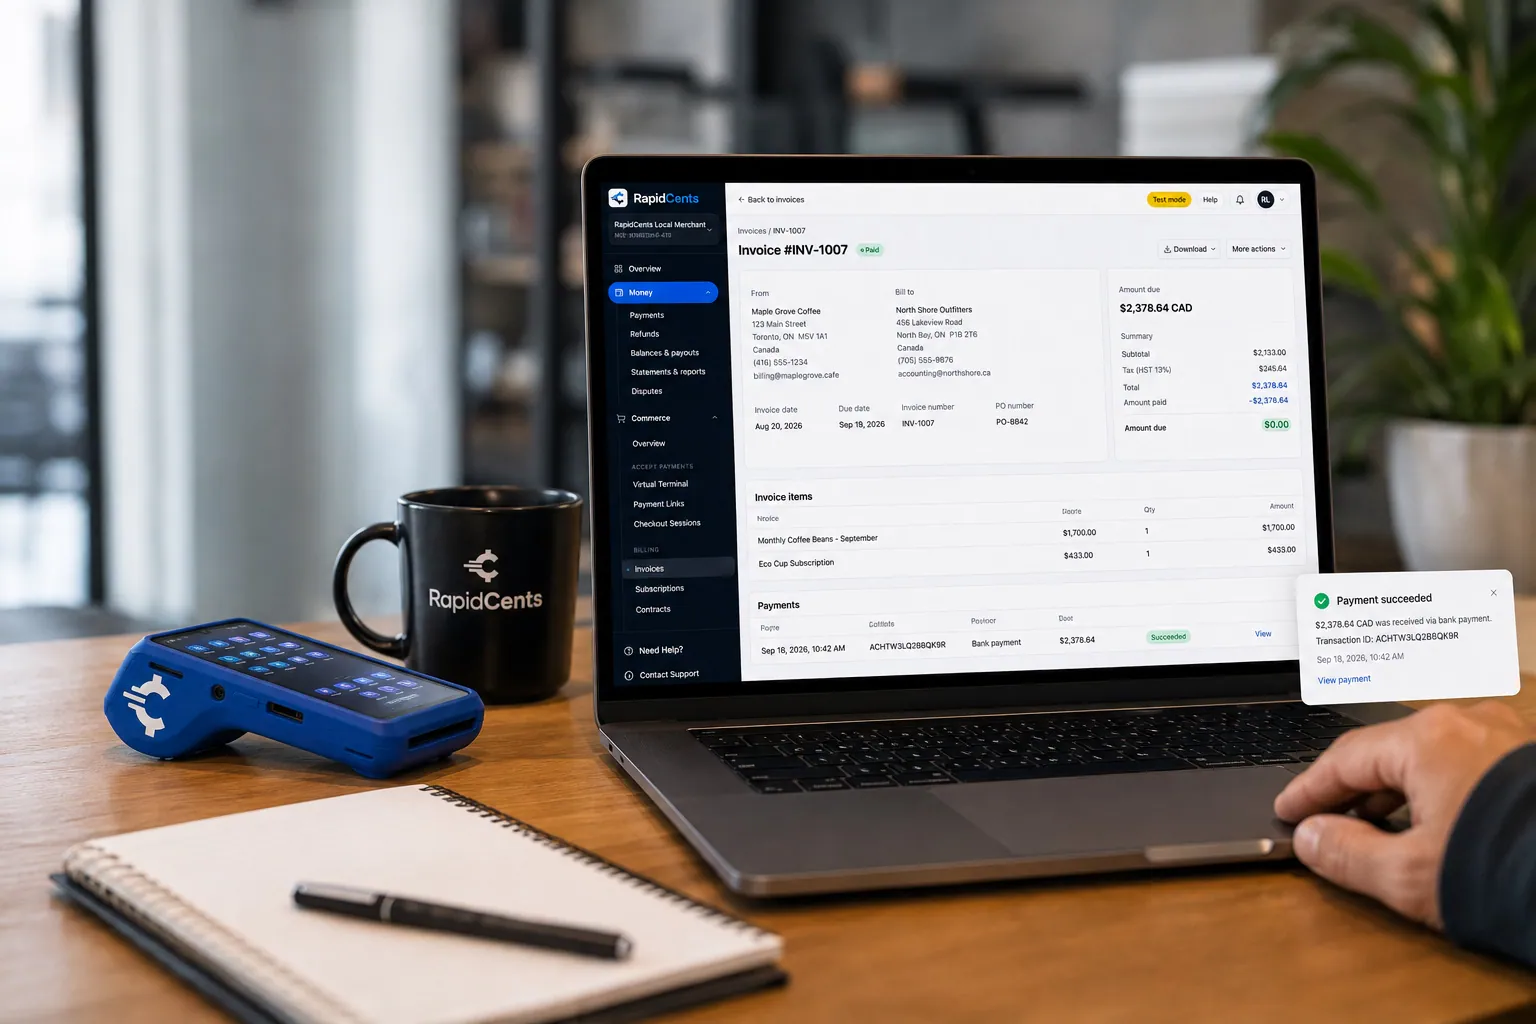
A merchant invoices a customer for bank debit through RapidCents, with card terminal capture available on the same desk. Bank Transfer / Bank Payments
Bank payments suit recurring and high-value invoices where card fees are the wrong tool. Collect directly…
Explore


How should a size exchange affect a paid invoice?
Record the approved exchange or credit against the original invoice and keep the paid invoice intact. Refund the card only when the buyer is owed money back, and avoid raising a second charge that duplicates the first. Finance then sees one adjustment tied to the return authorization.
How an exchange is recorded
A buyer reports the wrong size run and you approve a return. Your staff note the return authorization against the paid invoice. If the replacement costs the same, record an exchange. If it costs less, refund the difference to the original card. If it costs more, send a payment link for the difference.
Return rules, credit notes and disputed returns
Set the return window and exchange rules in your terms before you ship. A credit note reduces what the buyer owes on the account, while a refund returns money to the card. For a disputed return, keep photos, shipping proof and the written approval.
Scrub tops in the wrong size
Say a uniform supplier ships 60 scrub tops to a clinic group, and 12 arrive in the wrong size. Your staff approve the return, ship the replacements and record the exchange against the paid invoice. No new charge is made, and the file shows one adjustment tied to the return number.
How do you compare textile distributor credit card processing costs?
Costs depend on your card mix, ticket size and how cards are taken. RapidCents prices on interchange-plus: interchange at cost, your RapidCents markup in your Fee Schedule, and fees for equipment or services if applicable, month to month with no fixed term. Use Fee Check to see interchange separated from markup.
What drives your cost
Interchange varies with card type, such as debit, credit, premium or commercial, and with how the card is taken. Keyed and online payments differ from tapped or inserted ones. Large B2B invoices paid by commercial card behave differently from small reorders, so your mix matters more than any headline.
What to bring to a comparison
Bring recent processing statements, your card mix, average invoice and deposit size, the split between invoice links, phone orders and counter sales, and your refund and chargeback volume. Ask for every quote in writing, with the markup and equipment or service fees listed apart from interchange.
Commercial cards and enhanced data
Large buyers often pay with purchasing or commercial cards. Enhanced Level 2 and 3 data can be passed where it is supported for your setup, and your RapidCents representative will tell you what applies to you. Do not assume a particular qualification or a lower cost from sending extra data.
Which order and accounting software can work with RapidCents payments?
RapidCents connects settled transactions, fees and refunds to QuickBooks Online and Xero, and SAP and NetSuite import settlement files. RapidBridge takes payments inside web-based order software such as Acumatica and Dynamics 365 Business Central. Tell your RapidCents representative what you run and they will map out the options.
NetSuite and SAP Business One
Wholesale suppliers often run orders, inventory and receivables here. SAP and NetSuite import RapidCents settlement files, so settled payments, fees and refunds land against your invoices. Your RapidCents representative will help you map invoice and customer references for your edition. This is an import, not a live connector.
Dynamics 365 Business Central, Acumatica and Epicor Prophet 21
RapidBridge works with Dynamics 365 Business Central and Acumatica, so a card payment posts against the invoice you already have open, with no change to the software. For Epicor Prophet 21, RapidCents integrates with many major platforms through APPIE and RapidBridge. The right option depends on your edition and version, and your RapidCents representative will walk you through it.
QuickBooks Online and Xero
Smaller wholesalers often keep their books here. Settled transactions, fees and refunds map to either one, including deposits, exchanges and credit notes. Invoice payment links also work outside the software, so a buyer can pay from the email you send.
Payment options for apparel wholesalers by country
RapidCents serves merchants in Canada and the United States. The payment methods, bank-payment options and settlement currency you can offer follow the country of your merchant account, and your RapidCents representative will walk you through what fits before you quote a buyer.
Cards
Major card brands such as Visa, Mastercard and American Express are the common route for deposits and invoices by payment link, phone or counter. Debit options at the counter vary by country.
Bank payments and currency
Bank-payment schemes and the currency of settlement follow your account's country. Your RapidCents representative will show you the methods that fit, and you keep the order reference on every payment either way.
How do you switch processors without losing order history?
Inventory what is open, test the new flow, run both for a short period if needed, and reconcile before you close the old account. Stored cards do not move automatically, because both providers must agree to any transfer. Plan the move around your shipping seasons, not the other way around.
Take inventory first
List open invoices, unpaid deposits, partial shipments, stored cards with their authorizations, recurring schedules and pending exchanges. Export payment history and map each payment reference to the order, invoice and return number in your operational software.
Test, then run in parallel
Run a test sale, a deposit by payment link, a refund and a partial payment before you move live volume. Keep the old account running for open items. Avoid switching in the weeks when seasonal shipments and uniform season orders peak.
Reconcile before you close
Match deposits to the ledger by settlement report, then check fees and refunds against your Fee Schedule. Ask buyers to authorize their card again if tokens cannot be moved. Once your account is approved, your RapidCents representative walks you through each setup step and the timing.
Payment questions from apparel and uniform wholesalers
What is the best payment processor for apparel wholesalers?
The best processor is the one that fits how you collect, so compare written quotes against the same criteria. Look at invoice payment links, deposits and part payments, stored card authorization, refund and credit handling, reporting you can reconcile and software compatibility. Ask for interchange and markup separately. RapidCents is built around these jobs, and Fee Check shows interchange apart from markup on your statement.
How much does credit card processing cost for apparel wholesalers?
It depends on your card mix, invoice size and how cards are taken, so no single figure applies. RapidCents prices on interchange-plus: interchange at cost, your RapidCents markup in your Fee Schedule, and fees for equipment or services if applicable. Service is month to month with no fixed term. Upload a statement to Fee Check to see interchange separated from markup.
Can NetSuite use a different payment processor?
Often, yes. SAP and NetSuite import RapidCents settlement files, so settled payments, fees and refunds land against your invoices. RapidCents also integrates with many major platforms through APPIE and RapidBridge. The right option depends on your NetSuite edition and how payments connect today, and your RapidCents representative will walk you through it.
How can apparel wholesalers switch processors without losing payment history?
Export your payment history first, then move in stages. List open invoices, deposits, partial shipments, stored cards and recurring schedules, test a sale, a deposit and a refund on the new account, and run both for a period if needed. Stored cards move only if both providers agree; otherwise buyers authorize again. Reconcile settlements to your ledger before closing the old account.
Which payment options can an apparel wholesaler offer by country?
It depends on the country of your merchant account. RapidCents serves merchants in Canada and the United States, and card acceptance is the common starting point for deposits and invoices. Debit options, bank payments and the settlement currency differ by country, and your RapidCents representative will walk you through the methods that fit your business.
How is a custom-uniform deposit linked to approved artwork?
Keep the accepted design, size run and payment milestone together on the order, and use the order number as the payment reference. Send the deposit link or signed request only after the buyer approves the artwork. If the design or quantity changes, issue a new request or an adjustment instead of editing a paid record. Your order system holds the artwork file.
Can a retailer pay a partial seasonal shipment?
Yes, when you invoice by shipment or allow part payments on an open invoice. Use the shipment and invoice references on each payment link, and your reports show the remaining balance on every open invoice. A part payment is a collection step, not financing, and it does not change the agreed terms. Backordered items should stay off the invoice until they ship.
How should size exchanges affect a paid invoice?
Record the approved exchange or credit against the original invoice and avoid creating an unexplained duplicate charge. Refund the original card only if the buyer is owed money, send a payment link for any extra amount, and note the return authorization on each record. Credit notes sit in your accounting software, while a refund moves money back to the card.
Can we charge a stored card for repeat uniform orders?
Yes, if the buyer authorizes it. Get written agreement to the stored card, the kind of orders it covers and how to cancel before you charge it. Recurring charges also need agreement on amount and timing. Each charge should show the order reference, and a declined card goes back to the buyer for a new payment.
How do bank payments compare with card payments on large orders?
Bank payments can suit large, repeat invoices, while cards suit deposits and buyers who want a familiar way to pay. Compare total cost across both using your real invoice sizes, plus how each handles failed payments, disputes and reconciliation. Your RapidCents representative will walk you through the bank-payment options for your country and account.
What MCC is used for apparel, textile and uniform wholesalers?
MCC 5137 is commonly associated with uniform and commercial clothing sellers. RapidCents sets your merchant category with you during onboarding, based on what your business actually sells, so a mix of uniforms, general apparel and textiles is reviewed as a whole.
Related wholesale industries
Our B2B & Wholesale overview covers the shared invoice, purchase order and net terms workflows. Computer and IT distributors, commercial furniture suppliers and office and school suppliers share the deposit and credit note routines. Retailers collecting from their own customers have their own page.
B2B & Wholesale
Collect net-terms invoices by payment link with the PO number attached, take commercial…
Computer & IT Distributors
RapidCents helps computer and IT hardware distributors collect approved reseller…
Electronic Component Distributors
Collect purchase order invoices, allocation deposits and partial-shipment balances from…
Office & School Suppliers
Collect payment from schools, districts and offices that buy stationery and supplies from…
Commercial Furniture Suppliers
RapidCents helps commercial furniture suppliers collect fit-out deposits, delivery…
Beauty & Salon Suppliers
Collect reorder invoices, equipment deposits and phone orders from salon trade accounts…
Pet Product Wholesalers
Collect from pet retailers on approved invoices, trade-account reorders and credits, with…
Dental Suppliers
From monthly consumables reorders to chair and imaging deposits, collect what clinics…
Take the next step
Review your wholesale payment workflow
Upload a recent processing statement to Fee Check and see interchange separated from your markup, then walk through deposits, partial shipments and exchanges with RapidCents.
- No obligation
- Payment specialists, not a call centre
- Secure statement upload



